


Constellation Energy (CEG) Could Be 25% Undervalued After Amazon Google Deals And DOE Loan
Constellation Energy (CEG) has moved to the center of the clean power conversation after two key developments: long term contracts with Amazon and Google, and a conditional US$5b federal loan commitment.
Despite the new contracts and federal support, Constellation Energy’s share price has retreated, with the year-to-date share price return down 28.36% and the 1-year total shareholder return down 30.01%, even after a very large 3-year total shareholder return of 128.47% that points to longer-term momentum still in place.
Compare Constellation Energy’s pullback and nuclear expansion story with other power players by scanning 39 power grid technology and infrastructure stocks benefiting from rising data center demand and grid investment themes.
Constellation Energy now trades at a clear discount to both analyst targets and some intrinsic estimates after that sharp pullback. Is the market prudently pricing nuclear risk, or misjudging the value of those 20 year tech contracts and federal backing?
Most Popular Narrative: 25% Undervalued
Constellation Energy last closed at $262.38. The most followed narrative, which pegs fair value at $350, frames that gap as a sizeable discount and anchors the current pullback in a long-term nuclear scarcity story.
The market is underappreciating how scarce true 24/7 carbon-free baseload has become just as AI data centers and electrification drive the sharpest sustained rise in U.S. power demand in decades. Most investors still treat CEG as a “utility with nuclear exposure.” It is better understood as the owner of the largest, highest-quality fleet of scarce, dispatchable zero-carbon generation that hyperscalers cannot easily replicate or replace.
See why 27 investors see Constellation Energy as 25% undervalued.
According to Andrei_Niculescu, who authored the narrative, the key point is that Constellation Energy controls a large fleet of nuclear assets and is already signing long contracts tied to that scarcity. The view is that this contracting momentum supports a fair value of $350, which is well above both the current share price and some traditional models that focus mainly on near term earnings multiples.
Result: Fair Value of $350 (UNDERVALUED)
Still, Constellation Energy’s story can break if nuclear projects face cost overruns or if regulators tighten rules around uprates and data center load.
Find out about the key risks to this Constellation Energy narrative.
Another View: What Multiples Say About Constellation Energy
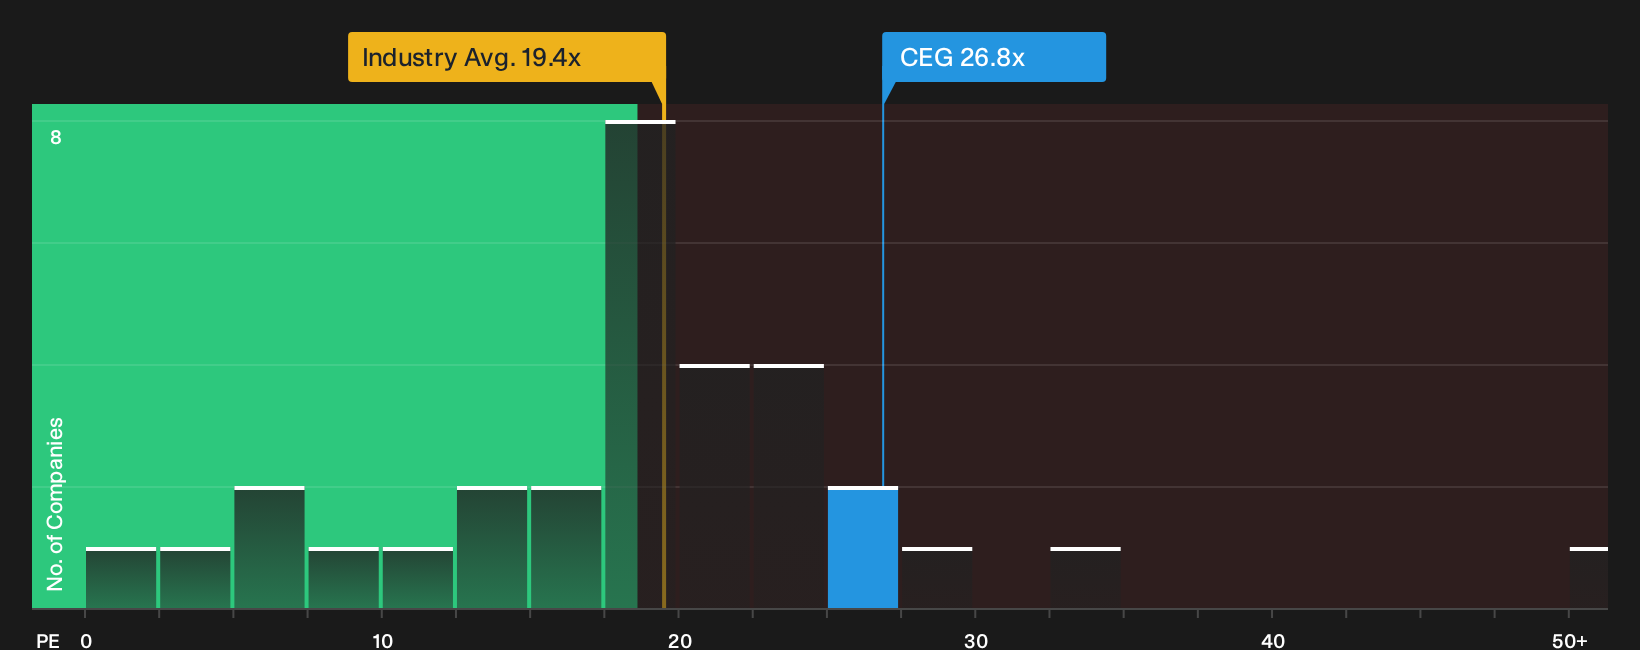
There is a catch. Constellation Energy screens cheap on some intrinsic estimates, yet its 26.8x P/E is richer than the US Electric Utilities group on 19.4x and above the peer average of 23.2x, while still below a fair ratio of 29.6x. That combination suggests both potential upside and valuation risk. Which signal do you trust more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Constellation Energy’s story so far. Move quickly, review the full picture of both risks and potential upsides, and weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Constellation Energy?
If you stop with Constellation Energy, you only see part of the opportunity set. Let the data point you toward fresh ideas that fit your style.
- Target steadier potential outcomes by checking companies in the 30 resilient stocks with low risk scores that focus on resilience when conditions change quickly.
- Chase quality at a discount and review the 18 high quality undiscovered gems that may not yet be crowded with institutional attention.
- Build a foundation of financial strength by scanning the list of solid balance sheet and fundamentals (25 results) so your next idea starts from a position of balance sheet discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com