


Ono Pharmaceutical (TSE:4528) Stock Sours As Q2 Results Feed Profit Doubts
Ono Pharmaceutical closed on Friday at ¥2,256, leaving the stock down roughly 10% over the past week as traders reacted coolly to fresh numbers. The company just reported Q2 2027 results with basic earnings per share of ¥44.21 on revenue of ¥116,344m, and the immediate read was that the quarter lacked spark.
That short term verdict misses the bigger tension. Trailing 12 month earnings are up sharply with net profit margin at 15.2%, yet analyst forecasts still point to declining profits over the next three years. The real story now is the growing gap between a richer margin profile and a market that is pricing in earnings decay.
Like the earnings power at Ono Pharmaceutical but uneasy about analyst calls for profits to fade? Check out the list of solid balance sheet and fundamentals stocks (21 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥116,344m vs. ¥129,600m (top line declined 10.2%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥20,779m vs. ¥22,416m (profit slipped 7.3%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥44.21 vs. ¥47.71 (earnings per share fell 7.3%)
- Trailing 12-Month Net Profit Margin (Q2 2027 vs Q2 2026): 15.2% vs. 9.6% (margin improved by 5.6 percentage points)
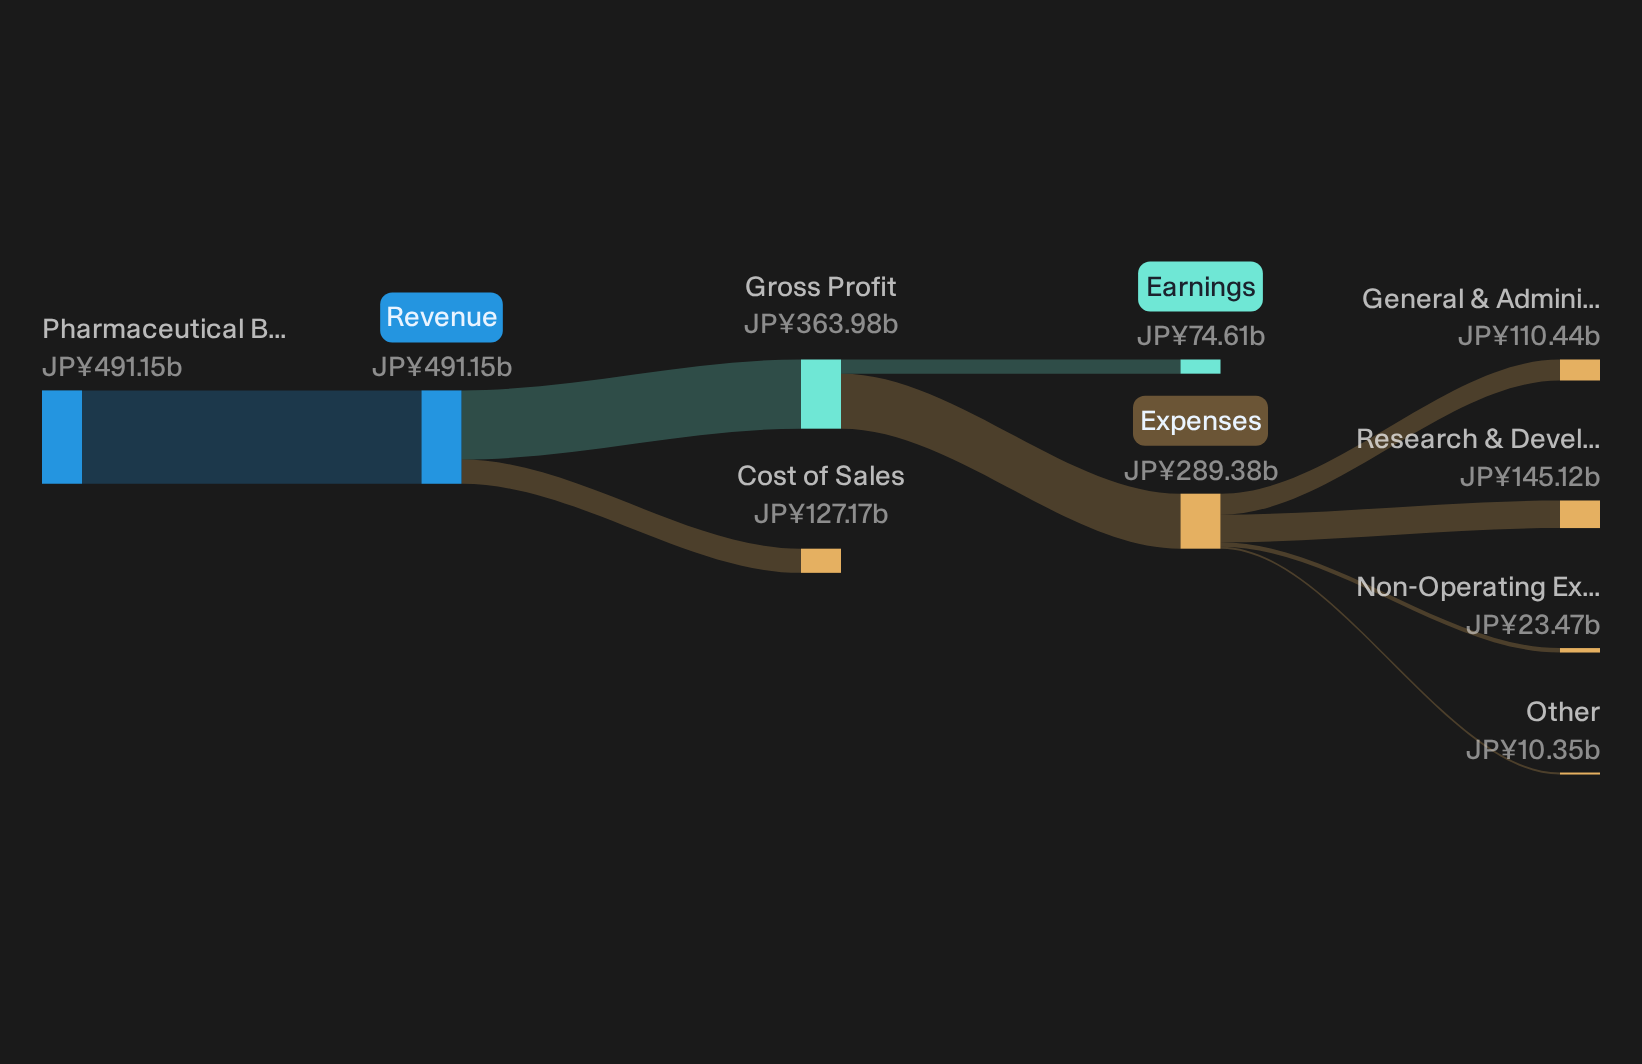
Ono Pharmaceutical’s results and the bullish angle
Ono Pharmaceutical still gives supporters a few clear hooks. Net profit margin over the past 12 months sits at 15.2%, above the 9.6% level a year earlier, so the earnings engine is running more efficiently even as quarterly revenue is lower. Recent deals in autoimmune and neurology, plus efforts to defend Opdivo royalties, also fit the picture of a broad, resilient portfolio. For investors who prefer companies with a long list of oncology and chronic disease franchises, this set of results does not clearly undermine that quality story.
Short term softness and validation for skeptics
Bears get something concrete too. Quarterly revenue declined 10.2% year on year and basic EPS fell 7.3%, which aligns with concerns about pressure on mature drugs and rising competition. The share price is down almost 10% over the past week and 5.4% over three months, so the market has already leaned toward that cautious view of Ono Pharmaceutical. Deals that add pipeline depth may be helpful, but they come against a backdrop of shrinking quarterly sales, which keeps the risk narrative in focus.
After shrinking quarterly sales and pressure on mature drugs, the key question is resilience. Review the risk analysis for Ono Pharmaceutical which shows 1 important warning sign to see whether this earnings wobble hints at deeper structural issues that are not yet fully priced in.Hunt For Quiet Earnings Mispricings
Ono Pharmaceutical just showed how a richer margin profile can still sit alongside a cautious share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 32% below our estimate - pairs a multi rail online gateway with cashless and instant payout tools enterprises plug directly into workflows.
- Company 2 - 42% below our estimate - sells low code workplace software teams adopt once spreadsheets and email chains collapse under growing processes.
- Company 3 - 24% below our estimate - supplies embedded form and data engines firms use once manual document handling blocks timely billing and analysis.
That is three of the list. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com