


Brookfield Wealth Solutions (BNT) Could Be 17% Overvalued As Earnings Reassure Investors
Brookfield Wealth Solutions (BNT) drew investor attention after reporting distributable operating earnings of US$488 million for the quarter, alongside US$35 billion in liquidity and continued integration of Just Group.
Brookfield Wealth Solutions shares have climbed over the past month, with a 30 day share price return of 7.37% and a 7 day gain of 3.32%, even though the year to date share price return is down 16.00% and the 90 day move has fallen 9.22%. This hints that momentum is rebuilding after a weaker spell. At the current US$39.21 share price, investors are weighing those stronger distributable operating earnings and US$35b liquidity against a 1 year total shareholder return that declined 14.35%. This is set against a much stronger 3 year total shareholder return of 80.71% and 5 year total shareholder return of 18.49% that reflect how the story has played out over a longer stretch.
Scan other insurance and retirement plays that show similar momentum and capital strength in our curated list of 30 resilient stocks with low risk scores.
After that rebound and a US$39.21 price tag, the spread between Brookfield Wealth Solutions' market value and intrinsic estimates looks wide enough to matter. So where does fair value genuinely cluster within that range?
Price-to-Earnings of 112.2x: Is it justified?
Brookfield Wealth Solutions changes hands at $39.21, and the SWS checks show that this lines up with a P/E near 112.2x, which is a rich tag against insurance peers.
The P/E ratio compares the current share price with the most recent earnings per share and gives a quick read on how much investors are willing to pay for each dollar of profit. For a retirement and insurance platform like Brookfield Wealth Solutions, that multiple often reflects expectations around long term annuity earnings, underwriting discipline, and how efficiently the balance sheet is used.
Here the earnings picture is mixed. Net income sits at $125.0m on $11.85b of revenue, so the net margin is around 1.1%, and that margin has declined from 5.5% in the prior year. Over a five year stretch, profits have grown at 30.6% per year, yet the most recent period shows a fall in earnings of 84.2%. With return on equity at 1%, the current valuation implies the market is willing to pay a high price for profits that are both thin and recently under pressure.
The comparison to peers is stark. The SWS checks flag Brookfield Wealth Solutions as expensive versus both the direct peer group average P/E of 12.8x and the broader US insurance industry average of 11.5x. That means the multiple is more than 8x the sector level, which is a very large premium that is consistent with investors expecting materially different earnings power ahead.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 112.2x (OVERVALUED)
Still, the thin 1.1% net margin and 1% return on equity leave Brookfield Wealth Solutions exposed if earnings wobble again or if investor patience with a triple digit P/E fades.
Find out about the key risks to this Brookfield Wealth Solutions narrative.
Another View on Brookfield Wealth Solutions' Value
The high P/E paints Brookfield Wealth Solutions as expensive, yet the SWS DCF model lands differently. At a future cash flow value estimate of $32.63 against a $39.21 share price, the stock screens as overvalued on this method too. So what is really driving that gap in expectations?
Look into how the SWS DCF model arrives at its fair value.
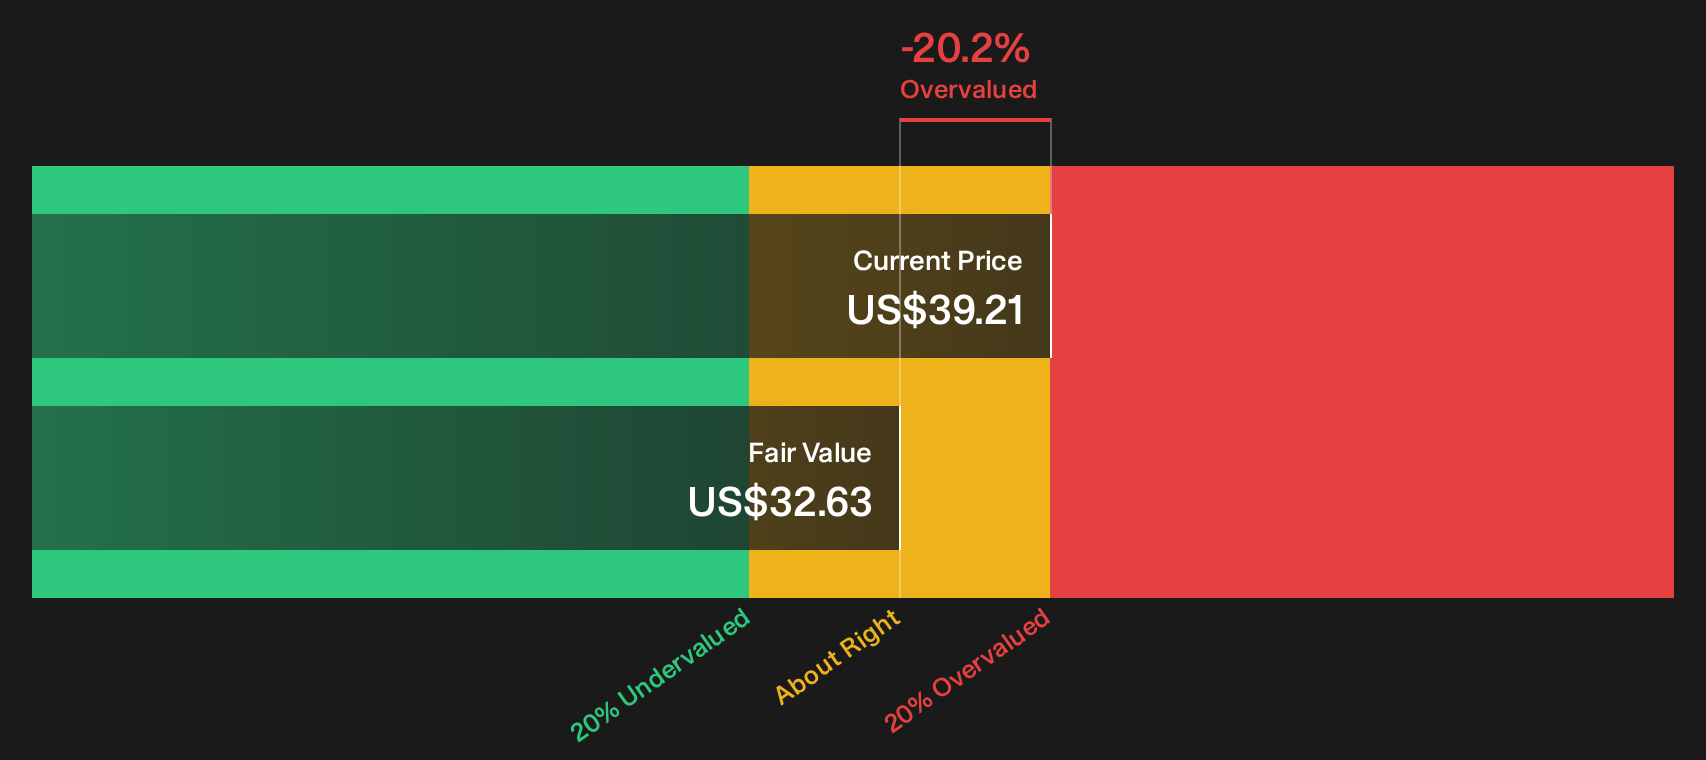
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brookfield Wealth Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the combination of high expectations and limited returns around Brookfield Wealth Solutions feels uneasy, act quickly and examine the numbers yourself, including the 2 important warning signs.
Looking for more Brookfield Wealth Solutions sized ideas?
If Brookfield Wealth Solutions leaves you cautious about concentration risk, consider widening your search. Use focused stock lists to filter for stronger balance sheets, income streams, and potential opportunities.
- Hunt for potential bargains that combine quality with a discount by scanning the 29 high quality undervalued stocks before prices reflect underlying fundamentals.
- Build a steadier income stream by reviewing the 5 dividend fortresses that focus on higher yield payouts with robust coverage.
- Prioritise resilience and capital protection by screening through the list of solid balance sheet and fundamentals (25 results) to identify businesses with greater financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com