


Is Live Nation Entertainment (LYV) Cheap Following Its Strong Quarter And Muted Market Reaction?
Market reaction to Live Nation’s strong quarter
Live Nation Entertainment (LYV) drew fresh attention after reporting a Q2 in which revenue grew 9.4% year on year and attendance approached 49 million fans, yet the share price slipped following the release.
For context, Live Nation Entertainment trades at US$177.89, with a year to date share price return of 22.42% and a 1 year total shareholder return of 18.97%. The 3 year total shareholder return of 108.40% suggests momentum has been strong over a longer horizon, even if the recent reaction to Q2 hints at investors reassessing how much growth is already reflected in the current valuation.
Scan how investors are pricing Live Nation Entertainment’s Q2 momentum against other event, media, and entertainment operators by reviewing the handpicked 18 high quality undiscovered gems.
Live Nation Entertainment now trades at a discount to both analyst targets and one intrinsic value estimate, even after that strong Q2 update and muted share reaction. Is the caution in the current price still warranted?
Most Popular Narrative: 12% Undervalued
Live Nation Entertainment’s most followed narrative points to a fair value of $201.96 per share, which sits above the recent $177.89 close and presents the post Q2 pullback as a gap between courtroom risk and long term venue economics.
Expansion of Live Nation Entertainment into underpenetrated international markets, where Latin America activity is reported at one tenth of U.S. levels and Japan and Western Europe show meaningful headroom, could lift long term ticket volumes and concert revenue as fan activity in these regions closes the gap.
See why 21 investors see Live Nation Entertainment as 12% undervalued.
Result: Fair Value of $201.96 (UNDERVALUED)
Still, the legal overhang around Ticketmaster, including the US$450 million accrual and the upcoming remedies trial, could reshape Live Nation Entertainment’s economics if outcomes tighten contracts or add new costs.
Find out about the key risks to this Live Nation Entertainment narrative.
Another View: What The DCF Says About Live Nation Entertainment
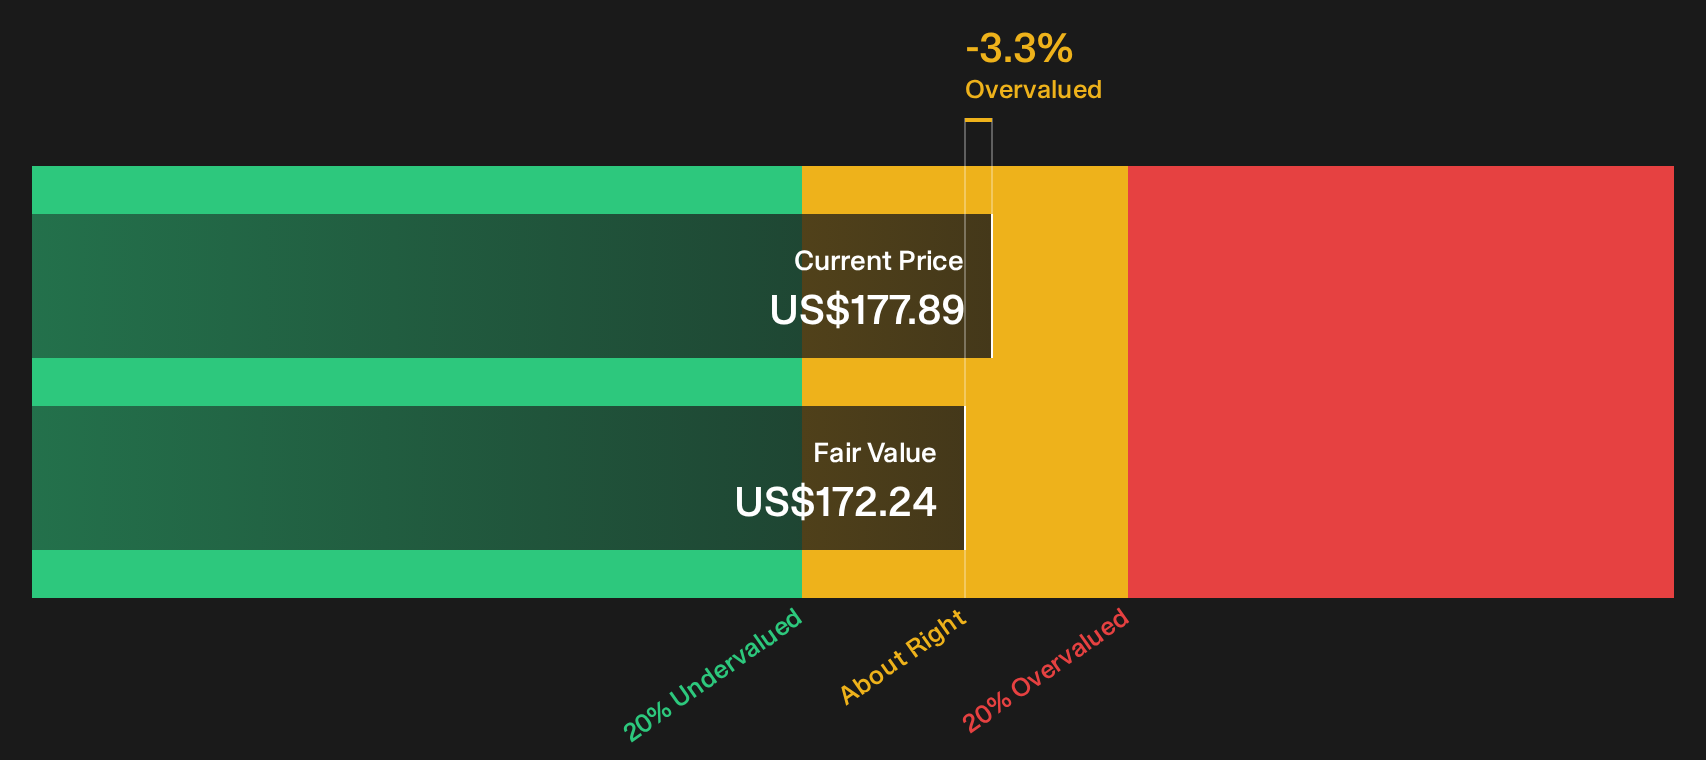
The earlier narrative leans on Live Nation Entertainment’s analyst fair value of $201.96, which frames the stock as 12% undervalued versus the recent $177.89 price. A different tool, the Simply Wall St DCF model, lands just below the market at $172.24, which suggests only a small premium baked into today’s quote.
That gap between a higher analyst target and a more restrained cash flow estimate leaves you with a simple question. Which set of assumptions about long term cash generation feels closer to how you see Live Nation Entertainment’s venue buildout and Ticketmaster economics over time?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Live Nation Entertainment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Live Nation Entertainment story points to optimism, yet the real edge comes from pressure testing the numbers yourself and moving with intent. To see what is driving that optimism and how it stacks up against the risks, review the 1 key reward
Looking for more investment ideas beyond Live Nation Entertainment?
If you stop at Live Nation Entertainment, you miss the wider opportunity set. Broaden your watchlist and pressure test your thesis against other high quality businesses.
- Target steadier compounding by scanning a curated 29 high quality undervalued stocks that couples solid fundamentals with prices that have not fully caught up.
- Strengthen income potential by reviewing a focused 5 dividend fortresses that highlights companies pairing higher yields with business resilience.
- Dial down portfolio risk by filtering a 30 resilient stocks with low risk scores designed to surface resilient balance sheets and more predictable cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com