


Essity (OM:ESSITY B) Could Be 46% Undervalued On Mixed Q3 Earnings
Essity earnings event and why it matters now
Essity (OM:ESSITY B) just reported third quarter and nine month 2026 results, with higher sales alongside lower net income and earnings per share, a mix that tends to sharpen investor focus on profitability drivers.
Essity’s 1 month share price return of 8.07% and 6.87% year to date rise to SEK280.0 suggests investors are leaning toward the sales story despite weaker earnings, while the 11.21% 1 year total shareholder return points to steadier support over a longer horizon.
Compare Essity’s mixed earnings reaction with a curated set of resilient balance-sheet plays by scanning the list of solid balance sheet and fundamentals (203 results) that may handle profit pressure differently.
Essity’s recent climb puts a spotlight on a simple tension. Are investors backing a sturdier hygiene business, or just repricing sentiment after mixed earnings? And how does that show up in the valuation work ahead?
Most Popular Narrative: 4% Overvalued
Essity’s last close at SEK280 sits modestly above the most followed fair value estimate of SEK268.2, which frames the current move as a mild valuation stretch rather than a clear bargain.
Planned capex of about 6% of net sales, supported by net debt to EBITDA of around 1.0 to 1.1x and recurring SEK 3 b share buyback programs, is directed toward capacity and systems in higher return categories such as incontinence and Professional Hygiene, with the potential to lift revenue and earnings over time.
See why 19 investors see Essity as 4% overvalued.
Result: Fair Value of SEK268.2 (OVERVALUED)
Still, Essity’s story can break if weak volume trends persist in key categories, or if higher input and SG&A costs compress margins faster than planned savings help.
Find out about the key risks to this Essity narrative.
Another View: Essity through the cash flow lens
The market has Essity at SEK280, while analyst fair value estimates cluster around SEK268.2 and imply a mild premium. A different tool, the Simply Wall St DCF model, points in the other direction, with Essity trading about 46.2% below an intrinsic value of SEK520.77. This raises a simple question: Is the market underestimating Essity’s future cash flows, or are the DCF assumptions too generous?
To stress test that gap between price, analyst targets and our DCF output, it helps to unpack how the cash flow model is built and what would need to change for Essity to move closer to that SEK520.77 figure.Look into how the SWS DCF model arrives at its fair value.
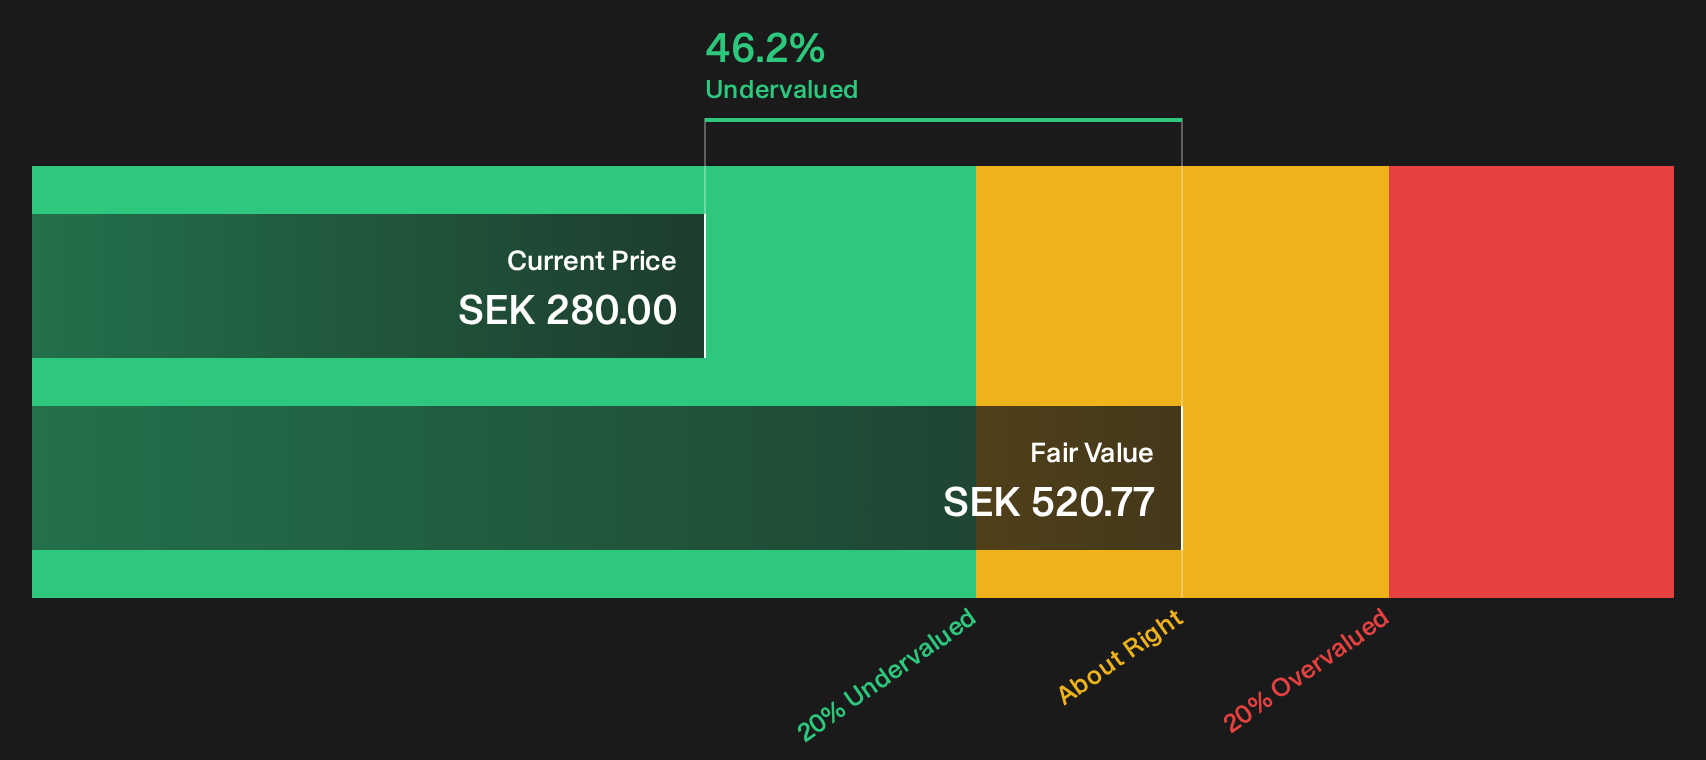
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Essity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Essity can make the story feel unresolved, which is exactly why it helps to inspect the numbers yourself while sentiment is still forming. To see what the optimism is built on, review the 2 key rewards
Looking for more Essity-sized investment ideas?
Essity shows how one stock can reshape a portfolio story, so broaden your watchlist now and give yourself more options before the next move hits.
- Target potential bargains that combine quality and valuation discipline by scanning 199 high quality undervalued stocks before prices move away from you.
- Strengthen your income stream by reviewing 221 dividend fortresses that aim to pair higher yields with resilience.
- Sleep easier through volatility by focusing on 218 resilient stocks with low risk scores built on sturdier fundamentals and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com