


Did Canadian Solar's 55% Drop Catch You Out? What Investors Missed
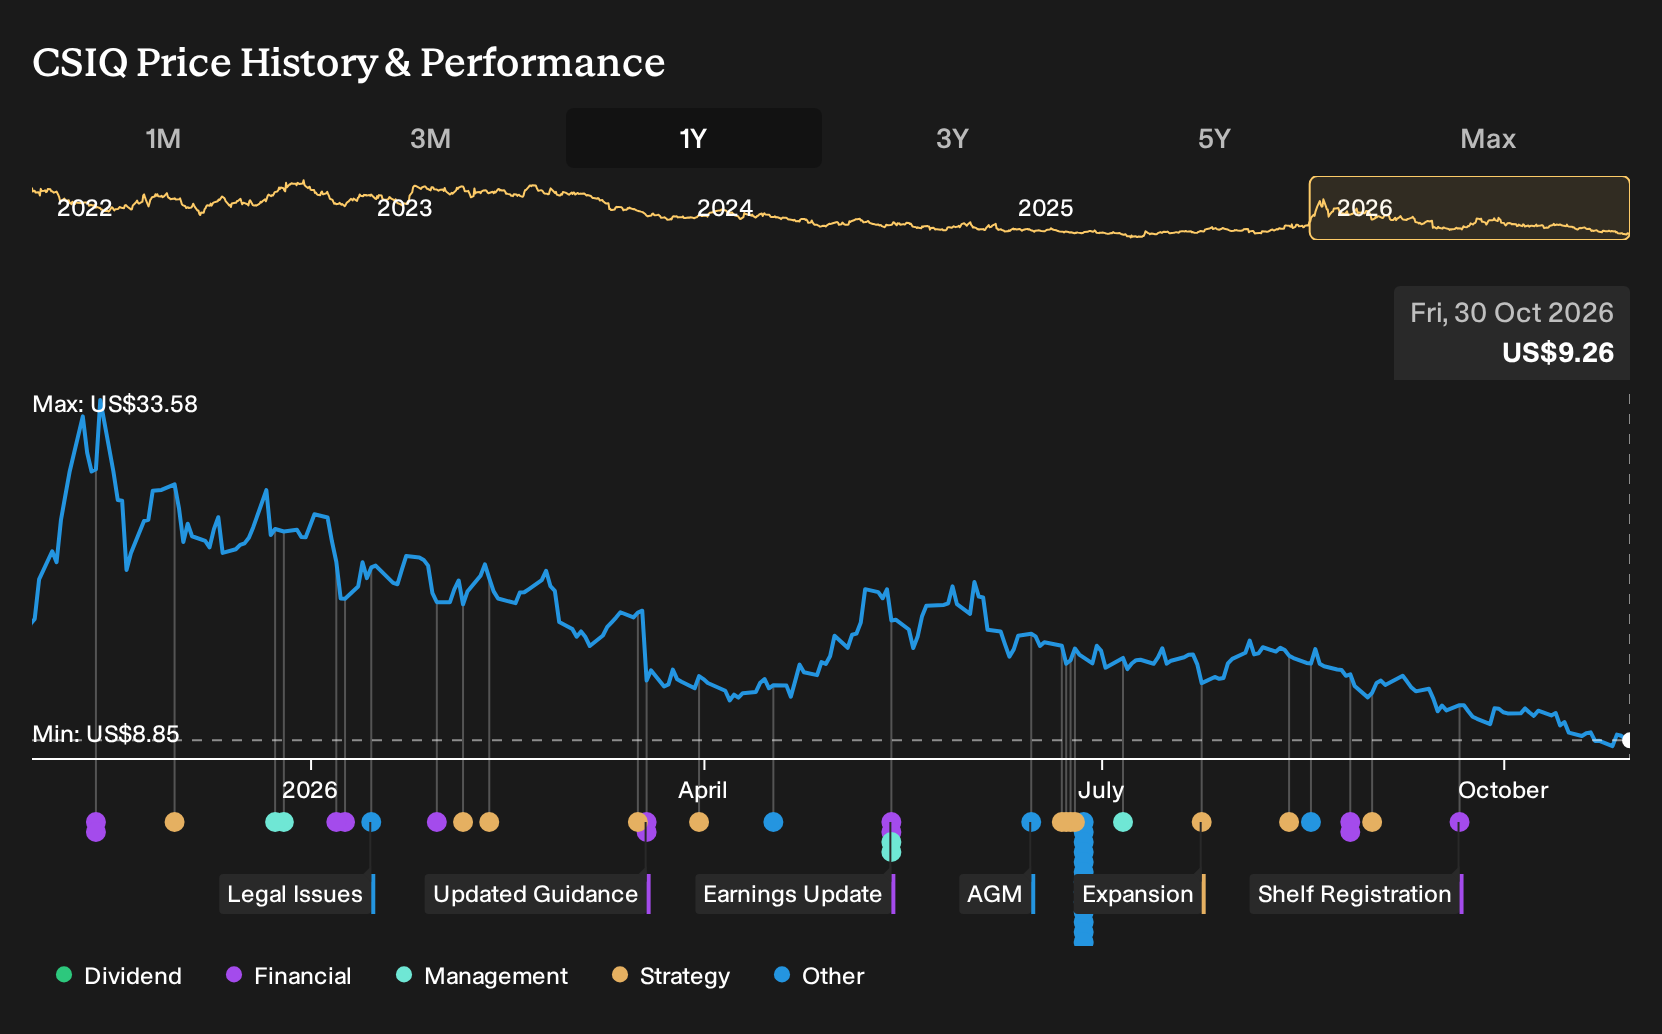
Canadian Solar’s sharp Q1 2026 share price drop after weak guidance grabbed headlines, but for anyone who owned the stock over the full year, that was just one chapter. Holding Canadian Solar over the past year would have meant a 55.4% loss, including dividends. If you had bought on 30 October 2025, knowing only the bullish and cautious analyst cases on record then, how should you now judge the shift to a profit-first playbook and storage expansion push?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Canadian Solar has already moved. Pinpoint other ways to investigate the theme among 39 power grid technology and infrastructure stocks.
What You Would Have Been Weighing Up With Canadian Solar
The shares cost US$17.94 at the start of the period, and investors had to choose between two very different stories about Canadian Solar.
On the bullish side, the Narrative set Fair Value at US$23, built on the idea that expanding U.S. manufacturing and tighter ESG compliance could support higher margins and premium contracts as regulations tightened.
The more cautious view put Fair Value at US$12.37, stressing the risk that heavy capital needs and rising costs might pressure free cash flow and limit earnings progress.
What The Results Changed For Canadian Solar
The clearest test came from Canadian Solar’s Q2 2026 results. Revenue fell from US$1,693.9m in Q2 2025 to US$1,207.7m, while a small prior profit turned into a US$76.9m loss and net margin moved from 0.4% to 6.4% in the red. That challenged the profit-first ambition and lent more weight to the cautious case that margin improvement was not yet showing up in the numbers.
The useful takeaway is simple. When a story leans on better future profitability, treat net margin as the key claim to test and track. Watch whether it actually trends higher in later reports before trusting the narrative.
What You Would Be Paying For Canadian Solar Today
Today Canadian Solar trades at US$9.26. The current bullish narrative argues that fair value sits above this price, based on the idea that investors are overpricing solar manufacturing risk and underpricing the rest of the group.
A buyer now would be assuming that Canadian Solar can eventually turn its CSI Solar stake, Recurrent and U.S. storage platform into durable cash generation for the Nasdaq parent.
"Canadian Solar is no longer simply a module manufacturer. The group contains several value pools with materially different economics, risk profiles, and potential valuations."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 46% below our estimate - enables large digital platforms to accept and send payments across fragmented local methods.
- Company 2 - 30% below our estimate - shifts hardware customers onto recurring AI networking and cloud infrastructure service contracts.
- Company 3 - 27% below our estimate - supplies grid testing gear utilities adopt as they upgrade electricity networks for electrification.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com