


What KB Home Investors Missed Before The Fall
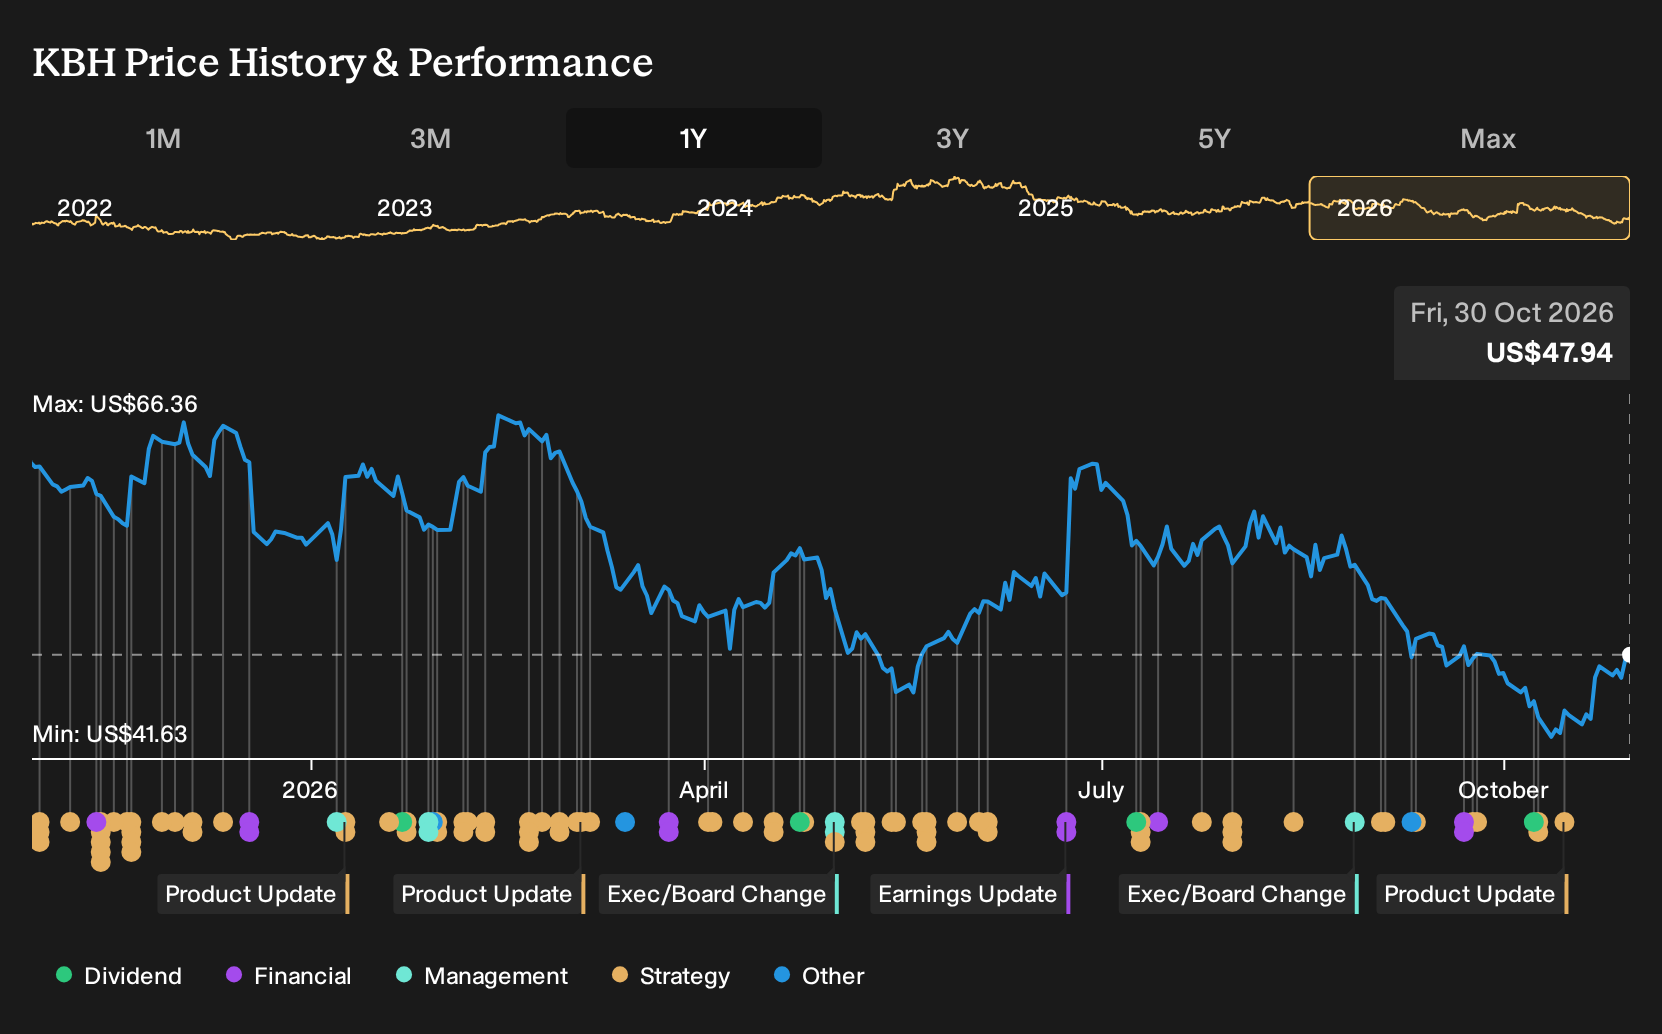
If you had looked at KB Home in late October 2025 and decided to sit it out while analysts argued over whether disciplined cost moves or falling first time buyer demand would matter more, the past year might look different today. Holding KB Home over the past year would have meant a 21.8% loss, including dividends. With that outcome in hand, which on record assumptions or early warnings would you want to re examine first?
KB Home has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Argument KB Home Investors Were Really Having
The shares cost US$62.38 at the start of the period, and anyone looking at KB Home then had to decide which story felt more realistic.
The optimistic Narrative pointed to a Fair Value of US$66, a notional target based on assumptions such as revenue growth falling 4.2% with profit margin at 6.8% and a future P/E of 11.6x. That view leaned on faster build times, new communities and tight cost control.
The cautious Narrative put Fair Value at US$49, using expectations for revenue to decline 3.4% a year while margins edged to 8.6%. This side focused on weaker first time buyer demand and rising development and regulatory costs as the key risk.
What The Results Changed For KB Home
KB Home’s later Q3 2026 update showed revenue down to US$1,297.1 million and net income at US$65.0 million, with net margin slipping to 5.0%. That weaker profitability challenged the optimistic case that tighter cost control would hold margins closer to 6.8%. It also gave more support to the cautious view that rising costs and affordability issues could weigh on returns.
The lesson is simple. When a story leans on cost discipline and pricing power, treat net margin as the key scorecard. For any other builder, compare the margin path management talks about with the margin they actually report each year.
What You Would Be Paying For In KB Home Today
KB Home now trades at US$47.94, with this Narrative’s Fair Value sitting above that level based on its own assumptions rather than a hard fact.
The argument leans on built to order focus, a heavier California mix, and share repurchases. A buyer today would need to believe those factors offset affordability pressure enough for orders and housing margins to hold up.
"KB Home’s growing pool of more than 1,500 sold homes that have not yet started construction creates a large, pre sold workstream that divisions can use to negotiate sharper trade pricing and steadier crew availability. This gives the company room to surprise on build costs and housing gross margin versus what current models assume."
The price and this Narrative do not agree. → Uncover what this Narrative says KB Home is actually worth
Looking Past KB Home
KB Home keeps attention on affordability, build cycles and local demand. One step away, another housing habit keeps quietly expanding.
People who buy new homes often refresh how they exercise, commute and spend weekends. That also shifts focus to what they wear and what supports their feet.
Athletic brands built on premium pricing and direct sales try to meet that urge. They prefer full price selling instead of filling constant discount racks.
When those businesses combine higher margin stores, new sports and fresh apparel, each shopper becomes more valuable. The unresolved tension is how durable that pricing power really is.
That argument has a Narrative and a number behind it. → See the company one Narrative values 87% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com