


Should Sales Growth Guidance Require Action From Ecolab (ECL) Investors?
- Ecolab reported third quarter 2026 revenue of US$4,694.8 million and net income of US$551.3 million, with full year to date revenue of US$13,176.3 million and net income of US$1,518.8 million, alongside guidance for 12% to 14% reported sales growth in the fourth quarter.
- The combination of higher year on year sales and only modest full year to date earnings movement suggests that pricing, mix and cost dynamics are all active levers for Ecolab. This matters for how durable its margin ambitions and capital spending plans might prove.
- We will now look at how Ecolab's guidance for 12% to 14% fourth quarter sales growth could influence its broader investment narrative.
Ecolab Investment Narrative Recap
To own Ecolab, you need to believe that consistent execution in water, hygiene and infection prevention can support earnings quality even when input costs and heavy industry demand are mixed. The latest quarter shows higher revenue but softer quarterly net income. As a result, the near term story hinges on pricing discipline and product mix holding up as costs and tariffs stay in focus.
The most important short term catalyst is management’s guided 12% to 14% reported sales growth for the fourth quarter, because it tests how well the One Ecolab playbook can translate into profitable volume. The biggest risk remains elevated capex and CoolIT related dilution squeezing free cash flow if margin progress stalls.
The earnings release for the third quarter of 2026 is the key announcement here. Ecolab reported US$4,694.8 million of revenue and US$551.3 million of net income for the period, with year to date sales of US$13,176.3 million and net income of US$1,518.8 million. That mix of healthy top line and relatively flat earnings keeps attention firmly on cost control and pricing power.
Guidance for double digit reported sales growth in the fourth quarter now acts as a live test of the growth engines investors often focus on, including Life Sciences, Digital and Global High Tech, while capital spending runs high. If revenue delivers against that range but earnings stay muted, the debate around margin ambition, tariff exposure and debt funded investment is likely to remain front and center for Ecolab holders.
Ecolab's narrative projects US$20.7b revenue and US$3.3b earnings by 2029, which implies 7.2% yearly revenue growth and an earnings increase of about US$1.2b from US$2.1b today.
Uncover why Ecolab's fair value indicates a 7% potential upside to its current price before the discount to Ecolab closes.
Exploring Other Perspectives
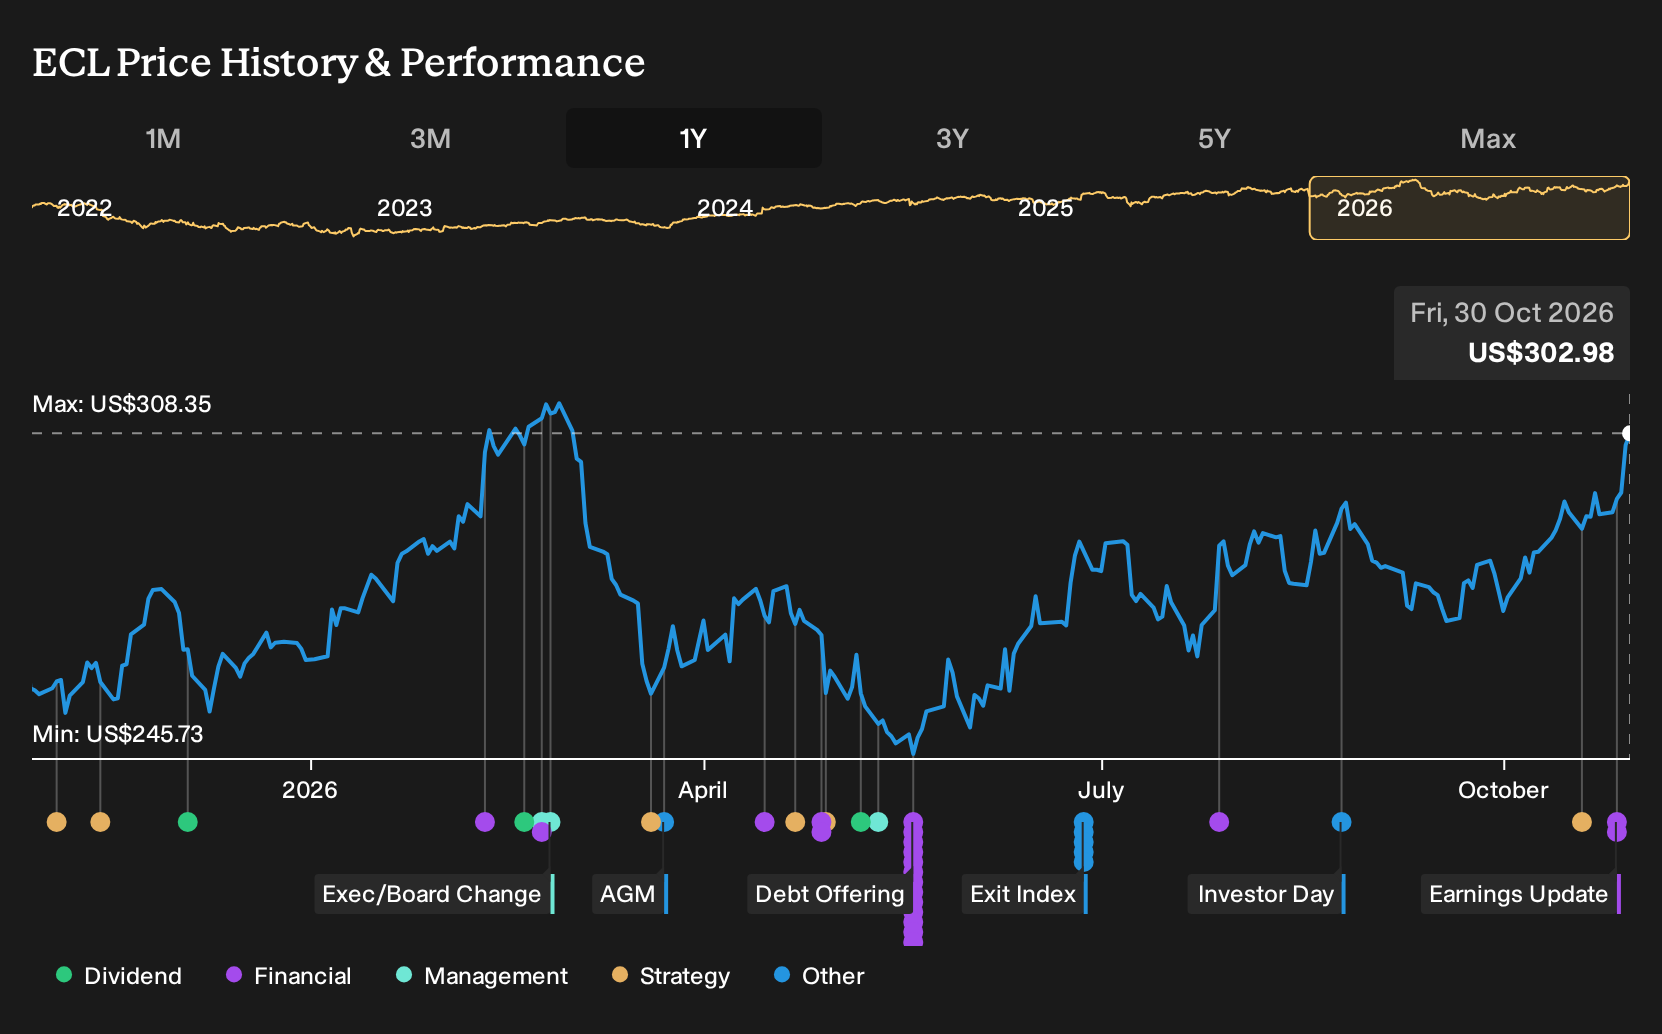
Fair value estimates for Ecolab from the Simply Wall St Community span roughly US$260.87 to US$324.95 across just 2 individual views, which already shows how far apart retail opinions can land. You can set those pre earnings figures against risks around tariffs, capex and heavy industry softness, then decide which narrative feels more convincing.
Explore another Ecolab fair value estimate, including one that suggests as much as 7% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Ecolab research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ecolab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ecolab's overall financial health at a glance.
Looking For More Ideas Beyond Ecolab?
If Ecolab's mix of earnings quality and guided sales momentum has your attention, it can help to line it up against other opportunities that share some of those traits. The Simply Wall St Screener lets you filter for different profiles so you can build a watchlist that fits your own risk, income and balance sheet preferences.
- If you care most about resilience, start with companies that the screener ranks as 30 resilient stocks with low risk scores and see which ones match your comfort level.
- For investors who want a focus on balance sheet strength and fundamental support, look through the list of solid balance sheet and fundamentals (25 results) to spot potential candidates for deeper research.
- If you are hunting for future leaders before they are widely followed, scan the 18 high quality undiscovered gems and see which stories you want to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com