


1st Source (SRCE) Earnings And Dividend Hike Put Its Valuation Back In Focus
Earnings jump, cleaner credit, higher dividend
1st Source (SRCE) just packed three key updates into one day: higher net interest income, increased net income, and lower net charge offs, along with a higher quarterly cash dividend.
Recent performance has backed up the stronger earnings story. 1st Source’s share price is up 40.07% year to date, and its 1 year total shareholder return of 50.68% together with a 3 year total shareholder return of 98.43% suggests momentum has been building rather than fading.
Scan beyond 1st Source and line up other banks with resilient earnings, cleaner credit, and rising payouts using our curated list of 5 dividend fortresses
1st Source now carries a richer share price and a bigger dividend, backed by higher earnings and cleaner credit. Is the latest climb mainly a reset in sentiment, or a measured response to what the bank is actually delivering?
Price-to-Earnings of 12x: Is it justified?
Valuation is no longer an afterthought for 1st Source with the stock at $87.49 and trading on a P/E of 12x. This sits above several benchmarks and suggests investors are paying up compared with both peers and a fair value reference.
The P/E ratio compares what you pay per share to the company’s earnings per share. For a bank such as 1st Source, it signals how the market is weighing current profitability alongside expectations for future earnings, credit quality and capital efficiency.
On these numbers, the market is assigning a richer tag than several reference points. The shares are on 12x earnings, while the estimated fair P/E is 10.6x and the peer average sits closer to 10x. That gap indicates investors are accepting a premium relative to what the SWS fair ratio suggests the multiple could move toward if sentiment cools or earnings trends normalise.
The comparison against the broader US Banks group is similar. The industry average P/E is 11.4x, which still sits below 1st Source at 12x, so the stock is priced more expensively than the sector despite earnings growth that did not outrun the banks industry in the most recent year.
Explore the SWS fair ratio for 1st Source.
Result: Price-to-Earnings of 12x (OVERVALUED)
Still, a richer P/E can come under pressure if 1st Source sees slower revenue or net income growth, or if credit costs start to rise again.
Find out about the key risks to this 1st Source narrative.
Another view on 1st Source’s value
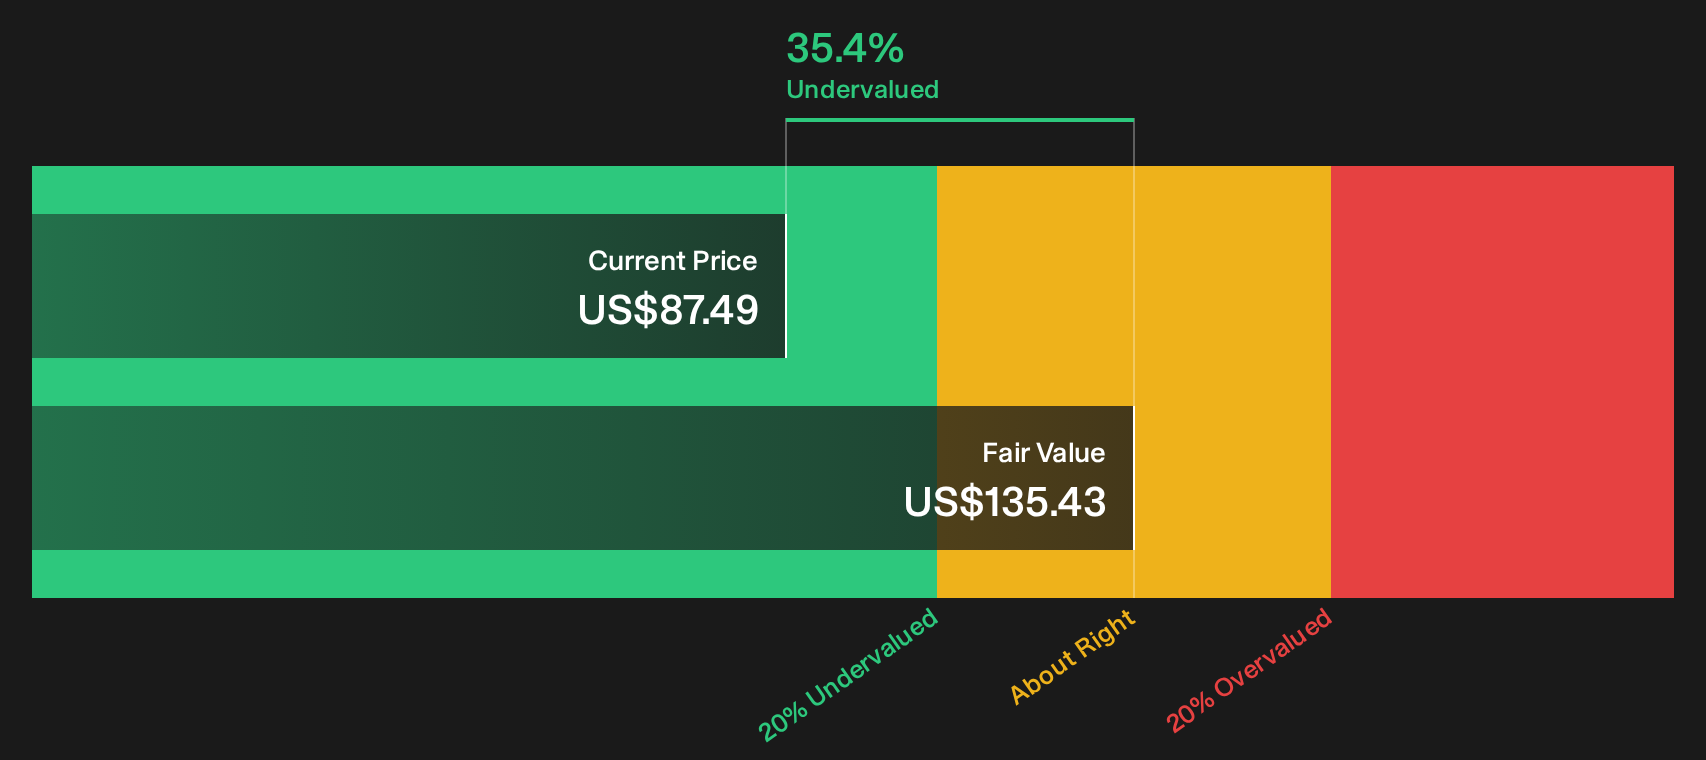
The P/E workup paints 1st Source as expensive, yet the SWS DCF model points in the opposite direction. On that cash flow view, SRCE at $87.49 trades about 35.4% below an estimated value of $135.43. This frames the current price as potentially discounted rather than stretched. Which lens should carry more weight for you?
For a closer look at how that cash flow estimate is built and what might need to go right for it to hold, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 1st Source for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on 1st Source have you intrigued, move fast and pressure test the story against the underlying data yourself. To gauge what optimism in the market is latching onto, take a closer look at 3 key rewards.
Looking for more investment ideas beyond 1st Source?
Do not park your attention on 1st Source alone when the wider market holds other potential opportunities that might better fit your goals and risk comfort.
- Target value first and let quality follow by reviewing a curated set of 29 high quality undervalued stocks that combine strong fundamentals with pricing that has not fully caught up.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses built on sturdier financial footing rather than stretched balance sheets.
- Spot potential early movers before the crowd by working through 18 high quality undiscovered gems that meet strict fundamental filters yet still fly under broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com