


What Vienna Insurance Group Holders Bought Into
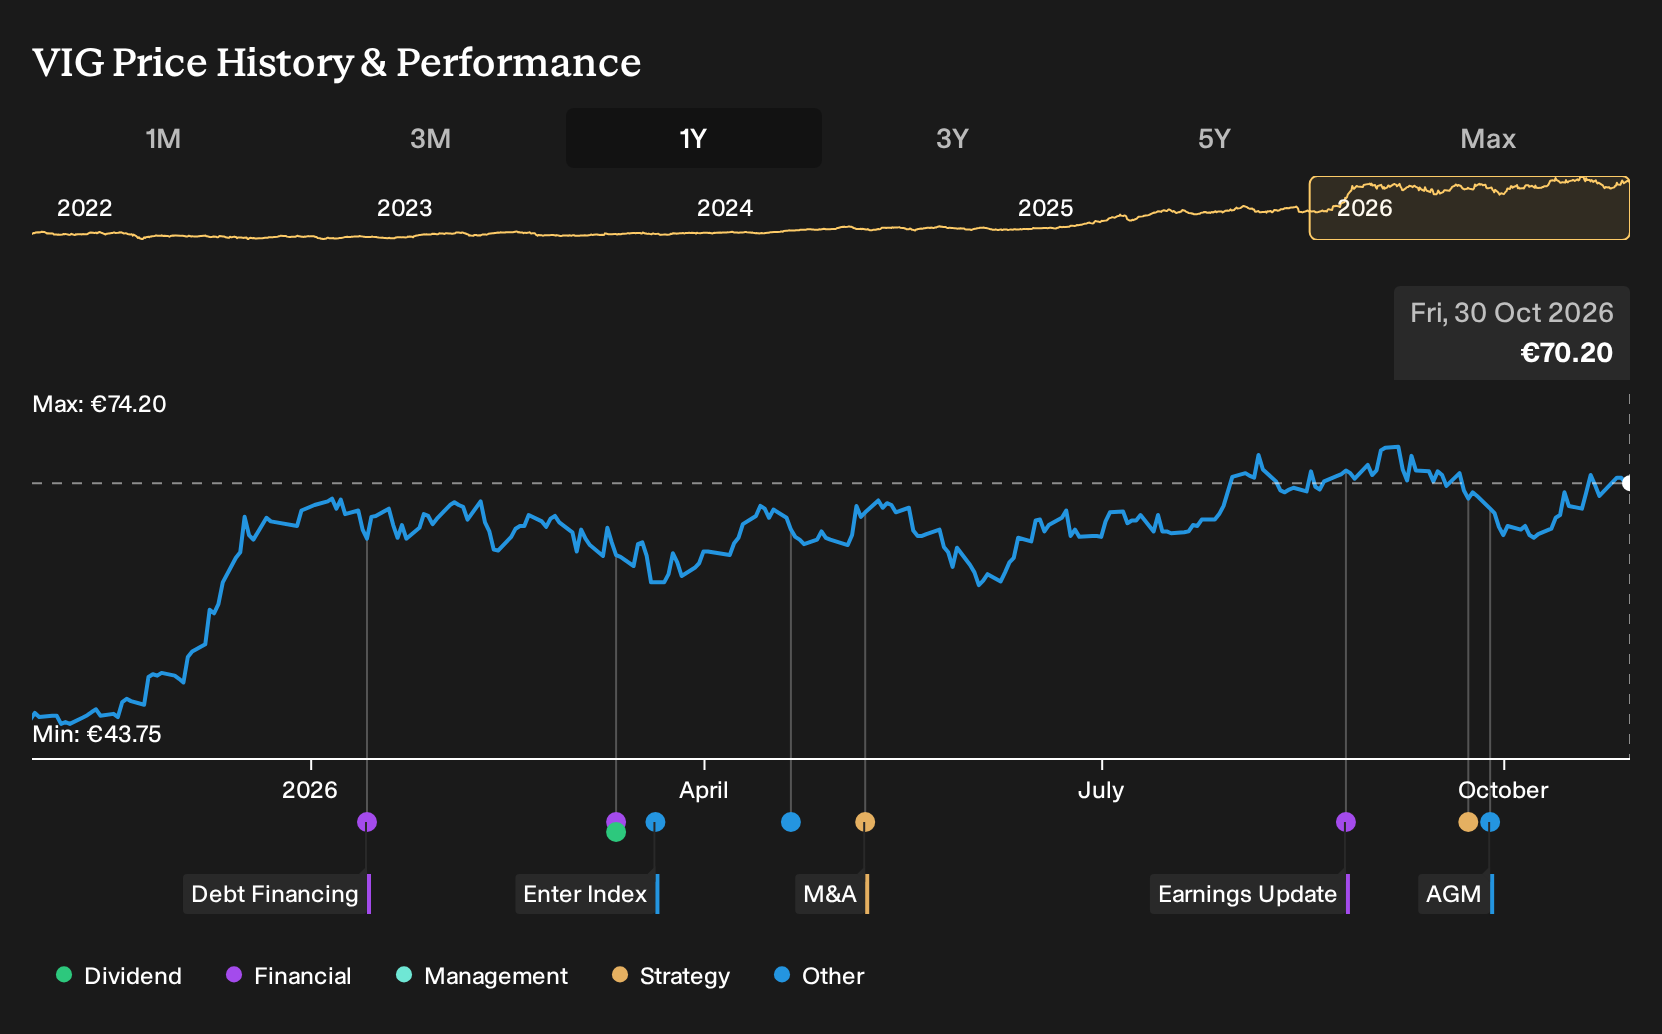
Investors who held Vienna Insurance Group over the past year are up 62.1%, including dividends. If you were weighing a buy on 30 October 2025, you saw a split screen. One side argued that CEE insurance demand, digital projects and a 278% solvency ratio could support long expansion. The other side stressed climate losses, bond-heavy investments and lagging IT. Faced with that record, what would have made you press “buy” or decide to pass?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Vienna Insurance Group has already moved. See which of 199 high quality undervalued stocks still trade below our estimates.
The Two Vienna Insurance Group Stories Investors Had To Weigh
The shares cost €44.95 at the start of the period, and Vienna Insurance Group sat between two very different but plausible stories about its future.
On the upbeat side, the bullish narrative set fair value at €49.5 and leaned on Central and Eastern European growth, along with a 278% solvency ratio that supporters thought could support acquisitions and a long expansion.
The bearish view anchored on a fair value of €24.5 and focused on escalating climate events, where higher weather related claims and combined ratios were expected to pressure underwriting profit and margins over time.
What The Results Changed For Vienna Insurance Group
The biggest new fact was Vienna Insurance Group closing its largest deal, the NÜRNBERGER acquisition, which supported the optimistic story about using a strong solvency position to expand. Measured results reinforced that view, with total revenue and net income both higher in H1 2026 than in H1 2025 and net margin edging up from 6.0% to 6.4%. Overall, the evidence leaned toward the upbeat case but did not settle climate and digital concerns.
The lesson to carry to other insurers is simple. When a thesis rests on capital strength and acquisition firepower, track actual deal execution and compare reported margins and earnings trends to the original expansion claims.
What Today's Vienna Insurance Group Price Already Assumes
Vienna Insurance Group now trades at €70.2, while the selected Narrative’s Fair Value sits below that level based on its own assumptions rather than any objective truth. The Narrative argues that the current quote already reflects Vienna Insurance Group’s capital strength, profitability and delivery against stated goals.
The question for you is what must keep going right for today’s price to hold, with the Narrative pointing to a buyer needing confidence that capital strength, reserve choices and higher risk markets will still translate into durable profit growth.
"Despite Vienna Insurance Group continuing to grow insurance service revenue and profit before tax at group level, using strong periods in key markets like Poland to reinforce reserves rather than to widen underwriting margins suggests that management may need to keep sacrificing short term profitability to maintain balance sheet strength, which may cap improvements in the combined ratio and earnings per share."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 44% below our estimate - uses a multi brand electric line-up and new plants to deepen overseas sales channels.
- Company 2 - 45% below our estimate - expands forensic software contracts by upselling existing users into higher tier subscriptions.
- Company 3 - 35% below our estimate - supplies AI chips and software that data centres rely on for high yield workloads.
Three companies from the same screener. Open every one of the 203 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com