


Construction Partners (ROAD) After Strong Q3 And Higher Outlook, Does Valuation Still Work
Construction Partners (ROAD) caught investor attention after reporting strong third quarter results and raising its fiscal year outlook, while addressing wet weather, higher energy costs, and the use of its cost pass-through model.
At a share price of US$89.88, Construction Partners has seen short term swings, with a 7 day share price return of 8.24% after the quarterly update. The year to date share price return is down 19.86% and the 1 year total shareholder return has fallen 21.40%, set against a much stronger 3 year total shareholder return of 126.06%, which points to longer running momentum even as sentiment has cooled more recently.
Scan other construction and infrastructure players showing similar momentum and backlog support through our hand picked 39 power grid technology and infrastructure stocks. These tap into long term road, energy, and transport spending themes.
For Construction Partners, a strong quarter and a sharp 7 day rebound sit beside a weaker year, which raises a simple question. Is the recent jump catching up to business fundamentals or just sentiment snapping back before the valuation check.
Most Popular Narrative: 35% Undervalued
Against the last close of $89.88, the most followed narrative on Construction Partners points to a fair value of about $138. This gap turns the recent bounce into a valuation question, not just a momentum story.
Ongoing vertical integration in liquid asphalt and terminals, including owning assets that now supply more than half of liquid asphalt consumption and expanding index-linked and hedged contracts that protect over 80% of revenue, is already visible in mid-teens adjusted EBITDA margins. This can further support net margins and cash conversion as more volume moves through owned infrastructure.
See why 11 investors see Construction Partners as 35% undervalued.
Result: Fair Value of $138.14 (UNDERVALUED)
Still, the Construction Partners story can change quickly if public infrastructure budgets tighten, or if recent acquisitions underperform and weigh on margins and cash generation.
Find out about the key risks to this Construction Partners narrative.
Another View: What Multiples Say About Construction Partners
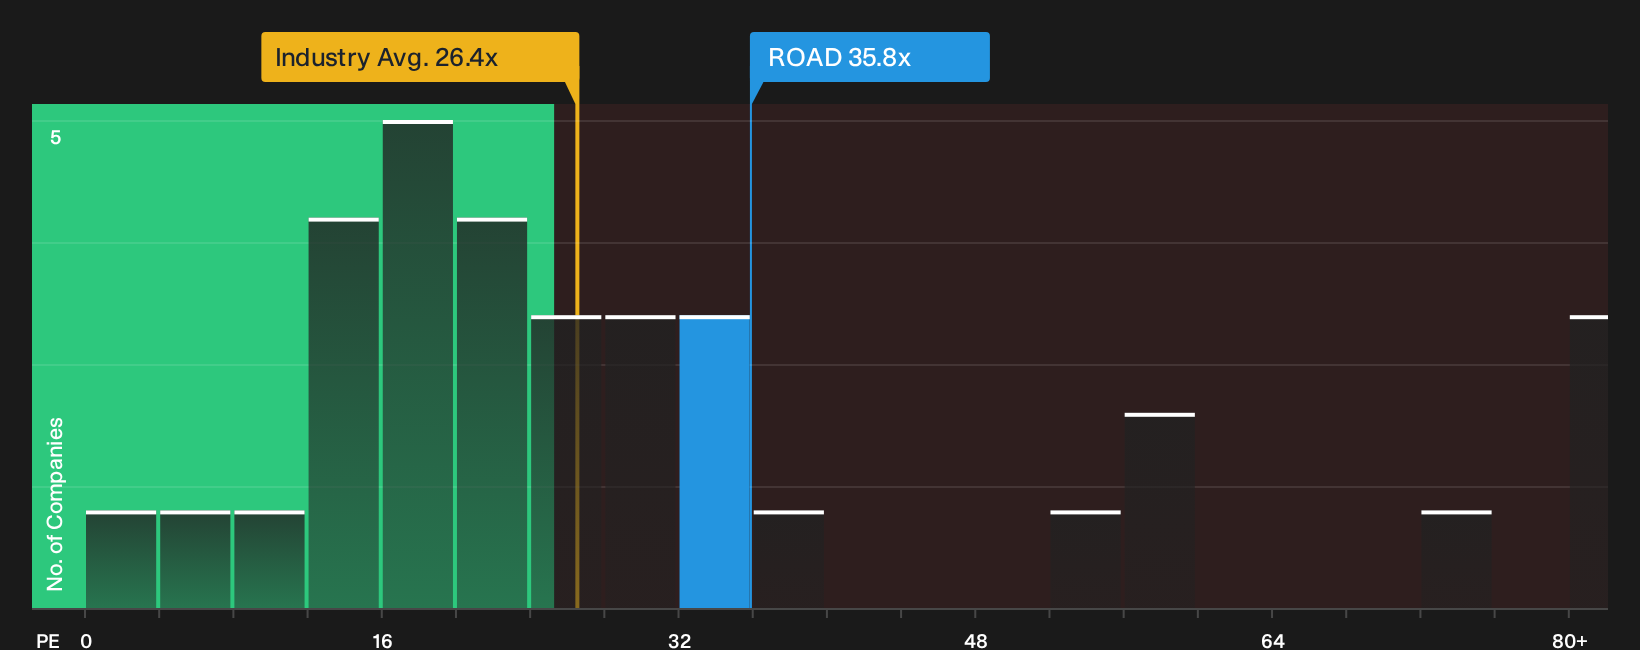
On the flip side of that fair value of about $138, Construction Partners currently trades on a P/E of 35.8x. That is higher than the US Construction industry at 27.9x, peers at 27.4x, and even the 33.1x fair ratio that the regression work suggests the market could move toward. For investors, the question is whether paying this kind of premium feels like a margin of safety or a valuation stretch.
To see how this richer P/E stacks up against the broader sector and where the fair ratio sits, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Construction Partners story so far. If you want to move fast and anchor your own view in the data, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Construction Partners?
Construction Partners gives a useful starting point, but your portfolio benefits when you line up several quality candidates and compare them side by side.
Use the Simply Wall Street Screener to spot fresh angles before everyone else pays attention, or risk missing opportunities that match your own risk and return preferences.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through our 29 high quality undervalued stocks.
- Strengthen the defensive side of your holdings by filtering for resilient businesses using the 30 resilient stocks with low risk scores.
- Unearth underfollowed opportunities that still show solid financial underpinnings with the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com