


QCR Holdings (QCRH) Record EPS Puts Its Undervalued Narrative Back In Focus
QCR Holdings (QCRH) just posted record earnings per share for the third quarter of 2026, supported by higher-margin loan originations, tighter balance sheet management, and net charge-offs falling to the lowest level reported this year.
The share price has slipped over the past week and quarter, with 7 day and 90 day share price returns both slightly negative. The stock still shows a year to date share price return of 23.25% and a 1 year total shareholder return of 36.71%. This may hint that investors are reassessing near term risks after a multi year period in which the company delivered a 3 year total shareholder return of 100.88%.
Compare QCR Holdings' record-quarter profile with a hand picked 30 resilient stocks with low risk scores that also focus on resilient balance sheets and tighter risk management.
Bulls point to record earnings per share and low net charge-offs at QCR Holdings, while bears focus on the recent share price slip. Which side does the current valuation really support next?
Most Popular Narrative: 8% Undervalued
The most followed narrative on QCR Holdings points to a fair value of $110.50 against the latest close of $101.24. This frames the current pullback as a discount that hinges on execution of its fee income and cost discipline plans.
The LIHTC lending and capital markets platform, supported by relationships with 18 of the top 20 affordable housing developers and guidance for US$60 million to US$70 million of capital markets revenue over the next four quarters, points to further fee based noninterest income that could support revenue growth and earnings power.
See why 2 investors see QCR Holdings as 8% undervalued.
Result: Fair Value of $110.50 (UNDERVALUED)
Still, QCR Holdings relies heavily on LIHTC related fees and is only halfway through its core system overhaul, so any missteps there could quickly weaken this 8% undervaluation story.
Find out about the key risks to this QCR Holdings narrative.
Another View: What QCR Holdings Looks Like On Earnings
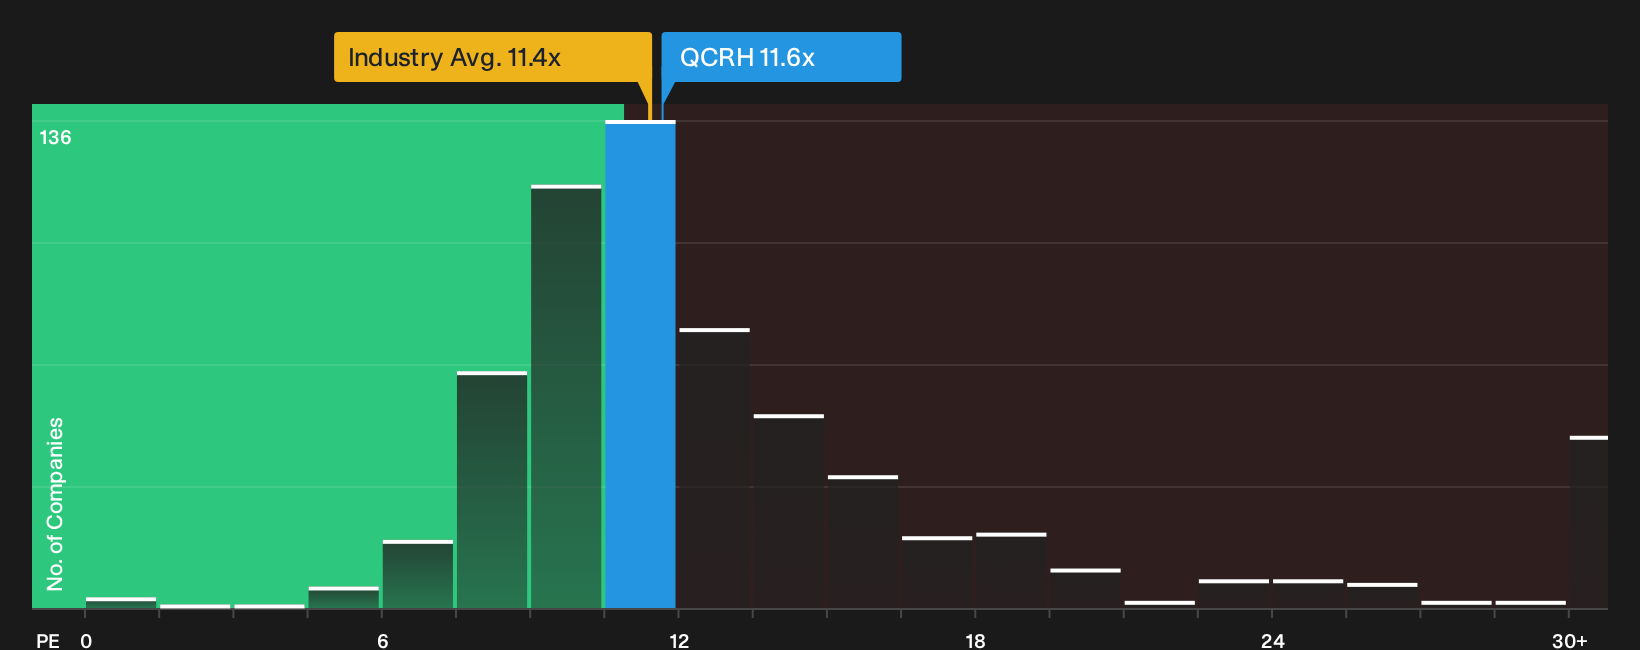
Flip the lens and the picture changes. On a P/E basis, QCR Holdings trades at 11.6x, which is slightly higher than the US Banks industry at 11.4x, yet below peers on 15.7x and above its own fair ratio of 10.7x. That mix hints at both some valuation risk and a possible relative opportunity. Does that premium against the fair ratio outweigh the discount to peers in your view?
For a closer read on what the numbers imply, including where the ratio could migrate over time, start with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the bullish rewards story and the recent price wobble around QCR Holdings? Move quickly, review the details, and weigh the 3 key rewards.
Looking for more investment ideas beyond QCR Holdings?
If QCR Holdings has caught your attention, do not stop there. Use fresh ideas from the screener to pressure test your next move and widen your opportunity set.
- Target steady compounding potential by checking companies built on reliable cash flows and healthy finances in the list of solid balance sheet and fundamentals (25 results).
- Chase pricing that could be more attractive relative to quality by reviewing the 18 high quality undiscovered gems before the crowd notices them.
- Boost your income watchlist by scanning companies offering stronger yields in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com