


Is Higher Insurance Costs Altering The Investment Case For Landstar System (LSTR)?
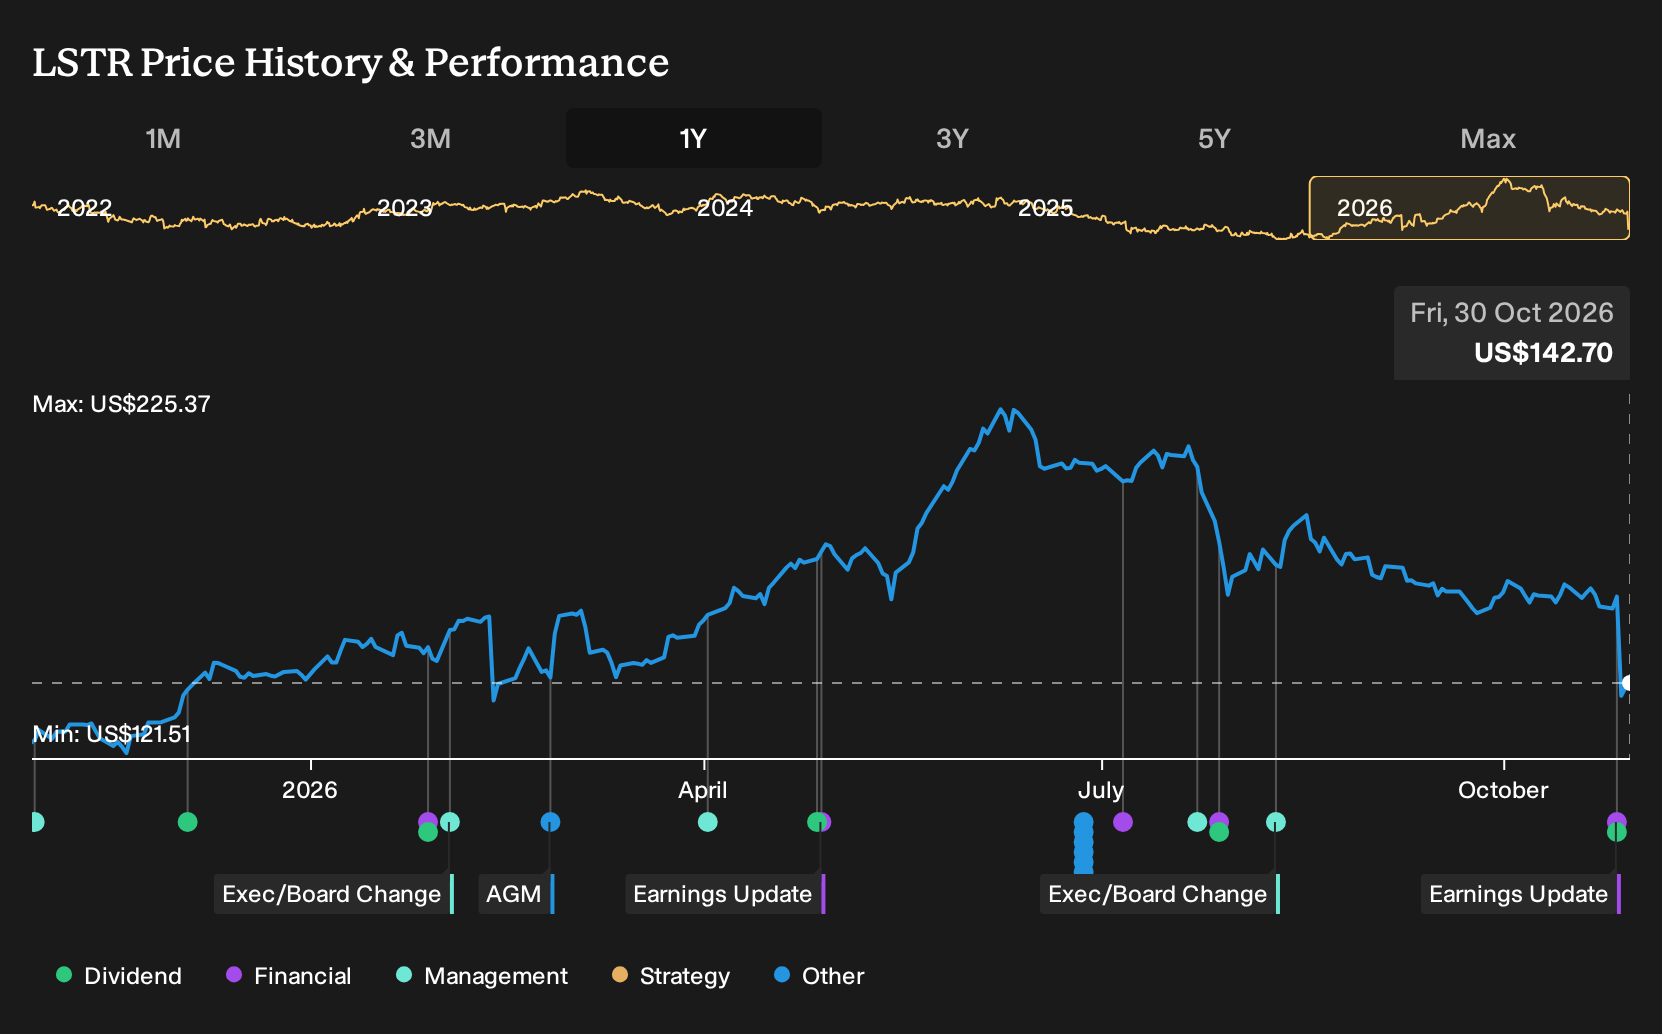
- Landstar System reported third quarter 2026 sales of US$1,490.31 million and net income of US$48.04 million. Its board declared a US$0.44 per share dividend that was paid on December 8, 2026 to holders of record on November 17.
- Strong freight demand and higher truck revenue occurred alongside heavy insurance and claims expenses, which compressed earnings quality and raised questions about the durability of Landstar System's asset light model under tighter safety and regulatory scrutiny.
- This article examines how Landstar System's investment narrative is affected by rising insurance and claims costs despite solid freight demand.
Landstar System Investment Narrative Recap
To own Landstar System, you need to believe its asset light freight model can keep turning strong demand in areas like heavy haul into durable earnings, even with tighter safety rules and higher legal scrutiny. The latest quarter delivered higher sales and net income, but insurance and claims expense remains the swing factor for near term profitability.
The most important short term catalyst is whether management can convert AI spending and stricter carrier vetting into better insurance and claims outcomes while preserving freight volumes. The biggest risk is that higher accident severity, fraud controls and reserve adjustments keep insurance costs elevated enough that margin progress stalls.
The recent quarterly earnings release is the key update to focus on. Landstar System posted third quarter 2026 sales of US$1,490.31 million and net income of US$48.04 million, with higher basic EPS from continuing operations versus a year ago. Heavy haul demand, more trucks in the network and firmer freight pricing supported top line performance.
Those same results also highlighted how central insurance remains to the story. Management called out accident settlements, reserve adjustments and broader claims costs as material pressures on earnings quality. Your view on this report likely comes down to whether strong freight fundamentals and AI driven efficiency projects can offset that insurance drag over the next few quarters.
What The Current Forecasts Assume For Landstar System
Landstar System's narrative projects US$6.7b revenue and US$296.5 million earnings by 2029. This is built on analyst assumptions of 10.0% yearly revenue growth and an earnings increase of about US$164.8 million from current earnings of US$131.7 million.
Uncover why Landstar System's fair value indicates a 27% potential upside to its current price, an opportunity that could narrow quickly.
Exploring Other Perspectives
One alternate view on Landstar System zooms in on tighter safety rules as the real swing factor. The most pessimistic analysts already expected revenue of about US$6.6b and earnings of roughly US$289.1 million by 2029 before this dividend and Q3 update, yet still saw lower fair value. That gap shows how sharply opinions can differ, so consider using this quarter to compare several narratives and test which assumptions you find most reasonable.
Explore another Landstar System fair value estimate, including one that suggests it could be worth just $181.12!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Landstar System research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Landstar System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Landstar System's overall financial health at a glance.
Looking For More Investment Ideas Beyond Landstar System?
If the Landstar System story has you thinking about position sizing and portfolio balance, it can help to line it up against other stocks with different income profiles, balance sheet strength and perceived risk levels. Use the Simply Wall St Screener to pressure test your freight exposure and surface fresh ideas that fit the way you like to invest.
- If income matters to you, scan for companies offering sturdier yields and payout histories through our 5 dividend fortresses.
- For investors who want quality without overpaying, filter for stronger fundamentals and pricing support using the 29 high quality undervalued stocks.
- If capital preservation is front of mind, narrow your search to businesses with stronger financial resilience via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com