


Will Raised AFFO Guidance Change W. P. Carey (WPC) Narrative
- W. P. Carey reported third quarter 2026 revenue of US$468.3 million and net income of US$140.95 million, and lifted full year 2026 AFFO guidance to US$5.23 to US$5.29 per share, alongside a 4.4% dividend increase.
- Occupancy of 98.6%, 2.6% same-store contractual rent growth, and roughly US$1.6 billion of investments at a 7.5% initial cash cap rate highlight how W. P. Carey is leaning on high-quality net lease assets to support earnings capacity.
- This article examines how W. P. Carey’s investment narrative is affected by raised AFFO guidance following a 6.4% quarterly AFFO increase.
Scan how W. P. Carey’s raised AFFO outlook compares with other income-focused real estate plays by reviewing our curated list of 5 dividend fortresses in similar cash flow driven sectors.
W. P. Carey Investment Narrative Recap
To own W. P. Carey, you need to be comfortable with a simple idea. The REIT is built around long term net leases that aim to turn high occupancy, CPI linked rent bumps and steady acquisitions into relatively predictable AFFO and dividends. The raised 2026 AFFO guidance and 6.4% quarterly AFFO uplift support that cash flow centric story in the near term.
The key short term swing factor is execution on the US$1.8b to US$2.1b investment pipeline at returns that justify the funding mix. The biggest current risk sits around tenant concentration and credit quality, because a cluster of tenant issues on long leases could pressure occupancy, rent collections and eventually AFFO, even with today’s healthy 98.6% level.
The most relevant update here is the third quarter 2026 earnings report, which showed revenue of US$468.3 million, net income of US$140.95 million and AFFO of US$1.33 per share. That print underpins the raised full year AFFO guidance of US$5.23 to US$5.29 per share and the 4.4% dividend increase, both tied directly to operating cash generation.
Those figures sit alongside roughly US$1.6b of year to date investments at an initial 7.5% cash cap rate and portfolio occupancy of 98.6%, with 2.6% same store contractual rent growth. For you as a shareholder, the execution question is whether W. P. Carey can keep sourcing similar deals and managing tenant credit, while carrying debt that is not fully covered by operating cash flow so that dividend ambitions remain supported by actual earnings power.
Analysts currently assume W. P. Carey can reach about US$2.2b in revenue and US$802.8 million in earnings by 2029, based on consensus models that build in roughly 7.1% yearly revenue growth and an earnings increase of about US$151.8 million from current earnings of US$651.0 million.
Uncover how W. P. Carey's fair value indicates a 19% potential upside to its current price before a discount like that may not last much longer.
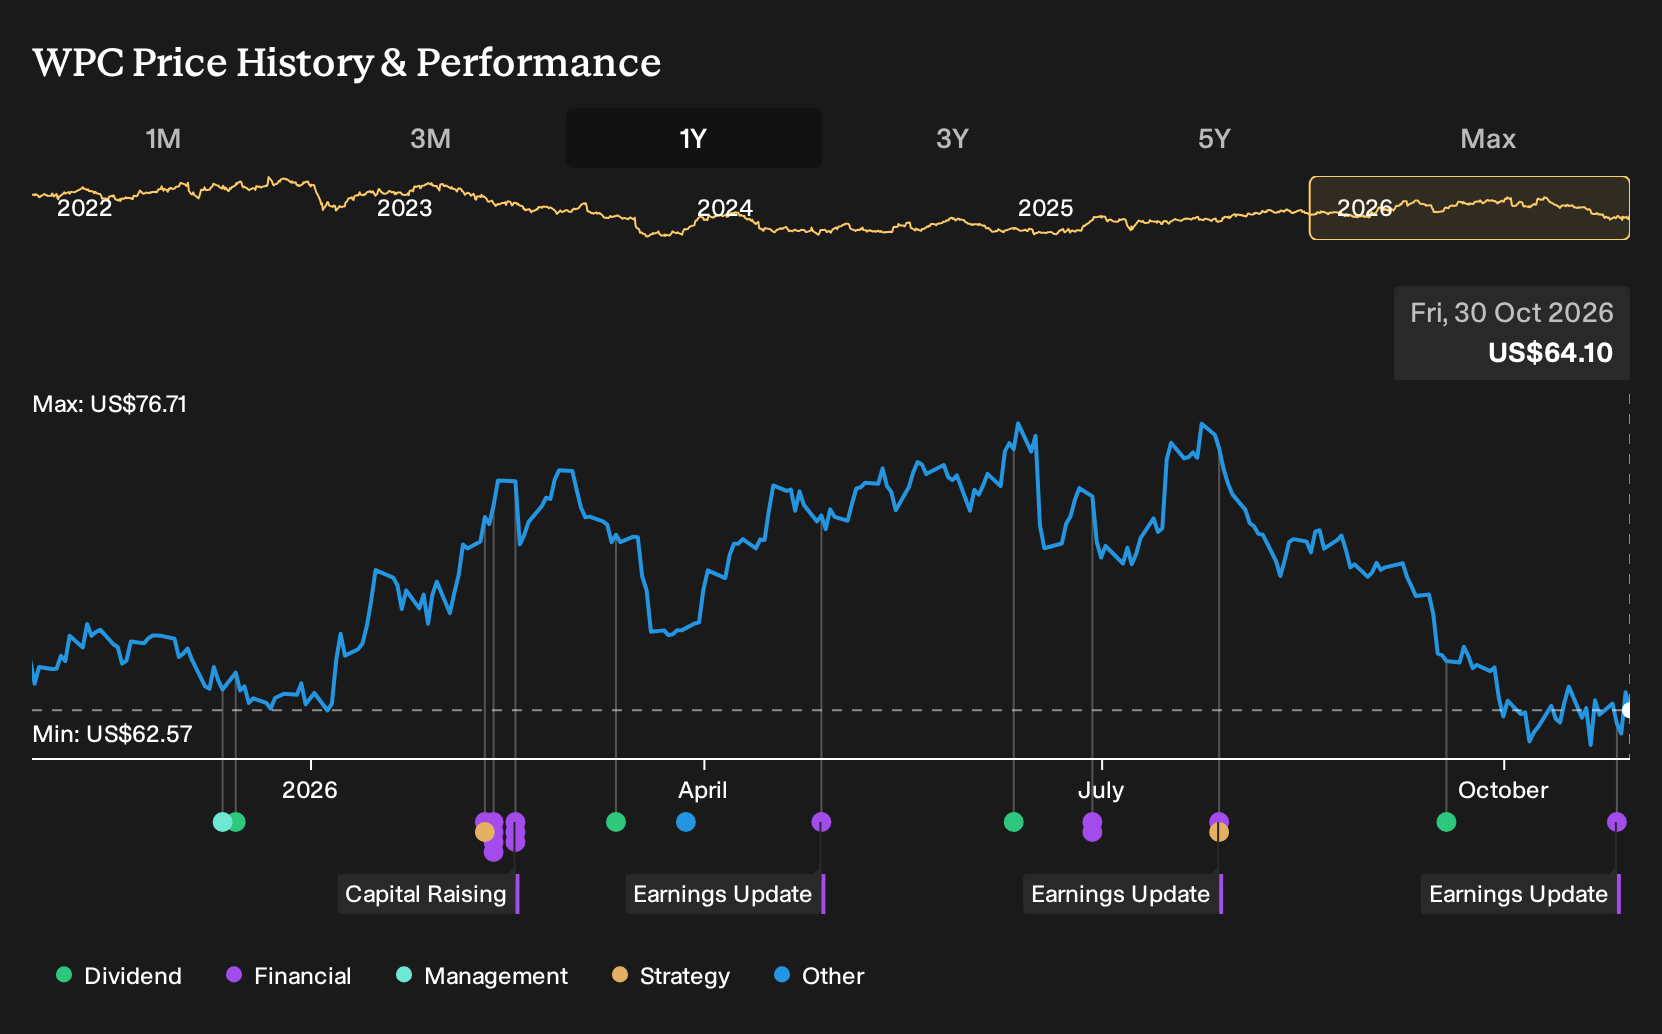
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$76.5 to US$167.9 per share, showing how far opinions on W. P. Carey can stretch. Some members focus on AFFO guidance, CPI linked leases and the current investment pipeline; others flag tenant concentration and funding costs. Treat these as starting points and compare several viewpoints before forming your own stance.
Explore 2 other W. P. Carey fair value estimates, including one that suggests there could be as much as 162% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your W. P. Carey research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for W. P. Carey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W. P. Carey's overall financial health at a glance.
Looking for more investment ideas beyond W. P. Carey?
If W. P. Carey has sharpened your focus on income and quality, it can be useful to line it up against a wider watchlist built around clear fundamentals. The Simply Wall St Screener lets you filter for different profiles so you can keep W. P. Carey in context rather than in isolation.
- For cash flow resilience and balance sheet strength, start with a curated list of solid balance sheet and fundamentals (25 results). This can help you compare financial robustness across potential holdings.
- If you want a margin of safety built into price, use the screener that highlights 29 high quality undervalued stocks based on fundamentals and current market expectations.
- For investors who prefer under-the-radar opportunities, scan a focused pool of 18 high quality undiscovered gems that pair quality metrics with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com