


What Is Drawing Fresh Attention To Cirrus Aircraft (SEHK:2507)?
Cirrus Aircraft (SEHK:2507) has broken ground on an HK$8 million Engine Run-Up Center, a 15,000-square-foot facility designed to provide safer, more controlled testing for SR Series, Vision Jet, and TRAC10 engines.
For investors watching the tape, Cirrus Aircraft’s latest HK$8 million investment arrives after a tougher stretch for the shares, with the 30 day share price return down 13.8% and the year to date share price return down 39.3%, while the 1 year total shareholder return has declined 28.1%.
Spot fresh aviation plays by scanning the 602 high quality undiscovered gems that, like Cirrus Aircraft, are investing heavily in capacity and capability upgrades behind the scenes.The share price has already absorbed a rough reset, yet Cirrus Aircraft is still spending heavily on its engine testing footprint. Is most of the rerating already in the rear-view mirror, or is the upside still ahead?
Most Popular Narrative: 33% Undervalued
Cirrus Aircraft's most followed valuation story pegs fair value at HK$55.14 per share, compared with the last close at HK$36.86. That gap puts a spotlight on whether the latest HK$8 million spend is simply business as usual capacity build, or part of a broader push that the market has not fully reflected in the current share price.
Cirrus Aircraft represents a high-quality niche aerospace platform with:
• Clear leadership in personal aviation
• Strong growth trajectory
• Attractive valuation relative to peers
While macro sensitivity remains a concern, Cirrus’ brand, innovation pipeline, and ecosystem strategy position it well for long-term value creation.
See why 1 investors see Cirrus Aircraft as 33% undervalued.
Result: Fair Value of HK$55.14 (UNDERVALUED)
Still, the Cirrus Aircraft story can be knocked off course if macro weakness hits big-ticket aircraft orders or if China ownership risk keeps a lid on valuation.
Find out about the key risks to this Cirrus Aircraft narrative.
Another View: Cirrus Aircraft Through The P/E Lens
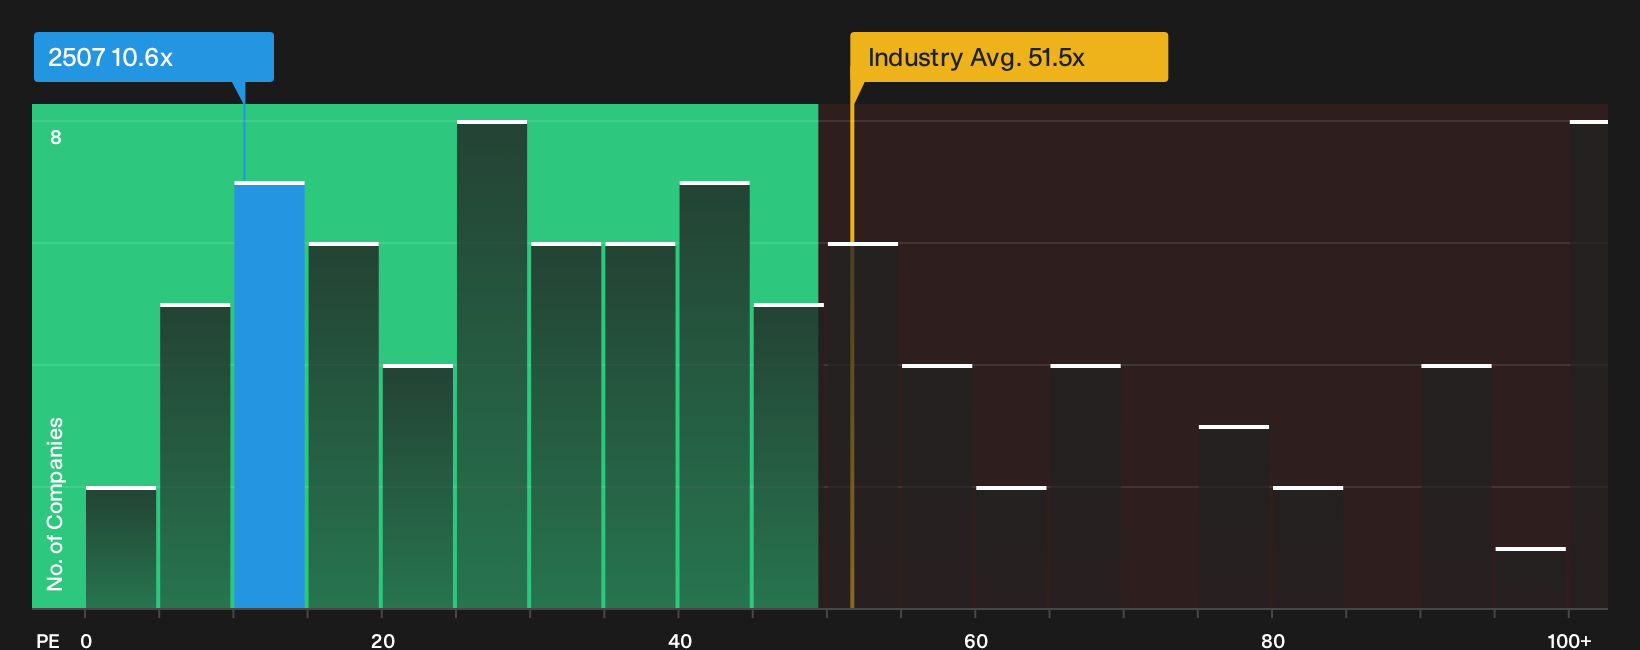
Fair value arguments for Cirrus Aircraft based on cash flows and narratives meet a more cautious picture when the P/E ratio is brought in. The shares trade on 10.6x earnings, above the fair ratio of 9.5x and above peer averages at 9.6x, even though the broader Asian Aerospace & Defense group sits far higher at 53.8x. For anyone watching downside risk as closely as upside potential, that premium to closer peers raises a simple question: how much confidence do you really have in the earnings path that would justify paying above the fair ratio?
That is where a closer breakdown of the valuation inputs helps. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Cirrus Aircraft story leans optimistic, but the real edge comes from testing the numbers yourself and acting before sentiment shifts. To see what the current optimism is anchored to, review the 4 key rewards
Looking for more investment ideas beyond Cirrus Aircraft?
If you stop with Cirrus Aircraft, you risk missing other compelling setups that line up with your risk level, return goals, and time horizon.
- Target potential mispricing by scanning companies on the 199 high quality undervalued stocks that combine appealing valuations with solid underlying fundamentals.
- Prioritize resilience and sleep-better-at-night holdings by reviewing the 218 resilient stocks with low risk scores with lower risk scores and steadier profiles.
- Strengthen the quality of your watchlist by checking the list of solid balance sheet and fundamentals (203 results) so you focus on businesses with sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com