


QXO (QXO) Faces Earnings Doubts And A New Partnership, Is The Valuation Gap Still Compelling?
QXO stock moves on mixed signals
QXO (QXO) is back in focus as investors weigh two fresh signals: a widely discussed earnings outlook that points to a year-over-year profit decline and a new distribution partnership in the western U.S.
QXO now trades at US$11.04 after a 1-day share price return that declined 2.99%, even though the 7-day share price return gained 5.04%. Meanwhile, the 1-year total shareholder return fell 37.52% and the 5-year total shareholder return declined 71.32%, signaling pressure on longer term momentum despite short bursts of interest around earnings expectations and distribution deals.
Compare how QXO stacks up against other building and construction plays by scanning the list of solid balance sheet and fundamentals (25 results) that are holding up under closer scrutiny.
QXO carries upbeat revenue and partnership news on one side and a sharp share price slide over 1 year on the other. Does most of the rebound case still sit ahead of the current valuation?
Most Popular Narrative: 66% Undervalued
Against a last close of $11.04, the most followed narrative on QXO places fair value at about $32.53, which implies a steep valuation gap that hinges on aggressive scale-up and execution over the next several years.
QXO represents a disciplined M&A consolidation play in the $800B building products distribution market, led by Brad Jacobs, the most proven serial acquirer in modern industrial history (300x cumulative returns across four prior platforms, roughly 500 acquisitions). The company has built a $1B+ EBITDA run-rate in under 10 months by acquiring Beacon Roofing Supply ($11B) and Kodiak Building Partners ($2.25B). This has created the largest publicly traded building products distributor in North America.
See why 24 investors see QXO as 66% undervalued.
According to OOO97, the narrative rests on QXO using M&A and technology to reshape a large distribution market, with fair value built from detailed revenue, margin and earnings bridges out to 2031. The view uses a 10.6% discount rate and a 12.5% profit margin assumption to support the $32.53 figure, which is roughly triple the current share price.
The same thesis highlights both upside and risk. The upside comes from forecast revenue growth of 22.5% per year and earnings growth expectations of 66.74% per year, as well as management targets for margin improvement. The risk side points to the current net loss of $656.3m, a return on equity that is negative at 4.14%, and a capital structure that includes preferred stock and higher risk funding through external borrowing.
Forecasts also involve uncertainty. Analysts see QXO's revenue growing faster than both 20% per year and the wider US market at 13.3% per year, and expect the business to become profitable within 3 years. At the same time, the consensus on target prices is not described as tight, and QXO's 1-year return has fallen 37.52%, which trails both the broader US market and the Trade Distributors industry.
For investors weighing this story, the gap between the $11.04 share price and the narrative fair value of $32.53 reflects a belief that the firm will execute on acquisitions, margin expansion and cash flow improvement while managing dilution and debt. Any shortfall on those ingredients could challenge that fair value, while strong progress on them would support the more optimistic case.
Result: Fair Value of $32.53 (UNDERVALUED)
Still, the story can break if QXO struggles to reach profitability from its current US$656.3m loss, or if its complex funding structure strains common equity.
Find out about the key risks to this QXO narrative.
Another View: QXO on sales-based valuation
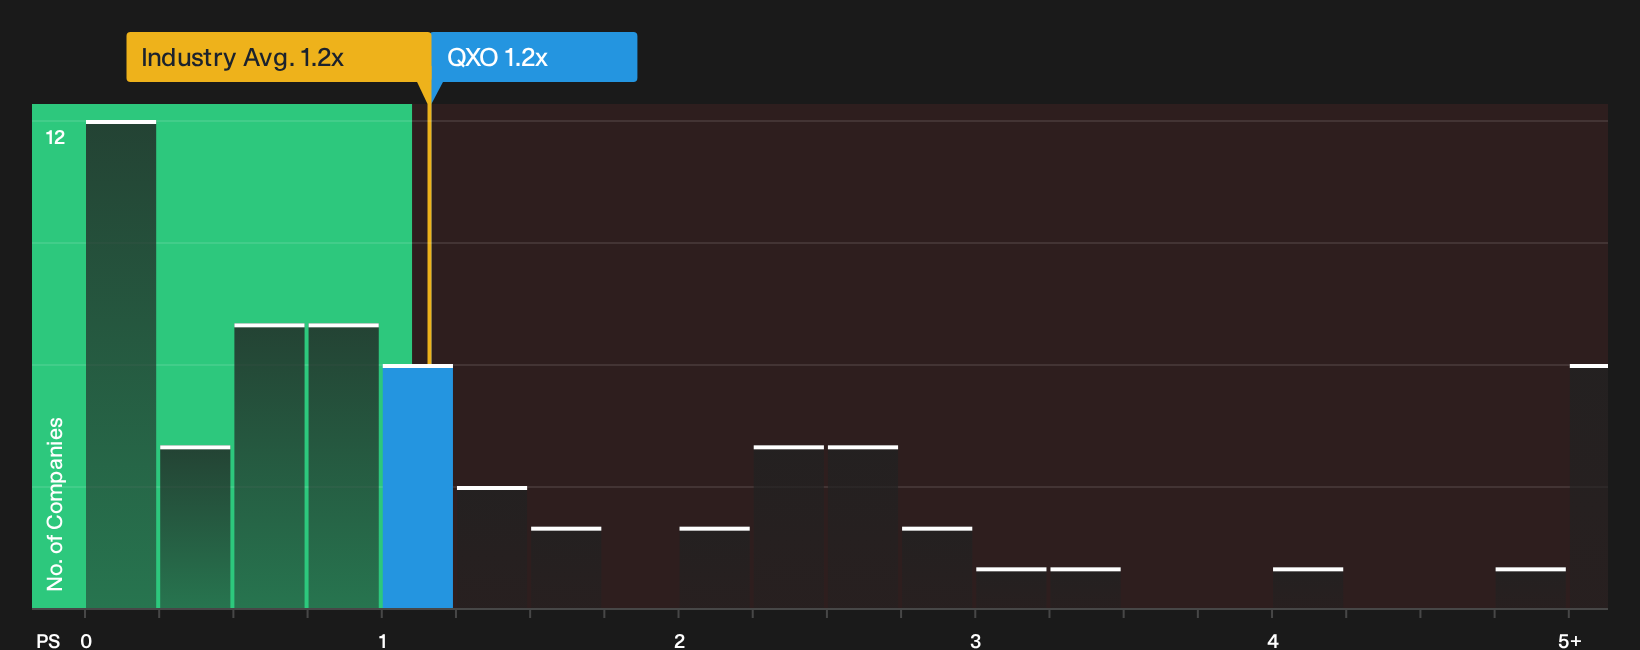
The story looks very different once the lens shifts from narrative fair value to what the market pays for each dollar of QXO's revenue. On a P/S of 1.2x, the stock trades in line with the US Trade Distributors average of 1.2x, yet well below peers at 2.9x and a fair ratio of 4.1x.
That gap suggests investors either see real risk in QXO's execution or have not fully priced in its revenue profile. This leaves readers asking whether this discount is sensible caution or a mispriced opportunity.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these can feel messy, which is exactly why it helps to review the full picture yourself and move before sentiment shifts again. To weigh both side by side, check the 2 key rewards and 1 important warning sign.
Looking for more QXO investment ideas?
If QXO has your attention, do not stop here. Broaden your watchlist with fresh ideas that could better fit your risk, income, and return goals.
- Chase potential mispricing by scanning the 29 high quality undervalued stocks that combine strong fundamentals with a market price that still looks cautious.
- Strengthen portfolio resilience by checking the 30 resilient stocks with low risk scores that pair steadier business profiles with lower overall risk scores.
- Spot early opportunities by reviewing the 18 high quality undiscovered gems that have quality metrics but limited attention from the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com