


Caught Out By CleanSpark's 57% Fall? What Investors Missed
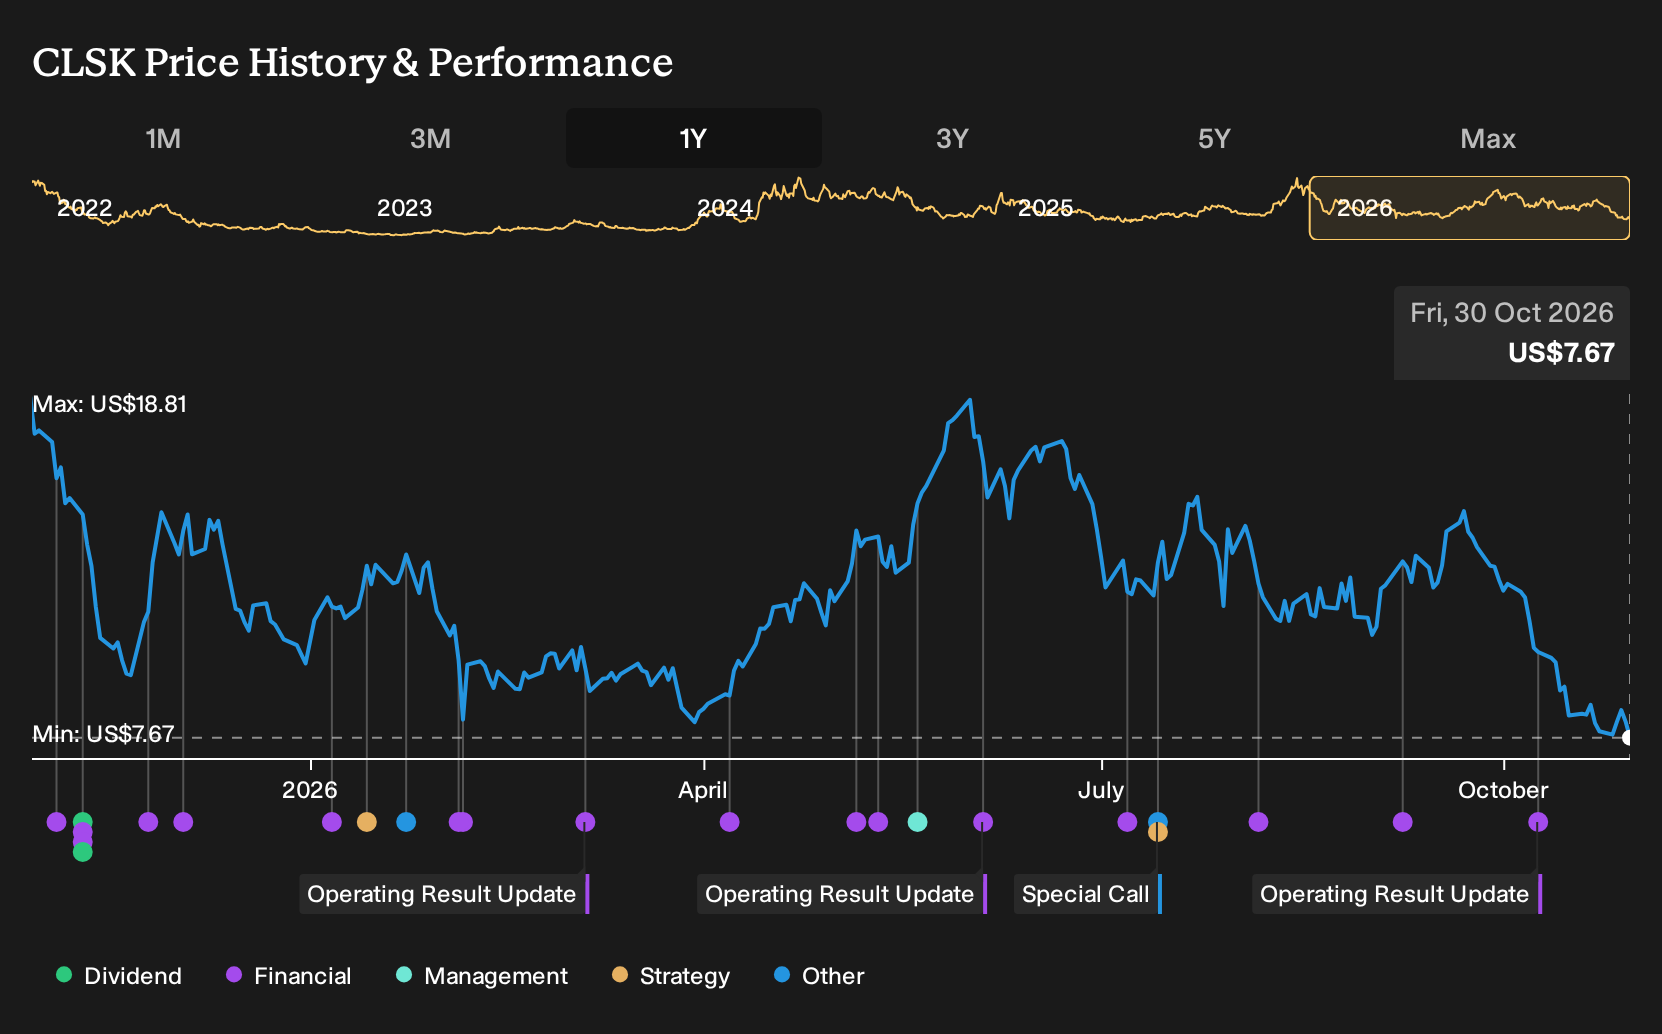
CleanSpark has just signed a 20‑year, US$6.6b triple‑net lease on its Sandersville AI data center campus, a headline that would catch any holder’s eye. Holding CleanSpark over the past year would have meant a 56.9% loss, including dividends. If you had put money into the stock back on 30 October 2025, how much of that experience now hinges on whether this AI and data center pivot can genuinely replace stressed Bitcoin economics?
CleanSpark is not the only name tied to this theme. Zero in on 18 cryptocurrency and blockchain stocks and compare how each one is priced.
The Argument CleanSpark Investors Were Really Weighing
The shares cost US$17.69 at the start of the period, and you were effectively choosing which CleanSpark story to believe.
On the upbeat side, analysts published a Fair Value of US$19.81, the rough “should be” price if their Bitcoin and efficiency assumptions played out, built on revenue growing 32.5% a year and margins settling at 21.7%.
The more cautious camp put Fair Value at US$15, tied to revenue growth of 18.1%, shrinking margins to 11.1%, and a much higher 42.2x future P/E assumption that made execution risk feel heavier.
What The Facts Did To The CleanSpark Thesis
The 20 year, US$6.6b triple net Sandersville lease with a high grade tenant supported the bullish shift toward AI infrastructure. At the same time, Q3 2026 data showed pressure on the old story. Revenue went from US$198.6m to US$138.0m and a prior profit of US$251.8m turned into a US$239.8m loss, so profitability claims stayed unproven. Overall, the evidence cut both ways.
The single hinge here was whether CleanSpark could turn Bitcoin driven cash flow into durable contracted income. For any similar pivot story, track the gap between long dated contracts signed and the trend in net margin after those deals start showing up in reported results.
What CleanSpark’s Drop Now Asks You To Believe
CleanSpark trades at US$7.67 after a 56.9% loss over the past year. The selected Narrative’s Fair Value sits above the current price and leans on the idea that long duration Sandersville lease income and Bitcoin mining cash flow can work together, rather than pull the business apart.
For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that policy support, energy access and treasury choices can keep funding growth without eroding existing holders through ongoing dilution.
"Operational efficiency and innovative treasury strategies drive higher margins and stable cash flow, reducing reliance on outside funding and insulating against energy market volatility."
One Narrative disagrees with today's price. → See where this Narrative says CleanSpark should trade
Where CleanSpark’s Theme Extends
CleanSpark’s AI data center push raises a follow up question. Who keeps all that compute connected, secured and running at scale?
Behind the headlines, another business focuses on digital infrastructure itself. It supplies networking hardware and software that move, protect and manage data.
Those tools underpin private clouds, AI clusters and traditional enterprise systems. Operators use them to support heavier traffic and more complex workloads.
If AI and cloud buildouts keep needing sturdier plumbing, that provider’s importance could quietly grow. Your research list might stretch one rung further up the stack.
Could this be another way into the opportunity? → Explore the AI infrastructure opportunity and its 50% discount to one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com