


What Investors Got Wrong About Star Cement Before The Drop
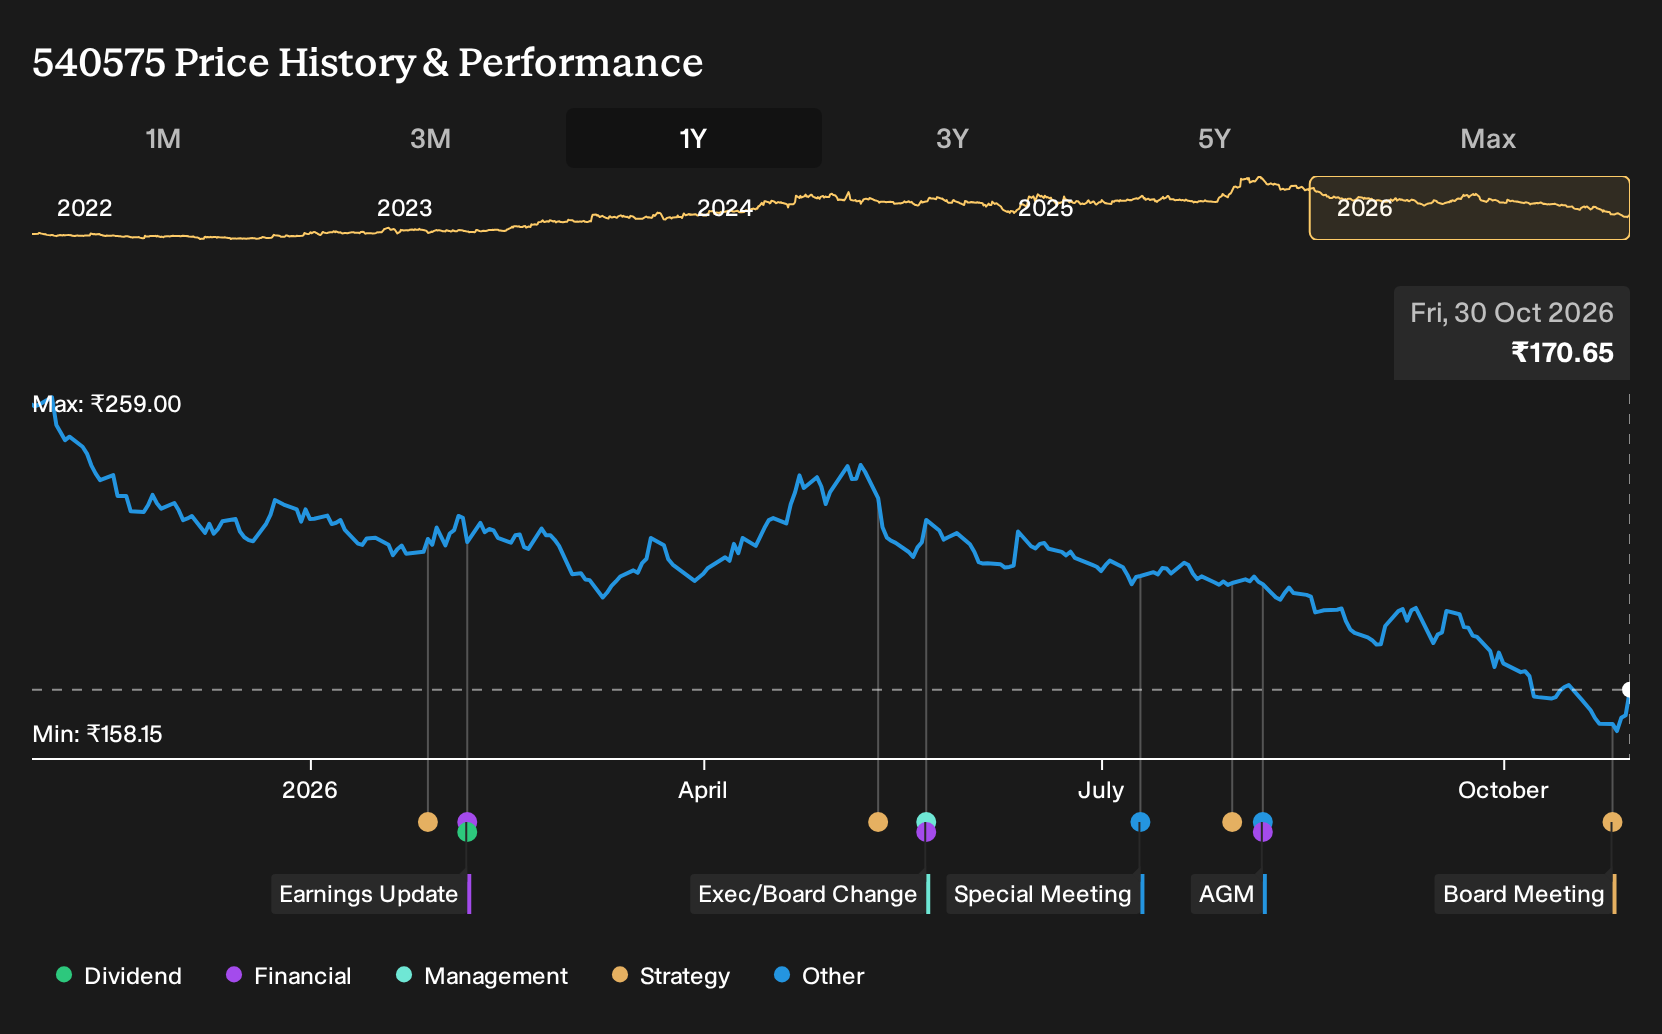
If you only glanced at Star Cement’s growth plans and the bullish analyst targets back in October 2025, the past year might look like it should have paid off. Holding Star Cement over the past year would have meant a 33.2% loss, including dividends. With revenue moving one way while net income and margins went the other in the latest results, the real question is which early clues pointed to that kind of outcome.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Star Cement harder to judge, start where the gap is still open and scan 199 high quality undervalued stocks.
The Two Stories Investors Were Weighing On Star Cement
The shares cost ₹256 at the start of the period, and the choice for anyone looking at Star Cement was between two very different stories that still sounded reasonable.
On the optimistic side, the bull narrative put fair value at ₹275, about 7% above the start price. This view hinged on faster plant ramp ups and green energy projects that were expected to cut power costs and lift margins.
The cautious bear view pinned fair value at ₹125, 51% below the start price. This perspective focused on heavy Northeast exposure and ongoing reliance on state incentives that could be reduced or delayed.
What The Results Changed For The Star Cement Story
The clearest data point came from earnings. Star Cement reported Q1 2027 revenue of ₹9,428.889m versus ₹9,119.925m a year earlier, while net income slipped to ₹747.166m from ₹984.549m and net margin moved from 10.8% to 7.9%. That pattern, more sales but thinner profitability, challenged the optimistic case that focused on stronger margins.
The lesson is simple. When a thesis leans on cost savings or richer pricing, track net margin just as closely as revenue and test the claim against each new result.
What You Would Be Paying For In Star Cement Today
Star Cement now trades at ₹171, down 33.2% over the past year. The selected Narrative argues that its Fair Value sits above the current price because the expansion and efficiency plan is not fully reflected.
The key assumption to test is whether Star Cement can scale new capacity and higher value cement volumes enough to offset weaker subsidies and tighter competition.
"The main factor that has to go right is that Star Cement offsets structurally lower subsidy income and potential Northeast price pressure by executing its cost optimisation, green power and logistics plans while scaling higher value trade and premium cement and building solutions volumes."
One Narrative disagrees with today's price. → See where this Narrative says Star Cement should trade
One Step Beyond Star Cement
Looking at Star Cement lets you track construction demand across buildings, roads and bridges. Yet another essential input quietly shapes a different kind of growth.
Crops must keep pace with rising food needs, whatever construction is doing. Farmers turn to fertilizer nutrients that are hard to replace.
One specialist miner is working to produce a key nutrient using adapted oil drilling techniques. The plan is to cut costs and reduce water use.
Instead of one giant operation, it proposes modular stages that can be expanded gradually. If the method scales, new fertilizer supply could arrive in a very different way.
That argument has a Narrative and a number behind it. → See the company one Narrative values 61% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com