


Mueller Industries (MLI) Dropped, What Is Driving Attention Now?
Mueller Industries (MLI) is back in focus after its third quarter earnings release, which was followed by a 6.59% share price drop and the announcement of a securities fraud investigation by law firm Pomerantz LLP.
Recent trading paints a mixed picture for Mueller Industries. The share price has fallen 9.98% over the past month and 17.84% over the past quarter, yet the 1-year total shareholder return is still 4.19% and the 5-year total shareholder return is very large at over 3x. This suggests that long-term holders have fared much better than more recent buyers as sentiment cools following the earnings miss and fresh legal scrutiny.
Scan how other industrials are reacting to earnings misses and legal headlines by comparing Mueller Industries with a curated set of 30 resilient stocks with low risk scores.Mueller Industries now trades well below both analyst targets and some fair value estimates after the post earnings slide. Is that a margin of safety, or a signal that the market’s caution on the legal overhang is warranted?
Price-to-Earnings of 13.8x: Is it justified?
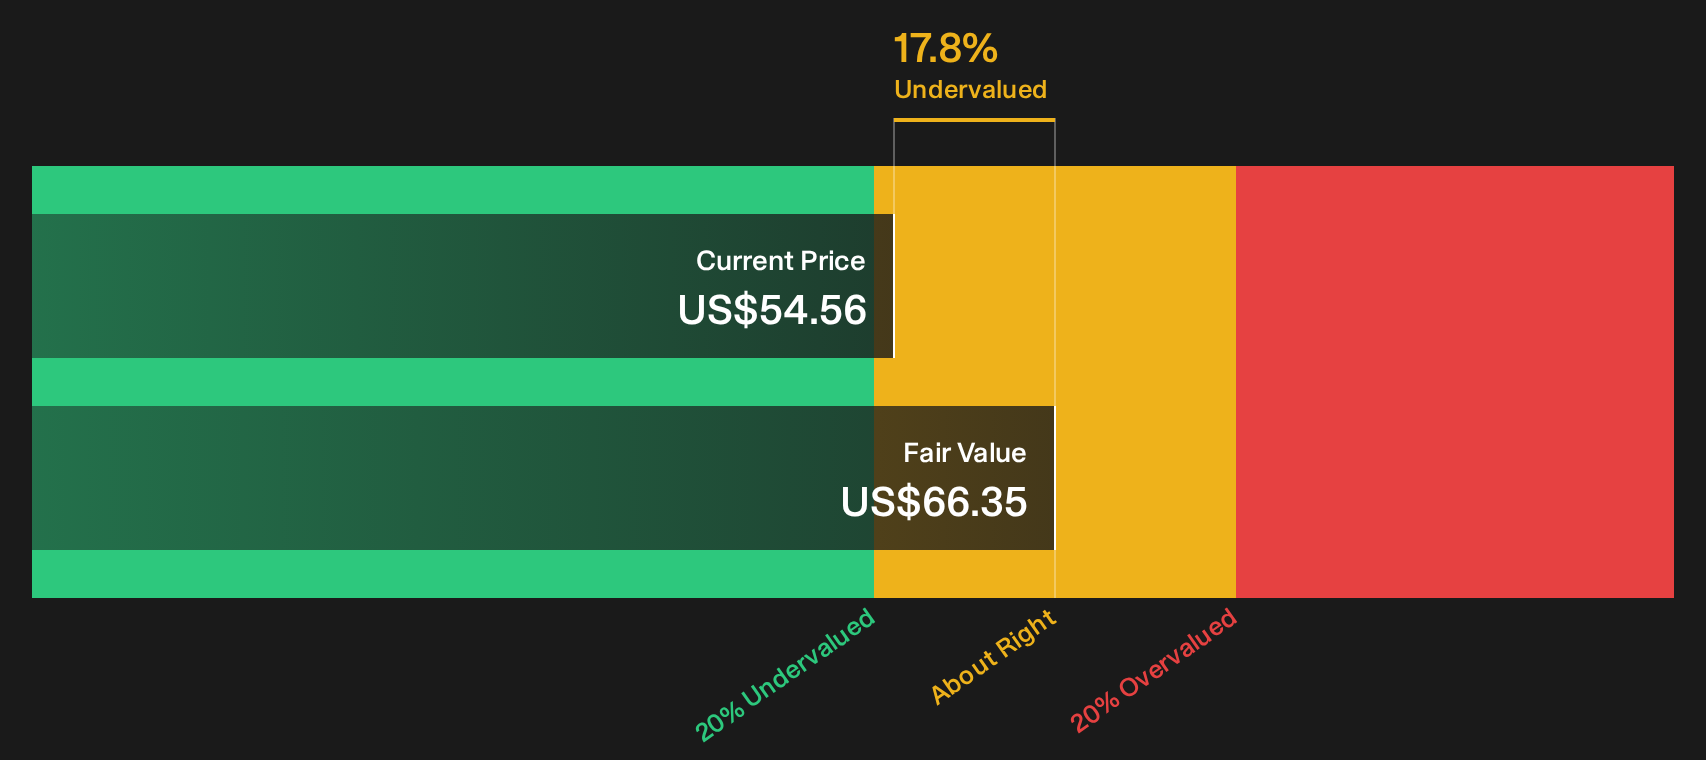
On traditional valuation metrics, Mueller Industries screens as inexpensive. At a P/E of 13.8x and a last close of $54.56, the stock trades at a discount to both the wider Machinery group and several internal fair value markers, including estimates that place the shares 17.8% below intrinsic value and 30% below the average analyst target of $78.00.
The P/E ratio compares what investors are paying today for each dollar of earnings. For a manufacturer like Mueller Industries, which reported revenue of $5.0b and net income of $863.6m, that filter helps you judge whether the market is assigning a rich or thin multiple to current profitability, rather than to more volatile sales or asset values.
Here the gap is wide. The stock trades at 13.8x earnings, while the estimated fair P/E based on a regression style “fair ratio” is 22.5x. The Machinery industry average is 24.2x, and comparable peers sit even higher at 32.5x. That is a notable relative discount that reflects the market assigning a much lower earnings multiple than both sector trends and quantitative fair value work might suggest if sentiment or the legal overhang were different.
Explore the SWS fair ratio for Mueller Industries.
Result: Price-to-Earnings of 13.8x (UNDERVALUED)
Still, the fresh securities fraud investigation and the recent share price decline could pressure Mueller Industries if legal outcomes or investor confidence turn against the current valuation story.
Find out about the key risks to this Mueller Industries narrative.
Another View: Cash Flows Back Up Mueller Industries' Valuation
That earnings based discount is only one angle. Our DCF model, which projects future cash flows and discounts them back to today, points to a fair value of $66.35 per share. With Mueller Industries at $54.56, the stock screens as undervalued on this framework too. So is the market overreacting to short term legal risk, or is it spotting something the models cannot fully capture?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mueller Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Mueller Industries is split, with litigation questions on one side and valuation support on the other. Move quickly to review the underlying data, weigh both the potential upside and the legal risks, and ground your own stance in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mueller Industries?
Once you have a view on Mueller Industries, widen your lens and line up a few fresh candidates for your watchlist before the next wave of results hits.
- Target potential mispricing by scanning a curated set of 29 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Strengthen your income stream by reviewing a hand picked group of 5 dividend fortresses that pair higher yields with resilient business profiles.
- Prioritise resilience under stress by assessing a focused list of solid balance sheet and fundamentals (25 results) so you are not caught off guard by weak finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com