


ITT (ITT) Sees Stronger Defense Demand, Is It Still Cheap?
ITT (ITT) just reported sharp momentum in its Connect and Control Technologies segment, with second quarter 2026 organic revenue up 17.3% and organic orders jumping 59%, helped by connector and defense demand.
ITT’s shares changed hands at US$198.50 at the last close, with a 7 day share price return of 4.42% and a year to date share price gain of 13.94%. The 3 year total shareholder return of 101.44% signals that longer term momentum has been strong, even as the 1 day move slipped 2% and the 30 day share price return eased 1.65% alongside the latest Connect and Control Technologies news and the kSARIA acquisition narrative.
Scan other industrials riding similar order momentum across our hand picked 39 power grid technology and infrastructure stocks.
ITT has been rewarding patient holders, yet the short term pullback after strong Connect and Control Technologies news leaves a real fork in the road. Investors may consider leaning in at US$198.50 or waiting for a cheaper entry point.
Most Popular Narrative: 23% Undervalued
Against ITT's last close at $198.50, the most followed narrative anchors fair value at $258.46, using an 8.9% discount rate and a backlog-heavy earnings view.
Strong, sustained order growth and backlog, supported by a company-level book to bill of 1.1 in Q2 2026, nearly doubled backlog over three years, and especially high ratios at Svanehøj and SPX FLOW, points to future revenue recognition that may not be fully reflected in ITT’s valuation.
See why 6 investors see ITT as 23% undervalued.
Result: Fair Value of $258.46 (UNDERVALUED)
Still, delays in project timing in multi year flow orders and slower than expected integration of SPX FLOW or kSARIA could weaken the ITT backlog driven narrative.
Find out about the key risks to this ITT narrative.
Another View: ITT Through The P/E Lens
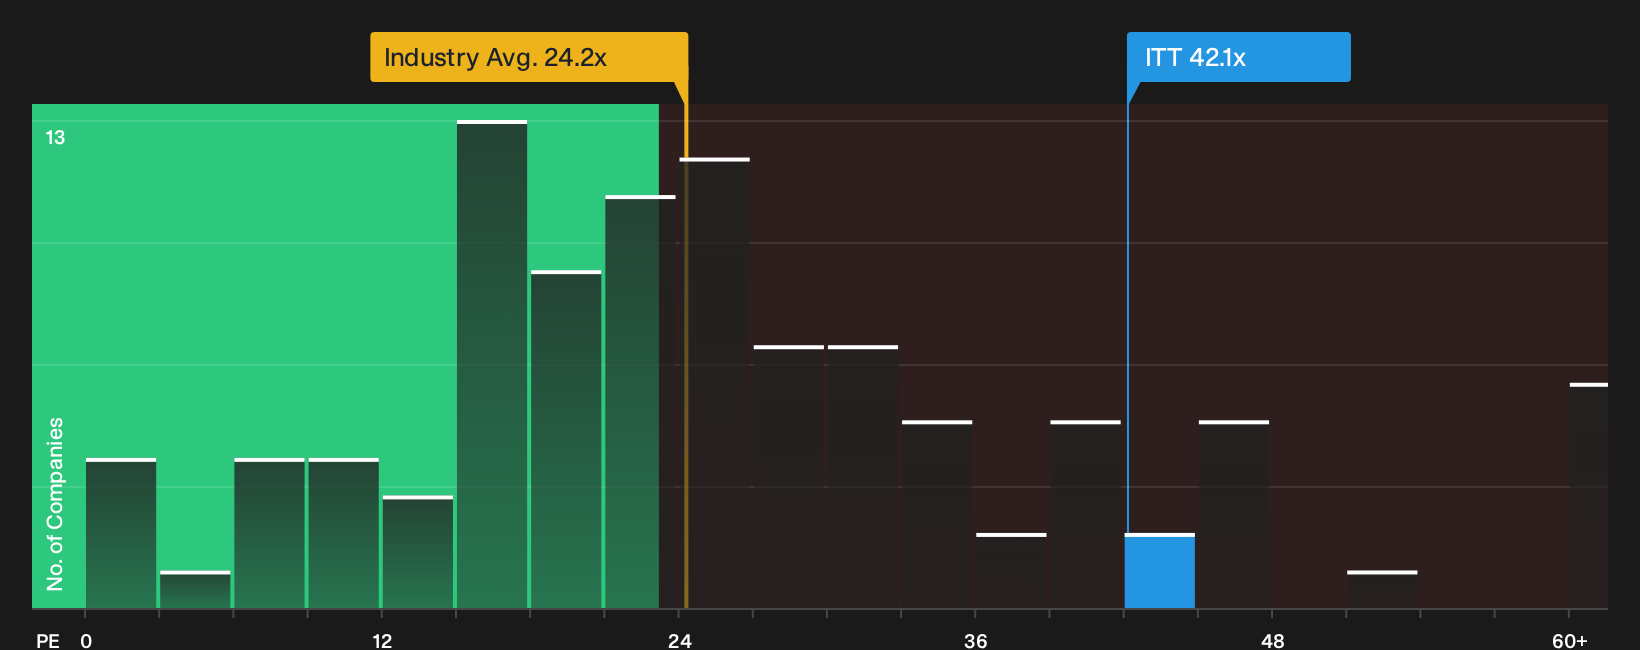
The backlog driven fair value of $258.46 paints ITT as 23% undervalued, yet the market is already paying a rich 42.1x P/E. That is well above the US Machinery group on 24.8x and also above a fair ratio of 28.5x, which points to clear valuation risk if expectations soften.
For investors weighing backlog strength against this premium earnings multiple, it helps to see how the current price compares to what the numbers alone imply for valuation pressure or support over time, and how peers with lower P/E ratios are being treated by the market See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on ITT's momentum and valuation can pull you in both directions, so move quickly to test the numbers yourself, weigh the backlog story against the premium P/E, and ground your decision in the full picture of 3 key rewards and 2 important warning signs.
Looking for more ITT sized investment ideas?
If ITT has you thinking harder about pricing power, backlog quality, and entry points, do not stop with one stock. Broaden your watchlist with focused screeners that surface very different types of opportunities before others move on them.
- Hunt for underappreciated quality by scanning our hand picked 29 high quality undervalued stocks that combine strong fundamentals with prices that lag underlying business strength.
- Lock in potential income streams by reviewing a curated set of 5 dividend fortresses built around higher yields and balance sheet support for payouts.
- Aim to lower portfolio stress by filtering for 30 resilient stocks with low risk scores that pair resilient finances with historically steadier trading patterns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com