


Hexcel (HXL) Stock Dropped, What Is Behind the Move?
Hexcel’s earnings beat and bobsled tie up put the stock in focus
Hexcel (HXL) has investors’ attention after reporting higher quarterly sales and net income, reaffirming its 2026 outlook, and joining a new composite focused partnership for next generation USA bobsled cowlings.
Hexcel’s share price has slipped in the short term, with a 30 day share price return down 7.25% and a 90 day move down 24.39%, even as earnings, guidance and the bobsled collaboration keep the story in the headlines. Zooming out, total shareholder return of 9.91% over one year and 30.03% over five years points to a stock where long term holders have still seen momentum build, despite recent pressure on the quote.
Scan beyond Hexcel and see how other aerospace and advanced materials players are setting up for the next leg higher with a curated list of 18 high quality undiscovered gems.
Hexcel’s latest sell off comes right after stronger earnings, guidance and a fresh partnership story, which raises a simple question: Is the lower price pointing to weaker fundamentals or just sentiment resetting the valuation bar?
Most Popular Narrative: 25.5% Undervalued
Hexcel’s most followed valuation narrative puts fair value at $104.47 versus a last close of $77.84. This indicates a wide gap that investors need to explain with either stronger growth conviction or higher perceived risk.
The anticipated ramp up in commercial aircraft production on programs like the Airbus A320neo, A350 and Boeing 787 and 737 MAX is now backed by management guidance that reaching OEM peak build rates could add about US$500 million in annual commercial revenue over the next 3 to 4 years. This would feed through to higher Hexcel sales and EBITDA.
See why 6 investors see Hexcel as 25% undervalued.
Result: Fair Value of $104.47 (UNDERVALUED)
Still, the Hexcel story can change quickly if inflation continues to squeeze long term Airbus contracts or if additional hiring and new carbon fiber capacity put pressure on margins.
Find out about the key risks to this Hexcel narrative.
Another View on Hexcel’s valuation
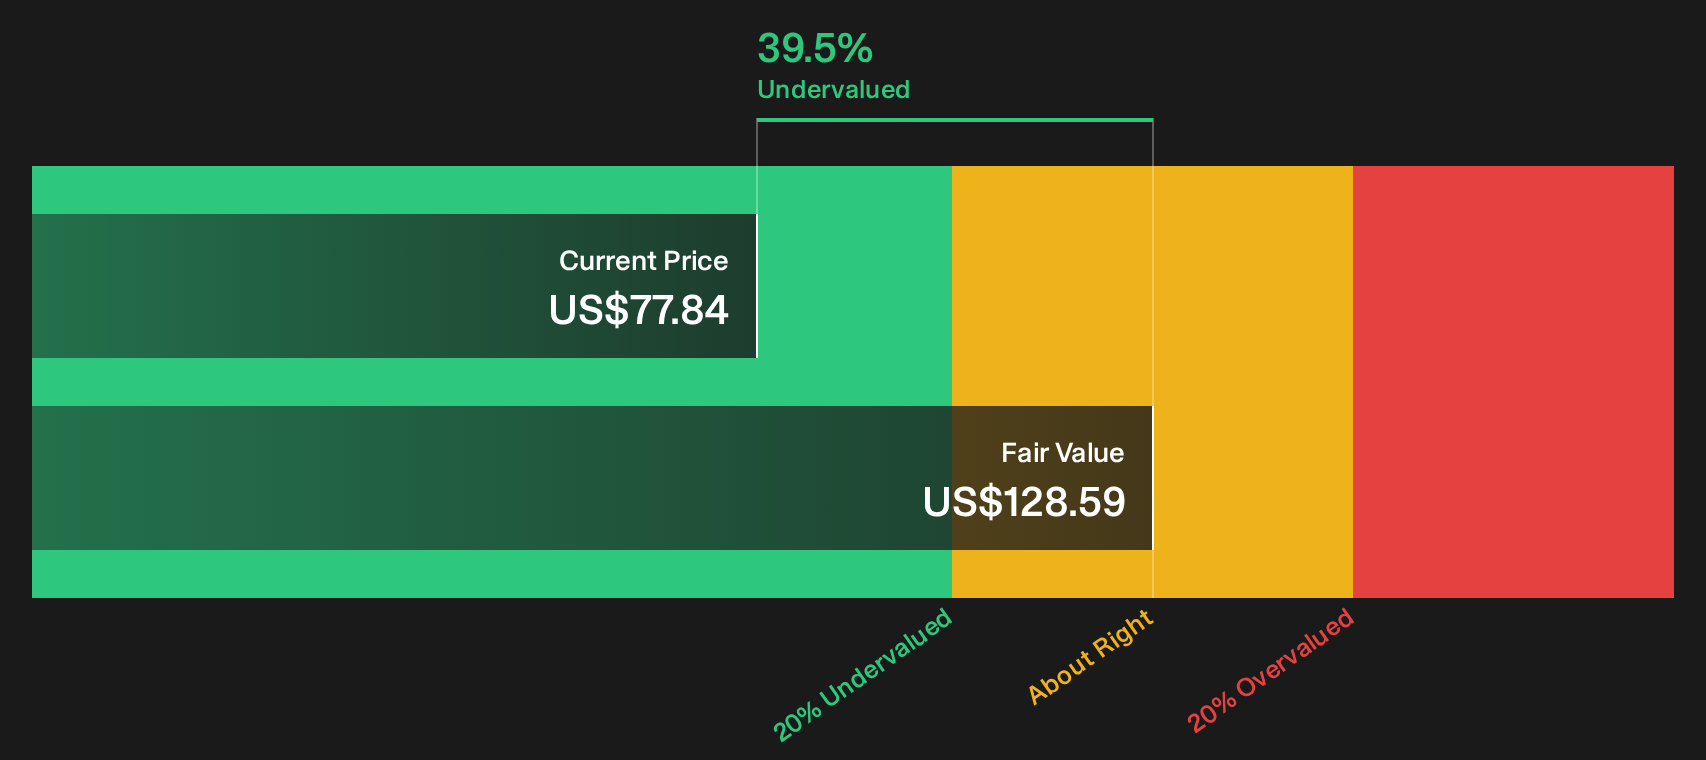
DCF work points in a very different direction. Our DCF model estimates Hexcel’s future cash flows at about $128.59 per share, compared with the current $77.84 price and the $104.47 fair value narrative. That implies a deeper undervaluation, which raises a simple question for you: Is the market discount about execution risk or about the cash flow assumptions themselves?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals often create the best reading on sentiment, especially when Hexcel is trading below some fair value estimates yet still carries both flagged risks and potential rewards. Move quickly, review the underlying data, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hexcel?
If Hexcel has your attention, do not stop there. Use the same structured approach across sectors so you are not relying on a single story.
- Target potential upside in quality businesses trading below intrinsic value by scanning the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies in the 5 dividend fortresses that pair yield with resilient payouts.
- Dial back portfolio risk by concentrating on financially robust companies using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com