


Is Earnings Beat Altering The Investment Case For Teladoc Stock (TDOC)?
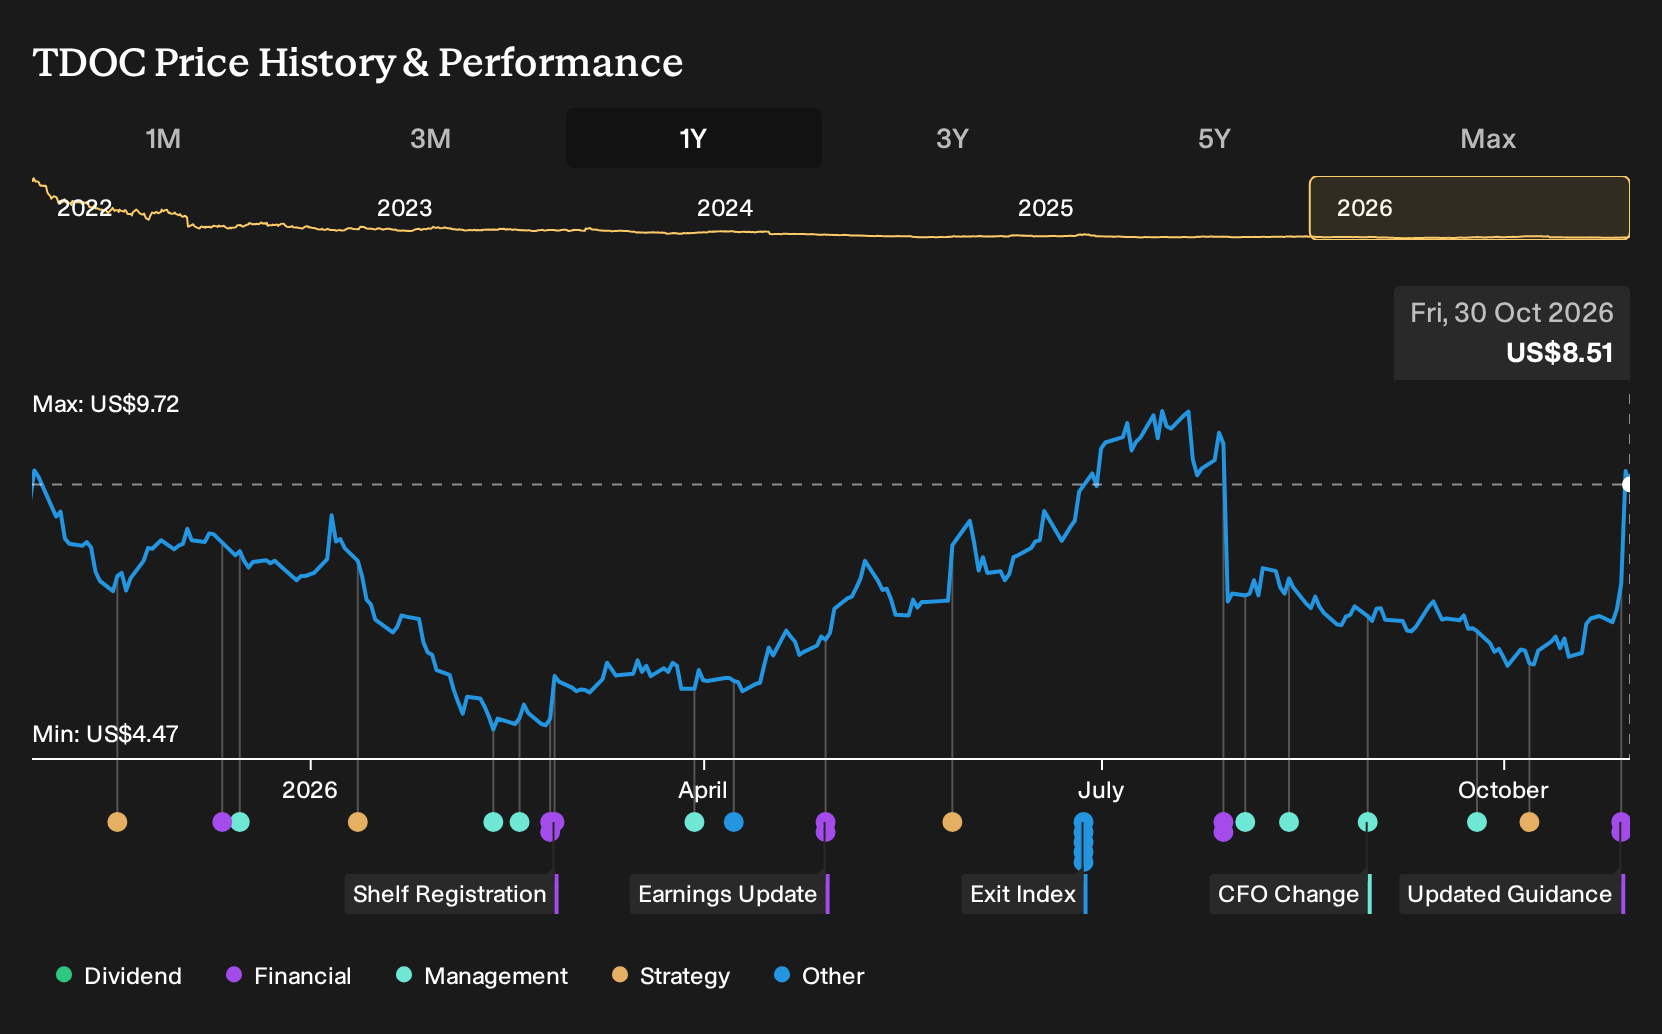
- Teladoc Health reported third quarter 2026 sales of US$605.1 million and a net loss of US$26.93 million, with basic loss per share from continuing operations of US$0.15. The company also issued guidance that points to a continued loss for the fourth quarter and full year 2026.
- Management highlighted improved adjusted EBITDA, stronger cash generation, and progress in shifting BetterHelp toward in-network insurance coverage. They also noted preparation for the Teladoc 1 unified care model, which aims to support more consistent margins and cash flow.
- We will now explore how Teladoc Health's improved loss profile and cash generation could influence the broader investment narrative around its turnaround.
Scan how Teladoc Health's earnings-driven rebound compares with other healthcare platforms reshaping virtual care by reviewing the hand picked 34 healthcare AI stocks.
Teladoc Health Investment Narrative Recap
To own Teladoc Health, you need to believe the company can turn a still loss making virtual care platform into a business with steadier margins and cash generation, even if revenue does not grow quickly. The latest quarter points to a tighter loss profile, but guidance still points to a full year loss, so the turnaround is unfinished.
The key near term catalyst is execution on the Teladoc 1 model and the ongoing shift of BetterHelp into insurance, which management argues should support more durable economics. The biggest risk is that the pivot away from higher margin cash pay users keeps pressuring gross margins and delays any path to consistent profitability.
The most relevant fresh data point is Teladoc Health’s updated 2026 guidance. Management now expects Q4 revenue to be between US$569 million and US$615 million and a net loss per share between US$0.23 and US$0.03. For the full year 2026, Teladoc Health guides to revenue between US$2.44b and US$2.94b and a loss per share of US$0.95 to US$0.75.
For you as an investor, that keeps the operational focus squarely on margin quality, cost control and cash generation rather than near term profit. It also frames upcoming quarters as tests of whether Integrated Care margins and BetterHelp’s insurance pivot can offset the structurally lower unit economics of covered visits and ongoing competition in virtual mental health and chronic care.
Teladoc Health's narrative projects US$2.6b revenue and US$172.9 million earnings by 2029. This reflects relatively flat yearly revenue expectations and an earnings increase of roughly US$344 million compared to the current earnings loss of US$171.1 million.
Uncover why Teladoc Health's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle on Teladoc Health leans heavily on BetterHelp as a pressure point. The lowest analysts were assuming revenue would decline about 3.1% a year and only reach roughly US$2.3b with US$161.4 million in earnings by 2029. That is a much gloomier setup. These pre news views could shift, so treat them as starting points and compare several narratives before deciding how you feel about the turnaround story.
Explore 3 other Teladoc Health fair value estimates, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Teladoc Health research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teladoc Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teladoc Health's overall financial health at a glance.
Looking For More Investment Ideas Beyond Teladoc Health?
If you want to cross check the Teladoc Health narrative against other opportunities, use the Simply Wall St Screener to line up different types of stocks and see how their fundamentals stack up side by side.
- If capital preservation is a priority, focus on stability first and scan through 30 resilient stocks with low risk scores that score well on resilience.
- If you are hunting for quality at a reasonable entry point, weigh Teladoc Health against a 29 high quality undervalued stocks that pair stronger balance sheets with supportive valuations.
- If you prefer companies that may have fewer eyes on them, broaden your watchlist with a 18 high quality undiscovered gems that combine solid fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com