


How Profit Collapse In China At Budweiser APAC Has Changed Its Investment Story
- Budweiser Brewing Company APAC reported Q3 2026 sales of US$1,449 million and net income of US$92 million, with nine month sales of US$4,620 million and profit of US$565 million, all below the prior year period.
- The sharp squeeze in Q3 profitability, with net income and basic earnings per share down by just over 50% year on year, highlights how ongoing volume and revenue pressure in China is outweighing growth in markets such as India and South Korea.
- Next is an assessment of how Budweiser Brewing Company APAC's investment narrative compares with this Q3 profitability squeeze in China.
Scan beyond Budweiser Brewing Company APAC and pressure in China by comparing it with a curated 199 high quality undervalued stocks that pairs solid balance sheets with proven cash generation.
Budweiser Brewing Company APAC Investment Narrative Recap
To own Budweiser Brewing Company APAC, you need to be comfortable with a simple tension. The story leans on premium brands, in home and O2O channels, and higher growth regions like India and South Korea, while China remains the key swing factor. The latest quarter, with profitability squeezed, reinforces how much that China drag still matters to group earnings.
In the near term, the main catalyst is whether management can stabilise volumes and lift mix in China without further eroding margins, as input costs such as aluminum are expected to rise under its hedging policy. The biggest risk is that weak on premise demand in China proves more structural, which could keep group profitability under pressure even if India and South Korea continue to perform relatively better.
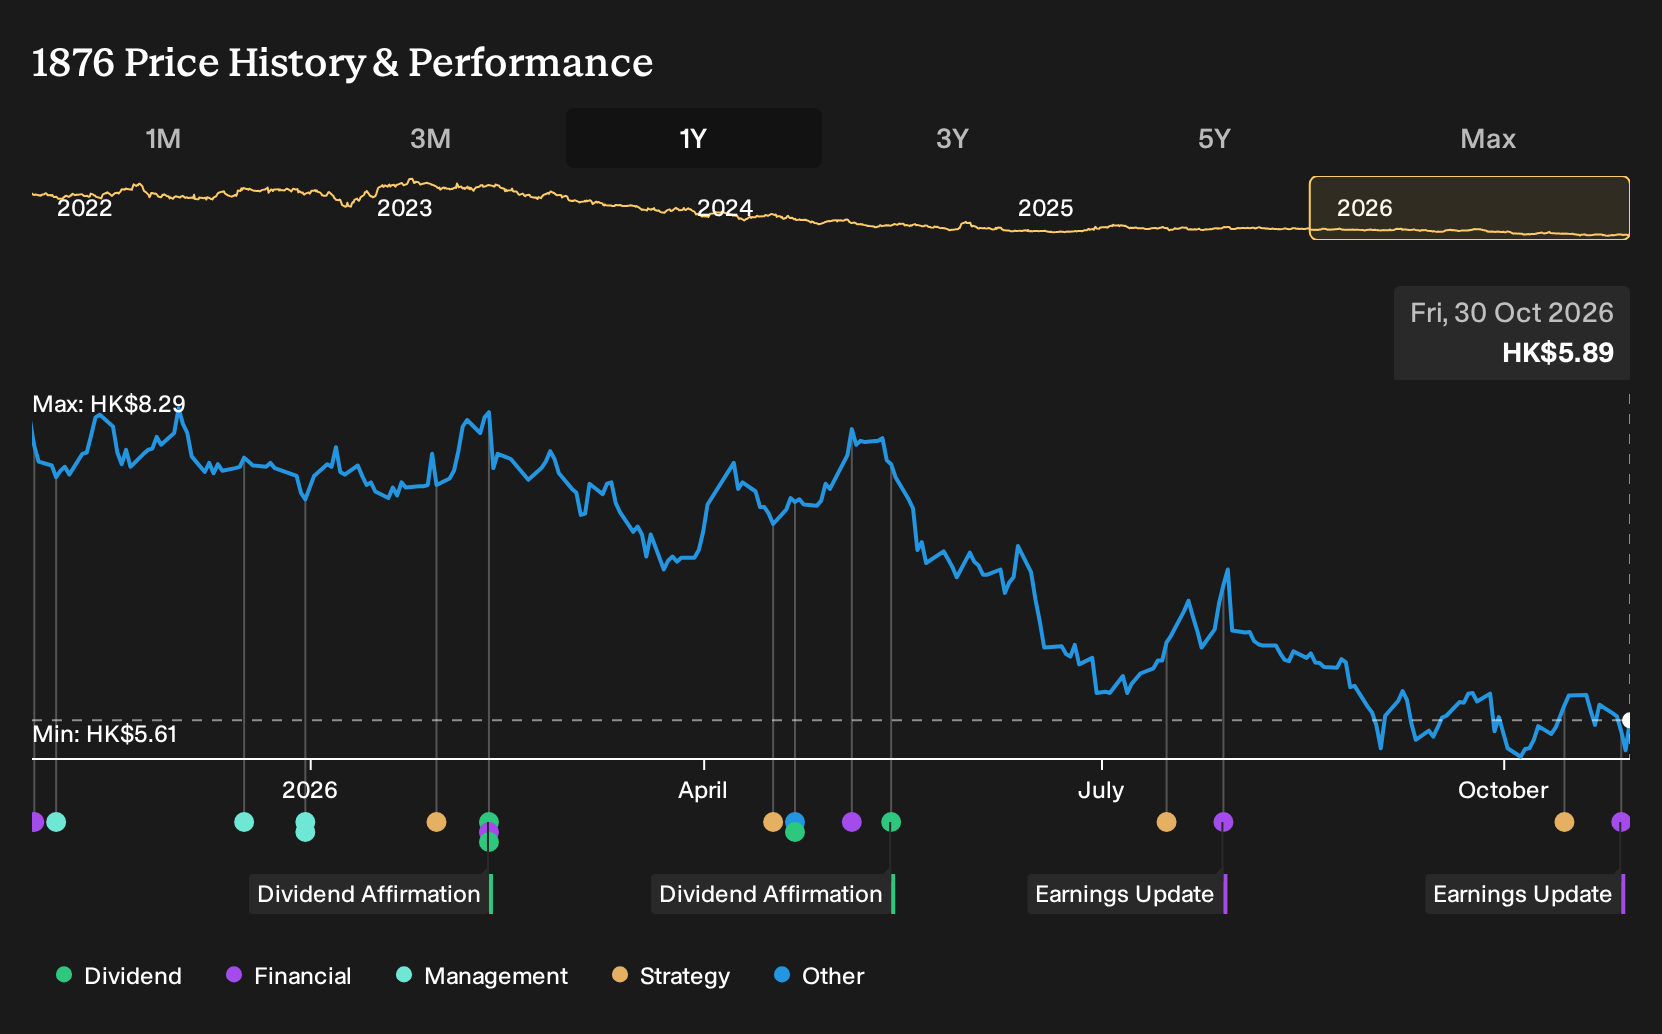
The most relevant update is the Q3 and nine month 2026 earnings announcement on 28 October 2026. Sales for the quarter were US$1,449 million compared with US$1,555 million a year earlier, while net income fell from US$185 million to US$92 million. That drop in profit, much steeper than the top line movement, points directly to margin strain as China volumes and pricing come under pressure.
Across the first nine months, Budweiser Brewing Company APAC reported US$4,620 million in sales versus US$4,691 million a year ago, with net income of US$565 million compared with US$594 million. For anyone tracking catalysts, these numbers put more weight on execution in China, cost discipline as aluminum hedges roll through, and continued growth and mix improvement in India and South Korea to offset the softness in the largest market.
Budweiser Brewing Company APAC Consensus Assumptions Under the Microscope
Analysts are effectively asking you to look through the current China squeeze and focus on where Budweiser Brewing Company APAC might land by the end of the decade. Their models build around a few core building blocks. Revenue is assumed to rise at 4.2% a year over the next three years, while profit margins are expected to move from 9.5% today to 12.3% in the same window. On that foundation, the consensus view points to earnings climbing from US$553.0 million today to US$809.0 million by about 2029, with more cautious forecasts still sitting at US$587.8 million.
That earnings bridge matters for anyone trying to square the current profitability squeeze with the longer term story. Moving from US$553.0 million to US$809.0 million implies an increase of roughly US$256 million in annual profit. To get there, the business would need both higher revenue and wider margins, not just one or the other. The margin lift from 9.5% to 12.3% does a lot of the heavy lifting in those forecasts. It assumes that current cost pressure and weaker China volumes do not permanently cap profitability at today's levels.
Valuation work ties these operating assumptions directly into the share price debate. On the consensus numbers, Budweiser Brewing Company APAC would be trading at a P/E of 20.6x on 2029 earnings, compared with about 17.7x today and against a Hong Kong beverages sector multiple of 18.5x. The implied step up in the earnings multiple indicates that analysts are not just baking in higher profits. They are also assuming investors would be willing to pay a richer P/E for those future earnings than for both the stock today and the sector average.
There is also a live discussion around how much faith to put in these projections. Current targets cluster around HK$8.0 a share, with optimistic calls at HK$11.6 and more cautious views at HK$6.0. The range reflects different views on how far China can recover, how durable India and South Korea are as profit engines, and how much margin expansion is realistic once higher aluminum costs and ongoing brand investment are taken into account. For you as an investor, the practical takeaway is straightforward: any view on Budweiser Brewing Company APAC over the next few years hinges on whether those assumptions on revenue growth, profitability and the future P/E appear achievable.
Budweiser Brewing Company APAC's current analyst framework points to revenues of US$6.6b and earnings of US$809.0 million by 2029, which builds in 4.2% yearly revenue growth and an earnings increase of about US$256 million from current earnings of US$553.0 million.
Uncover why Budweiser Brewing Company APAC's fair value indicates a 36% potential upside to its current price, which could narrow quickly as expectations reset.
Exploring Other Perspectives
You might focus on the China risk, but bullish analysts were watching a different catalyst before this earnings drop. They were leaning on India and South Korea, where they expected Budweiser Brewing Company APAC to help lift earnings toward about US$868.9 million by 2029. That is far more optimistic than the lowest forecasts near US$586.7 million. These projections were set before the Q3 squeeze. Treat them as moving pieces and explore a range of views before deciding what this new information means for you.
Explore another Budweiser Brewing Company APAC fair value estimate, including one that suggests potential upside of as much as 143% from the current price.
Decide For Yourself
Don't just follow the ticker. Instead, dig into the data and build a conviction that is truly your own.
- A great starting point for your Budweiser Brewing Company APAC research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Budweiser Brewing Company APAC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Budweiser Brewing Company APAC's overall financial health at a glance.
Looking for more investment ideas beyond Budweiser Brewing Company APAC?
If this Budweiser Brewing Company APAC review has sharpened your thinking but you still want a wider field of options, broaden your watchlist using targeted screeners that filter for the specific traits you care about most.
- If resilience matters most to you, start with a curated 218 resilient stocks with low risk scores that keeps the focus on companies with steadier risk profiles rather than just headline growth stories.
- For investors who care about balance sheet strength as much as earnings, filter for companies on a list of solid balance sheet and fundamentals (203 results) and quickly spot businesses that pair financial stability with fundamental support.
- If you prefer uncovering earlier stage opportunities, scan through a 126 elite penny stocks with strong financials that highlights smaller companies with stronger financial underpinnings than the typical micro-cap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com