


What RS Group Doubters Got Wrong
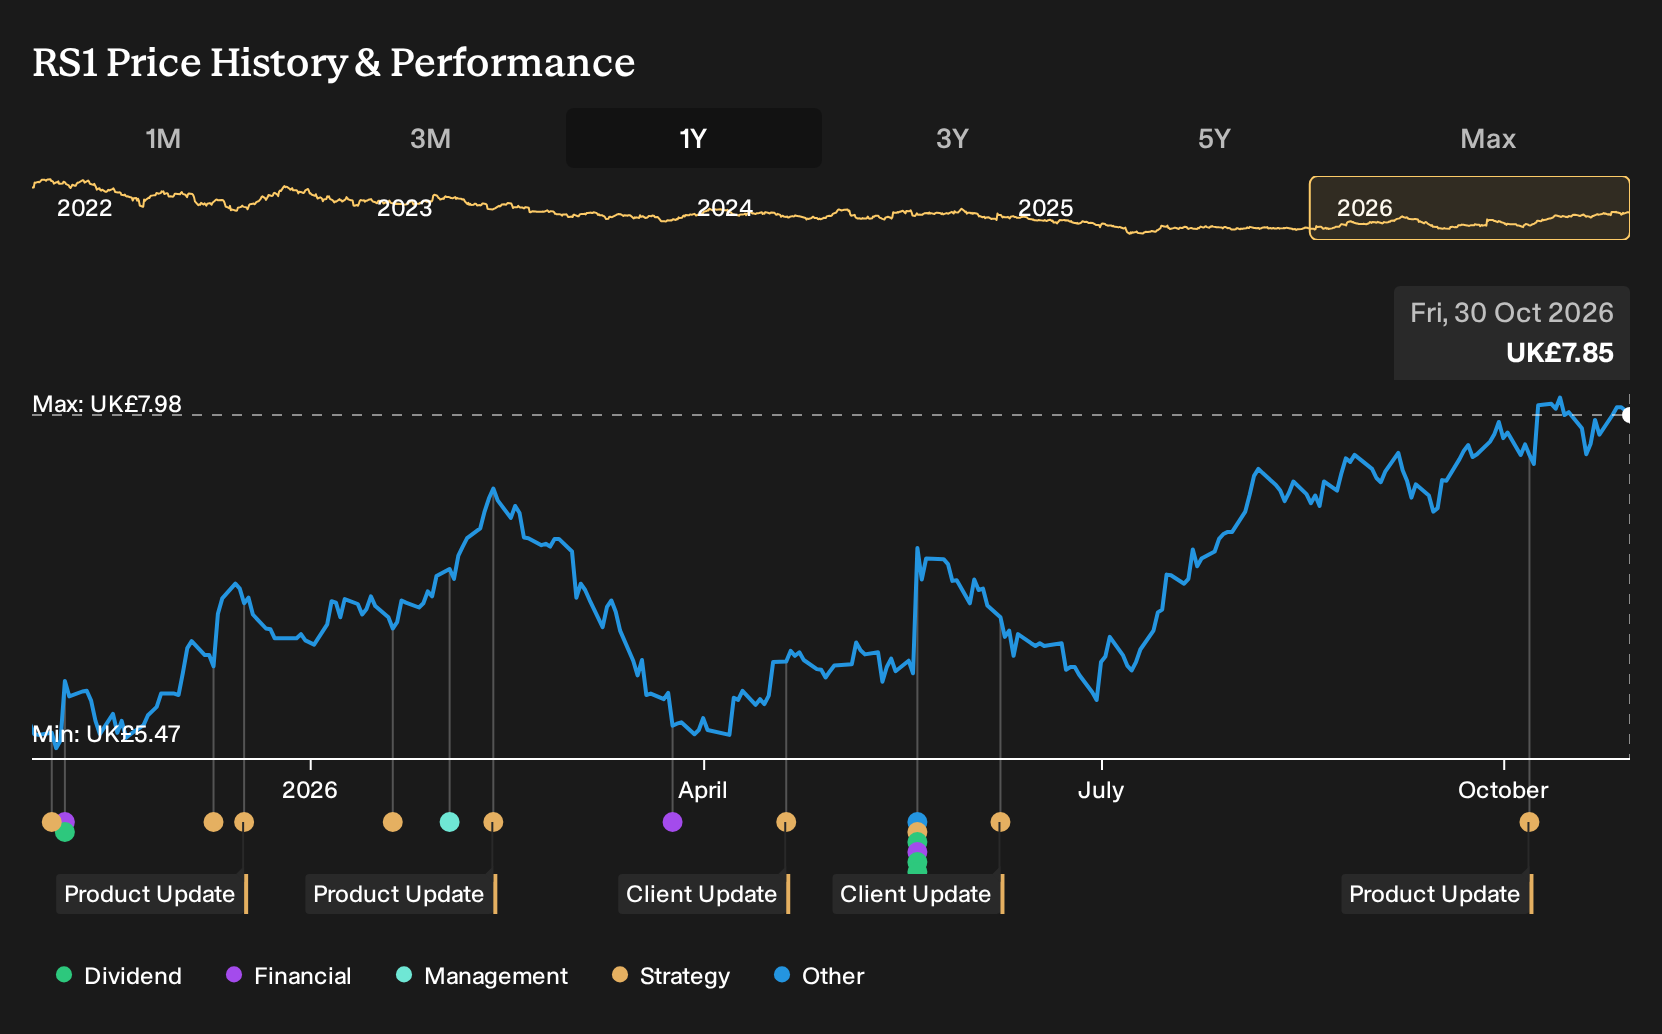
Berenberg’s decision to lift its target on RS Group to 900p ahead of first half results put one concrete datapoint on the table, even before the latest revenue and net income figures arrived. For RS Group shareholders, the return over the past year was 46.6%, including dividends. If you were deciding whether to buy on 30 October 2025, what exactly did you need to believe about AI-driven commerce and Distrelec integration to justify that outcome?
The move put RS Group in the middle of this trade. Scan 96 robotics and automation stocks for other companies exposed to it.
The Two RS Group Stories Investors Were Arguing About
The shares cost £5.57 at the start of the period, and RS Group sat between two very different but credible stories about its future.
The bullish view put Fair Value at £7, a price that reflected what believers thought the underlying cash flows could support if Distrelec integration delivered scale benefits and higher margins alongside AI-led digital commerce.
The cautious camp fixed Fair Value at £4.8 and focused on risks such as manufacturers selling directly to customers, which could bypass RS Group and squeeze its traditional distribution economics over time.
What The RS Group Results Actually Tested
The most concrete evidence arrived with H2 2026 numbers. RS Group reported revenue of £1,478.3m and net income of £79m, with net margin at 5.3% compared with 5.1% in H2 2025. That shift in profitability leaned toward the AI and Distrelec efficiency story, although the modest margin level still left plenty of room for the digital bypass risk to matter. Overall, the evidence cut both ways.
The practical lesson is simple. When a thesis hangs on integration and AI-driven commerce, watch the reported net margin and cost ratios, not just revenue. Then ask whether those figures move in the direction the story implied and whether the change is large enough to justify the price you are being asked to pay.
What RS Group's Current Price Already Assumes
RS Group now trades at £7.85, and the selected Narrative places its Fair Value below that level, arguing that the present quotation already bakes in successful digital execution and efficiency gains.
The key bet is that heavier technology and operating spend still turns into a better mix and profitability. The question is how rising ongoing technology costs and restructuring charges affect that assumption if customer adoption or demand slows.
"The numbers imply the share price already factors in successful execution on digital growth, mix shift and cost reduction, leaving limited room for disappointment if cyclical end markets or self-chosen investment spend weigh on earnings. Management plans to push organic OpEx investment towards the top of the £35m to £45m range for several years and broaden share based incentives by £5m to £10m annually."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 43% below our estimate - uses a rebuilt cloud tech stack and AI tools to deliver member products efficiently.
- Company 2 - 31% below our estimate - expands fee based access to renewable infrastructure and tax efficient retail investment offerings.
- Company 3 - 39% below our estimate - shifts client assets into higher fee private market strategies that raise fee related earnings.
Three companies from the same screener. Open all 12 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com