


What RH (RH)'s Earnings Drop Means For Shareholders
- RH faces an expected earnings per share of $0.67 and more than 60% year-over-year compression. Revenue is projected to rise slightly, highlighting pressure on profitability even as sales hold up.
- The firm trades on a forward P/E above its industry. GuruFocus scores its profitability at 8/10 and its financial strength at 3/10, which puts extra attention on how effectively RH converts its premium positioning into cash generation.
- We will now look at how RH's investment narrative holds up against the expected earnings drop that is weighing on sentiment.
Compare RH with a curated group of premium brands and quality retailers by scanning the 29 high quality undervalued stocks, which may offer stronger valuation support for their earnings profile.
RH Investment Narrative Recap
To own RH, you need to believe the gallery model, RH Estates and international flagships can turn a premium brand into consistent cash generation even through a choppy housing and renovation cycle. The expected 60%+ EPS compression, despite slightly higher revenue, keeps the short term focus squarely on margins and cost discipline.
The recent share pullback after a 2.74% daily decline adds pressure, but it does not fundamentally change the near term catalyst. Investors are still watching whether European galleries, higher price point assortments and lower capital spending start to ease the earnings squeeze before any housing or tariff shock worsens demand or input costs.
The most relevant data point to this earnings setup is that RH’s financial strength is scored at 3/10, with interest payments described as not well covered by earnings. When the market expects EPS of $0.67 and a big year over year drop, that balance sheet profile keeps execution risk on the front burner.
RH already carries an above industry P/E multiple, so the next few quarters become a test of whether gallery productivity, RH Estates mix shift and real estate monetization plans show up in cleaner profitability rather than one off gains. If those efforts do not translate into steadier earnings coverage of interest, the premium valuation and recent share price volatility may continue to attract elevated short interest.
RH's narrative projects US$4.5b revenue and US$308.5 million earnings by 2029. This implies 9.6% yearly revenue growth and an earnings increase of about US$197 million from US$111.5 million today.
Uncover why RH's fair value indicates a 13% potential upside to its current price that could narrow quickly.
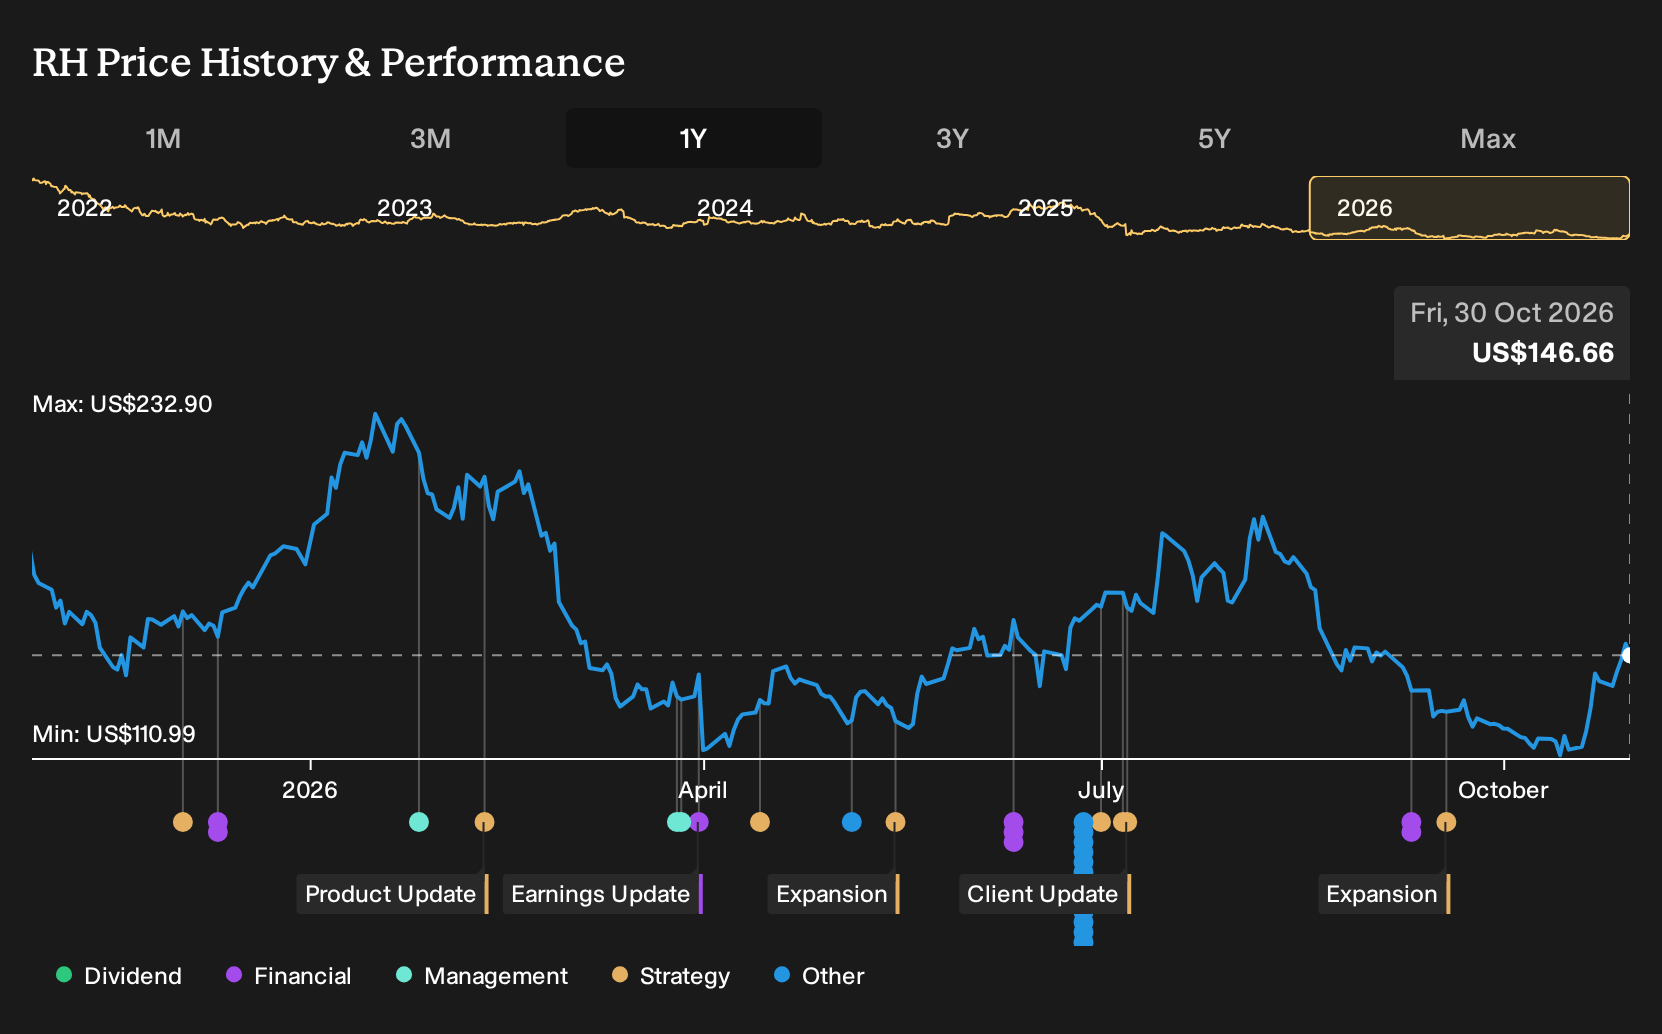
Exploring Other Perspectives
One alternate view pins the key risk on margins, not housing. The most bearish analysts expected RH to reach only about US$4.4b of revenue and roughly US$119.7 million of earnings by 2029, far below the consensus US$308.5 million path. That gap shows how sharply opinions differ and why this latest earnings shock could reshape both narratives.
Explore 4 other RH fair value estimates, including one that suggests as much as 44% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RH research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RH's overall financial health at a glance.
Looking For More Ideas Beyond RH?
Once you have a view on RH, it helps to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can surface a range of businesses that match the kind of portfolio you want to build, not just the one headline stock that caught your eye today.
- If you care most about finding companies that look mispriced relative to their quality, start with a focused set of 29 high quality undervalued stocks that may offer a balance between fundamentals and expectations.
- For investors who want reliable balance sheets and fewer surprises, filter for a list of solid balance sheet and fundamentals (25 results) that can anchor the risk profile of your holdings.
- If you are hunting for ideas the market might be overlooking, scan a 18 high quality undiscovered gems that pair fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com