


COSCO SHIPPING Ports (SEHK:1199) Faces A Fresh Valuation Test Following Mixed Q3 Earnings
COSCO SHIPPING Ports (SEHK:1199) just put fresh numbers on the table with its third quarter 2026 earnings, reporting higher sales and throughput, flat net income, softer earnings per share and heavier capital spending.
That earnings update landed alongside a sharp shift in sentiment, with COSCO SHIPPING Ports’ share price up 7.42% in the last session and showing an 18.20% 90 day share price return, while the 3 year total shareholder return of 57.97% points to momentum that has been building rather than fading.
Scan how COSCO SHIPPING Ports compares to other transport and infrastructure plays on our hand picked list of list of solid balance sheet and fundamentals (203 results) for ideas beyond this quarter's earnings move.
COSCO SHIPPING Ports is clearly moving containers and cash flow, yet the latest price jump raises a different question. Are you paying a fair price for that scale and spending push, or already paying up for it?
Most Popular Narrative: 5% Overvalued
The most followed valuation view puts COSCO SHIPPING Ports’ fair value at HK$5.99 versus a last close of HK$6.30. This implies a modest premium and asks investors to judge whether recent momentum justifies paying up.
The analysts have a consensus price target of HK$5.99 for COSCO SHIPPING Ports based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of HK$5.96, the analyst price target of HK$5.99 is 0.5% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 4 investors see COSCO SHIPPING Ports as 5% overvalued.
Result: Fair Value of HK$5.99 (OVERVALUED)
Still, the COSCO SHIPPING Ports story can change quickly if the much higher 2026 CapEx fails to earn its keep, or if Belt and Road trade flows slow more sharply.
Find out about the key risks to this COSCO SHIPPING Ports narrative.
Another View: SWS DCF Says COSCO SHIPPING Ports Looks Cheap
Analysts calling COSCO SHIPPING Ports about 5% overvalued are leaning on their HK$5.99 fair value, yet the SWS DCF model points in a very different direction. On that cash flow view, HK$6.30 is well below an estimated value of HK$9.84, which frames the recent rally as leaving a wide gap. Which lens do you trust more for a long term decision?
Look into how the SWS DCF model arrives at its fair value.
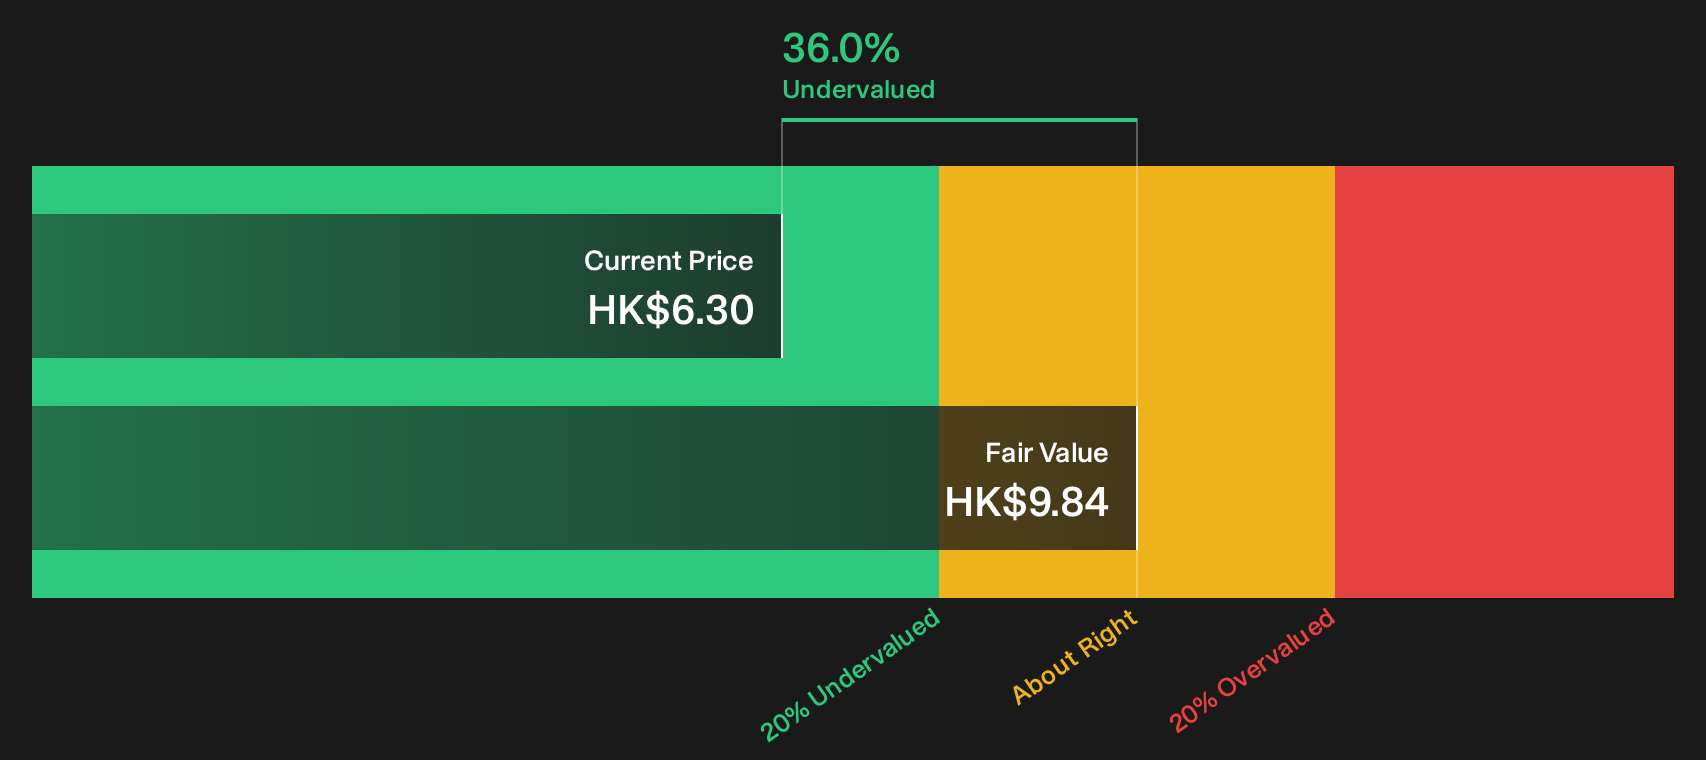
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out COSCO SHIPPING Ports for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like these only matter if you put them in context yourself, and act before sentiment lurches again. To weigh both the upside story and the pressure points around COSCO SHIPPING Ports, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond COSCO SHIPPING Ports?
If COSCO SHIPPING Ports has your attention, do not stop here. Broaden your watchlist with a fresh mix of value, resilience and income ideas.
- Hunt for quality at a discount and scan companies that combine strong fundamentals with appealing valuations using the 199 high quality undervalued stocks.
- Prioritise staying power and focus on resilient businesses with robust financial footing by checking the 218 resilient stocks with low risk scores.
- Put reliable cash payouts on your radar and shortlist income ideas by reviewing the 221 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com