


How Investors Are Reacting To Array Digital Infrastructure Stock After Tower Rental Improvement
- Array Digital Infrastructure reported stronger fixed wireless user engagement and healthier tower rental activity after efficiency efforts and cost controls improved profitability in a competitive market.
- The breadth of Array Digital Infrastructure’s tower relationships across major U.S. carriers points to a tower rental base that appears less dependent on any single tenant.
- We will now look at how Array Digital Infrastructure’s improved operational efficiency could influence the existing investment narrative around its tower platform.
Scan beyond Array Digital Infrastructure and compare its tower and wireless backdrop with a curated list of 39 power grid technology and infrastructure stocks
Array Digital Infrastructure Investment Narrative Recap
To own Array Digital Infrastructure you need to be comfortable with a tower-focused story that is still replacing lost DISH revenue while managing declining consensus forecasts for both earnings and sales over the next three years. The recent update on stronger fixed wireless engagement and steadier tower leasing supports that tower-centric thesis but does not fully erase those pressures.
Right now the near-term swing factor is how quickly Array backfills sites and lifts cash site rental income as it leans into a pure infrastructure model. The biggest risk is that recent Q1 revenue and EPS shortfalls become a pattern, which, combined with high non-cash earnings, could keep confidence in future margins fragile.
The clearest backdrop for this news is Array Digital Infrastructure’s earlier move to become a stand-alone tower platform with about 4,400 U.S. sites and a plan to monetize roughly 70% of its spectrum. That repositioning plus US$1.17b of completed spectrum sales already tilted the story toward tower cash flow, colocation and partnership income.
When you place the stronger user engagement and healthier tower rental activity against that pivot, the operational focus is clear. Execution around raising tenancy ratios, managing tenantless locations and sustaining carrier master lease revenues now sits alongside spectrum monetization and partnership distributions as the practical catalysts to watch rather than one-off financial optics.
Array Digital Infrastructure Forecasts And Valuation Setup
Analyst expectations around Array Digital Infrastructure now lean heavily on a smaller, tower centric earnings base that looks very different from the spectrum heavy profile investors grew used to. The consensus view ties the story to falling revenue, sharply lower profit margins and a much leaner earnings stream by the end of the decade.
The assumptions are blunt. Forecasts point to Array Digital Infrastructure’s revenue declining by 1.6% a year over the next three years, while profit margins are expected to compress from 310.9% today to 16.6% by 2029 as the mix shifts. Earnings are projected at US$33.7 million in 2029 compared with US$663.8 million today, which is a drop of about US$630 million in absolute profit, even as shares on issue are expected to creep higher by 0.11% annually.
On those numbers, the current analyst framework assumes investors will accept a P/E of 137.6x on the 2029 earnings, versus 4.5x today and above the US wireless telecom industry multiple of 18.4x. That is a very large uplift in the earnings multiple for a business that consensus still models with shrinking top line and thinner profitability.
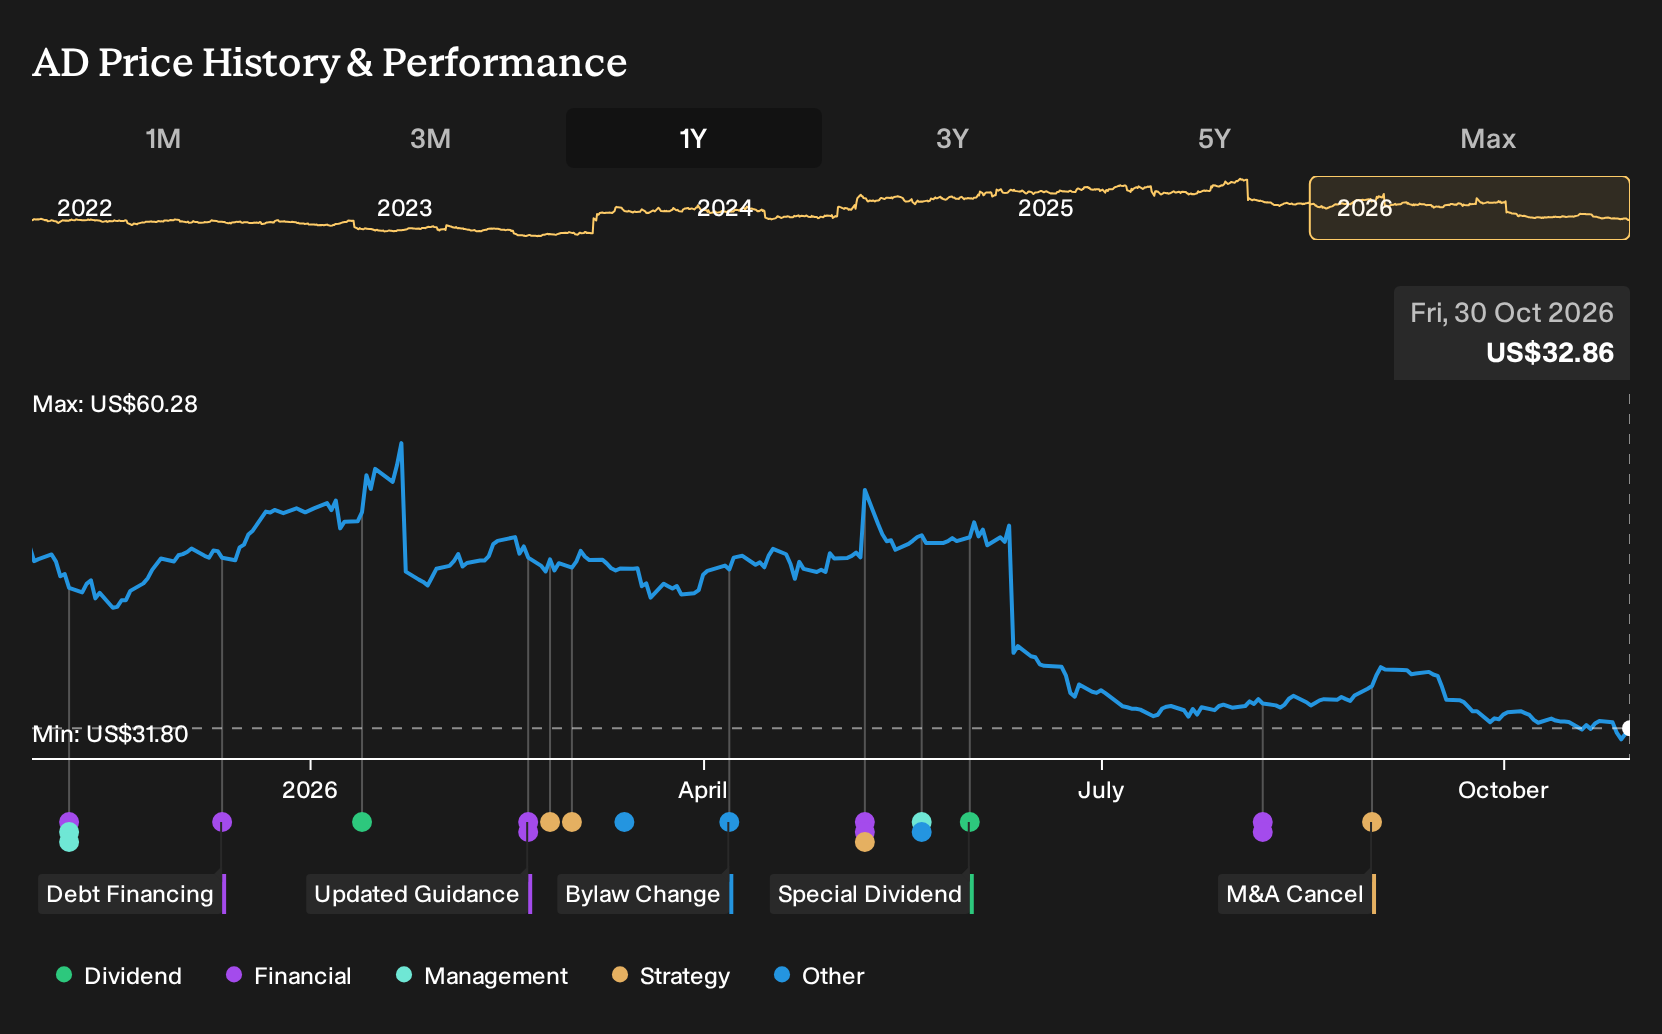
The valuation case folds in these earnings, revenue and risk inputs into a discounted view of fair value using a 7.2% to 7.24% discount rate. At today’s US$34.39 share price, the average analyst target of US$43.33 sits 20.6% higher. This suggests the street framework assumes the market is already pricing in a lot of bad news around tower leasing, DISH runoff and the reset in profitability.
Array Digital Infrastructure's narrative projects US$203.3 million revenue and US$33.7 million earnings by 2029, which lines up with analyst expectations for a 1.6% yearly revenue decline and an earnings drop of about US$630 million from the current US$663.8 million base.
Uncover why Array Digital Infrastructure's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on tower colocation growth at Array Digital Infrastructure, not just DISH replacement risk. Before this news, the bullish camp was modelling roughly flat revenue at about US$219.9 million and earnings of US$58.8 million by 2029. Views clearly differ, so treat this update as a prompt to compare several narratives side by side.
Explore 2 other Array Digital Infrastructure fair value estimates, including one that suggests as much as 32% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Array Digital Infrastructure research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Array Digital Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Array Digital Infrastructure's overall financial health at a glance.
Looking For More Investment Ideas Beyond Array Digital Infrastructure?
If you want to balance your view on Array Digital Infrastructure with fresh ideas, a quick scan of broader opportunities can help you pressure test your thesis and avoid anchoring on a single ticker.
- For investors hunting for overlooked strength, consider a 18 high quality undiscovered gems that already show solid fundamentals yet receive far less attention than larger peers.
- If capital preservation and steadier profiles matter most to you, narrow your focus to a 30 resilient stocks with low risk scores that score well on resilience and balance sheet quality.
- When you want a sturdier financial base behind any potential upside, filter for a list of solid balance sheet and fundamentals (25 results) that pair healthier leverage levels with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com