


Surprised By Laxmi Organic Industries' Fall? What Bears Saw
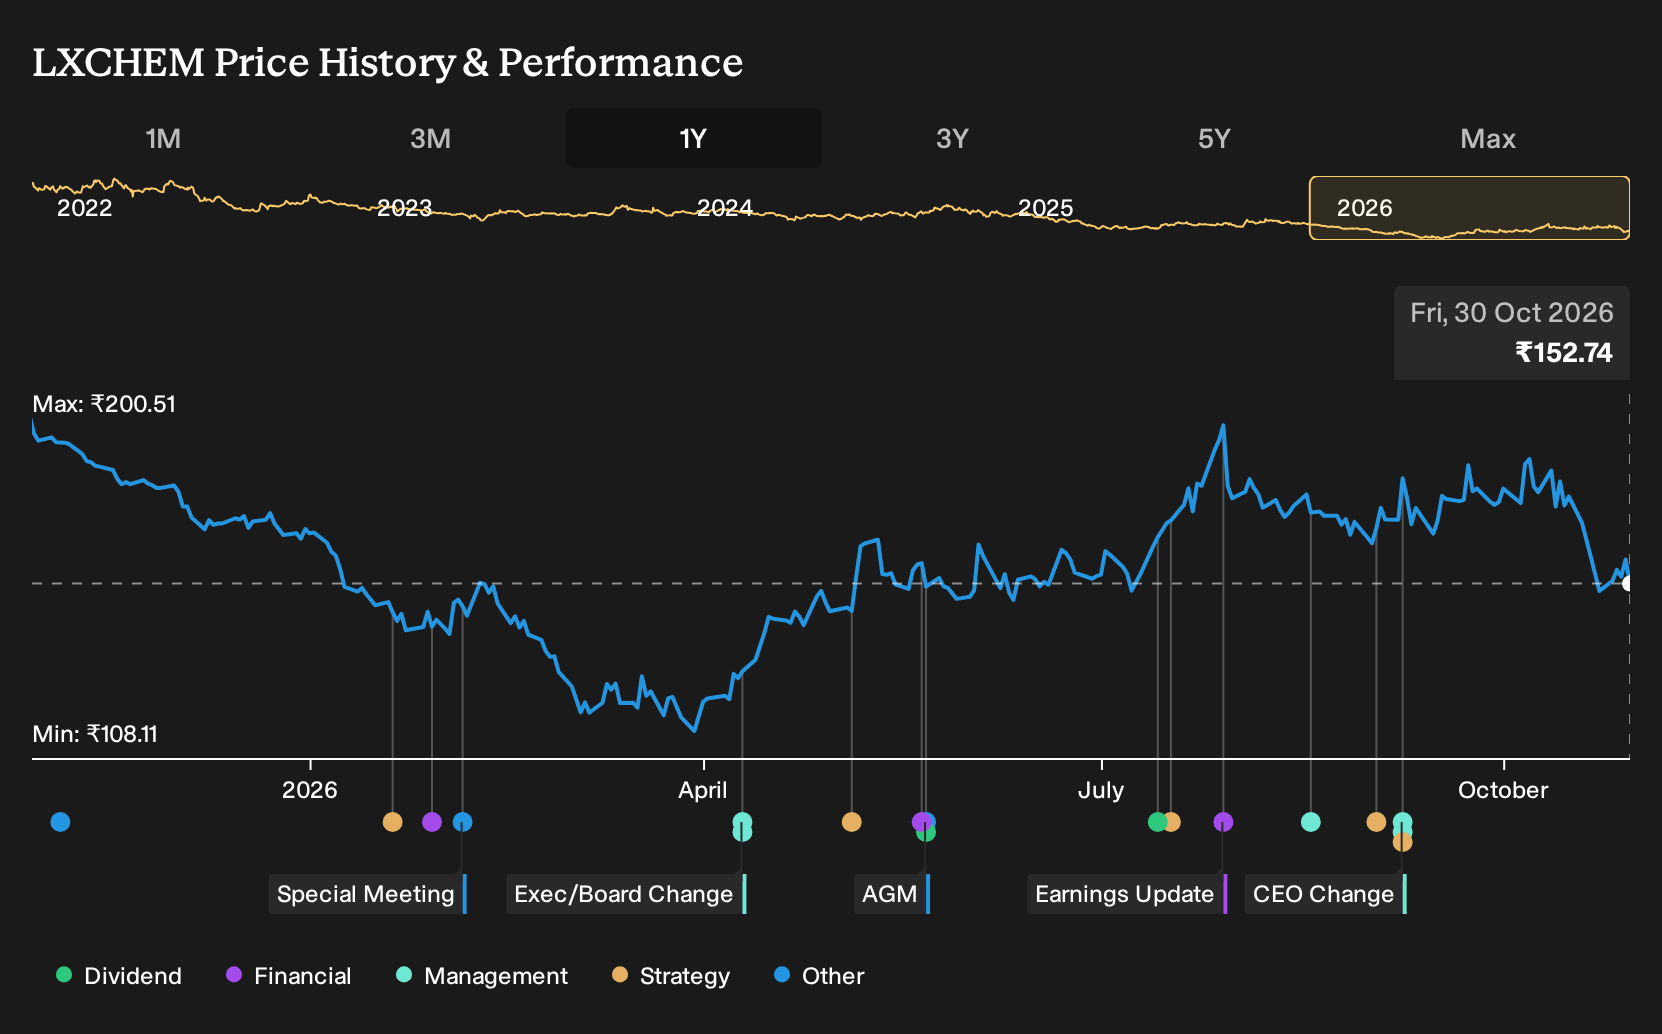
Laxmi Organic Industries just reported Q1 2027 numbers with higher revenue and a net margin that moved from 3.1% in Q1 2026 to 7.0%. For Laxmi Organic Industries shareholders, the loss over the past year was 21.9%, including dividends. If you had bought on 30 October 2025, that outcome might feel jarring next to fresher profit headlines. The real puzzle is whether that margin shift marks a durable business reset worth rethinking the earlier expectations.
The easy part of this move is behind Laxmi Organic Industries. Zero in on 199 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Arguing Over On Laxmi Organic Industries
The shares cost ₹198 at the start of the period, so anyone looking at Laxmi Organic Industries had to decide which story to trust.
The bullish narrative pointed to a Fair Value of ₹247. That price would only make sense if green chemistry bets and eco efficient gases, such as the Hitachi Energy SF6 replacement project, supported stronger, more stable net margins.
The bearish view worked off a Fair Value of ₹179. This assumed that tightening ESG rules, higher compliance costs, and pressure on legacy acetyl products could weigh on profitability.
What The Results Changed For The Laxmi Organic Industries Debate
The clearest new fact is the Q1 2027 step up in profitability, with revenue at ₹9,683.38m and net income at ₹677.16m, which lifted Laxmi Organic Industries’ net margin from 3.1% to 7.0%. That margin shift leaned toward the bullish story that argued for stronger earnings power, although a single quarter still leaves the longer term profitability argument open.
The takeaway is simple. When a thesis hangs on better economics rather than just more volume, track the reported net margin alongside sales. That pairing tells you whether a higher price assumption rests on efficiency gains the business is actually delivering.
What The Fall In Laxmi Organic Industries Now Asks You To Believe
Laxmi Organic Industries trades at ₹153 after a 21.9% loss over the past year, while the selected Narrative’s Fair Value sits above the current price based on its own assumptions about the business.
The argument leans on contracted ramps at Dahej and fluorination, so a buyer today must judge whether those projects ramp on time and restore healthier Specialty margins.
"Key Takeaways: Analysts expect Laxmi Organic Industries to use new capacities in diketene derivatives, ethyl acetate and fluorination, along with multi year contracts, to build on recent revenue and EBITDA traction while managing the inherent cyclicality in its Essentials business. The main factor that has to go right is the timely ramp up and customer qualification of the Dahej and fluorination projects, along with restoring healthier Specialty margins after the loss of a key agro intermediate and the impact of lower feedstock prices on pricing."
The price and this Narrative do not agree. → Uncover what this Narrative says Laxmi Organic Industries is actually worth
Looking Beyond Laxmi Organic
You have seen how Laxmi Organic turns chemistry into earnings power swings. The next question is where similar demand pressures could appear elsewhere.
Industrial chemicals rely on vast quantities of raw materials. Someone is supplying metals and minerals that support construction and cleaner energy projects.
This other business focuses on iron ore, copper and coal. Its operations help keep steelmaking and electrification projects stocked with essential inputs.
The twist is straightforward. Earnings there lean heavily on commodity prices and shifts in iron ore demand from major buyers. If you are weighing Laxmi Organic, that shared exposure to global cycles might deserve attention.
One Narrative has already put a figure on it. → Uncover the company trading 53% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com