


Is Waste Management (WM) Undervalued Following Q3 Guidance And Its CEO Transition?
Waste Management (WM) put fresh numbers around its outlook after third quarter 2026 results, guiding full year revenue toward the high end of its US$26.275b to US$26.475b range and updating investors on buybacks and leadership changes.
Over the past month, Waste Management has seen a 14.48% share price return, with a 6.89% year-to-date gain and a 1-day move of 1.10% after the Q3 update. Total shareholder return of 18.81% over one year and 57.99% over five years points to momentum that has been building rather than fading around the latest guidance, buybacks, and the upcoming CEO transition.
Spot similar waste and infrastructure plays showing strong cash generation and capital returns by scanning our hand picked 29 high quality undervalued stocks alongside Waste Management.Waste Management now trades about 9% below both intrinsic value estimates and the average analyst target after this run. Is that a genuine safety margin, or the market’s way of pricing in execution risk around the next phase and new CEO?
Most Popular Narrative: 8% Undervalued
Compared with Waste Management’s last close at $233.45, the most followed narrative points to a fair value of $253.84. This implies some cushion if those assumptions hold and capital returns stay disciplined.
The main thing that has to go right is that Waste Management turns its large investments in healthcare solutions, recycling automation and renewable natural gas into sustained cross sell, synergy capture and free cash flow conversion now that major capex is largely complete.
The current valuation implies the share price does not fully reflect a business that is growing operating EBITDA, expanding margins, lifting free cash flow conversion toward the high 40s% to low 50s% range and benefiting from scarce disposal and energy assets.
See why 93 investors see Waste Management as 8% undervalued.
Result: Fair Value of $253.84 (UNDERVALUED)
Still, this story can change quickly if renewable natural gas tax credits roll off, or if Stericycle synergies and healthcare margins fall short of expectations.
Find out about the key risks to this Waste Management narrative.
Another View: What Waste Management’s P/E Is Telling You
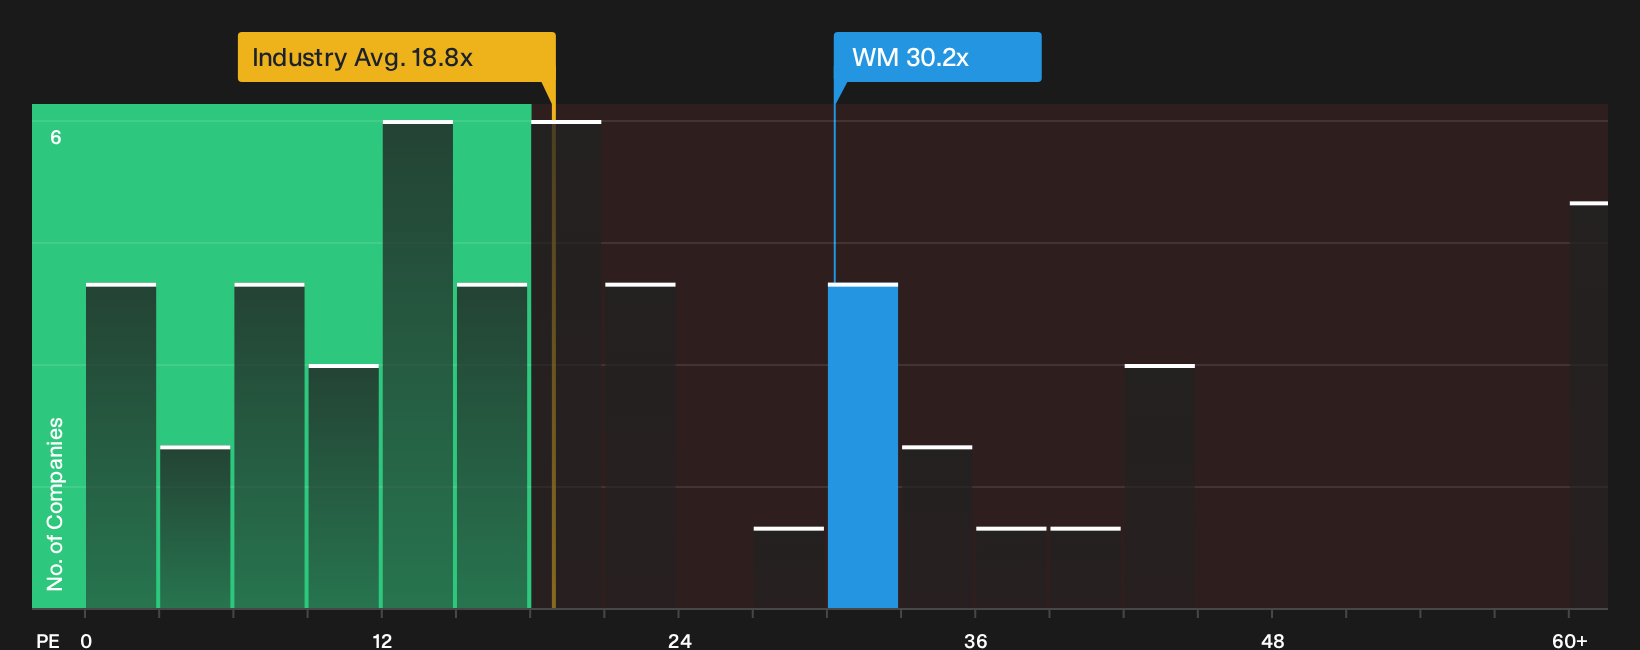
The story looks a bit different when you swap the fair value model for a simple earnings multiple. Waste Management trades on a P/E of 30.2x, above its own fair ratio of 26.5x and well ahead of the US Commercial Services average at 18.8x, even though it sits just below peer levels at 33.3x. That mix of rich versus industry and cheaper versus close comparables raises a blunt question for investors: Is this a quality premium worth paying, or a pricing risk if sentiment cools?
For a closer look at how that P/E gap could close over time, including what the fair ratio might move toward as expectations reset, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether Waste Management’s story here feels more cautious or optimistic to you? Act quickly and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Waste Management?
If Waste Management has sharpened your focus on quality, do not stop here. Broader opportunities could slip past if you ignore what the wider market is offering.
Use the Simply Wall St Screener to quickly surface focused ideas that match different portfolio goals.
- Target more resilient holdings by checking companies that score well on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underappreciated opportunities by scanning the 18 high quality undiscovered gems before other investors start paying attention.
- Explore income-focused ideas by reviewing a curated set of yield-focused opportunities in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com