


Did Cut Growth Guidance Just Shift Haleon's (LSE:HLN) Investment Narrative?
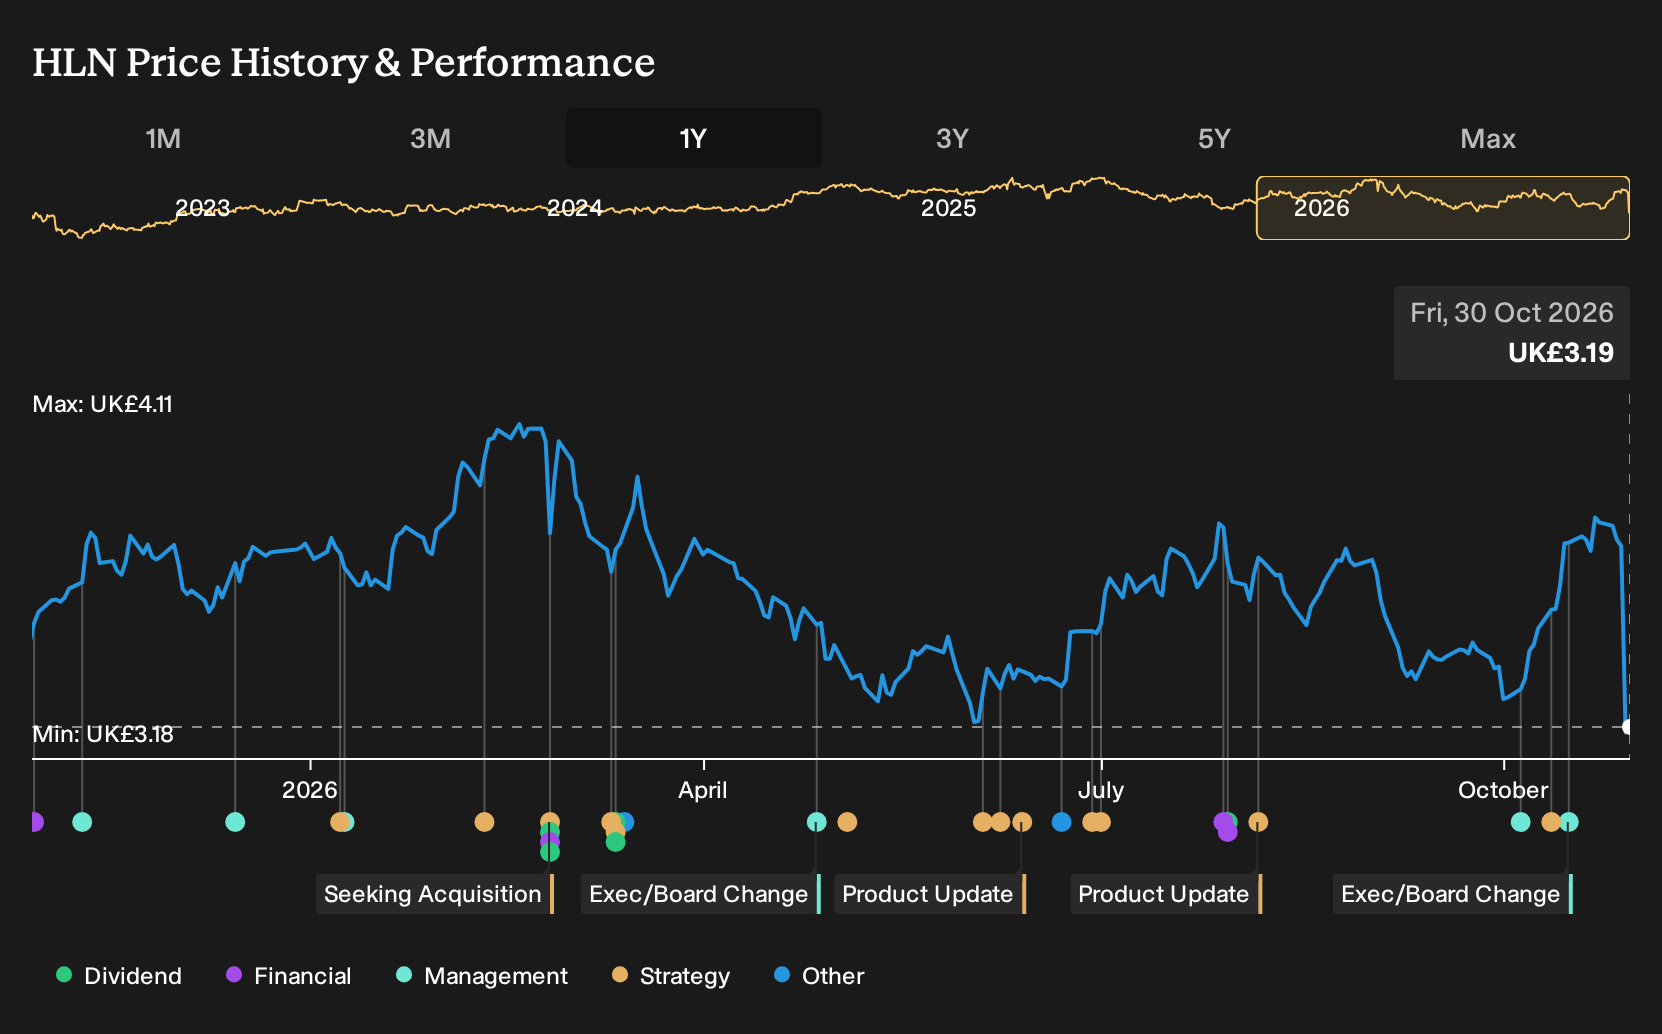
- Haleon recently reported weaker than expected third quarter revenue, cut its full year organic growth guidance and cited soft cold and flu demand, regulatory hurdles in China for Centrum and muted European consumption as key pressures on the business.
- The group is pushing ahead with a £500 million share buyback and operational changes, even as volume growth and respiratory trends remain under pressure. This highlights a tension between capital returns and the need to reinforce its underlying growth engine.
- We will now examine how Haleon's investment narrative is affected by the trimmed growth guidance and what that means for the business outlook.
Compare Haleon’s reset growth story with other consumer-facing opportunities by scanning our hand picked 12 high quality undervalued stocks, which pair resilient cash flows with stronger balance sheets.
Haleon Investment Narrative Recap
To stay with Haleon, you need to believe the core engine is still oral health, emerging markets and cost efficiency, and that these can offset a softer respiratory cycle. The reset to around 2.5% organic growth guidance puts more weight on how quickly management can stabilise volume, especially in North America and Europe.
The most important near term swing factor is whether cough, cold and flu demand normalises from this weak season. The biggest risk is that subdued respiratory volumes and the China Centrum restrictions stretch beyond current expectations, which would keep group organic growth tracking below the 4% to 6% ambition.
The new £500m share buyback matters because it interacts directly with these operating questions. A large repurchase while volumes are under strain and organic growth guidance is lower effectively tightens the spotlight on execution in respiratory health, Centrum and the European consumer channel.
If Haleon delivers on cost programs and keeps oral health and emerging markets steady, the buyback could reduce the share count while those operational levers play out. If volume momentum remains weak or regulatory issues in China weigh on vitamin revenues longer than planned, the same buyback could look like capital that might otherwise have supported balance sheet flexibility.
Haleon Forecasts and What They Assume
Haleon's consensus narrative relies on analysts expecting roughly mid single digit revenue expansion over several years, paired with firmer profitability. The current working assumption is that sales increase by 4.2% each year for the next three years, while profit margins rise from 14.6% today to 16.8% over that period.
On earnings, the market is modelling a climb from £1.6b today to £2.1b by 2029, with the most optimistic forecasts stretching to £2.4b. That £500m uplift implies earnings growth of a little over 30% in absolute terms, before factoring in any benefit from the planned 0.26% annual reduction in the share count.
These projections feed directly into how Haleon is being priced. To align with the analyst framework, investors would need to accept a scenario where, by 2029, revenue reaches £12.6b and earnings are £2.1b. In that case, the shares would be trading on a 21.6x P/E multiple, compared with about 20.7x today. The industry backdrop also matters, since that future multiple sits below the current P/E of 23.1x for the wider GB pharmaceuticals sector.
Haleon's narrative projects £12.6b revenue and £2.1b earnings by 2029. This assumes 4.2% yearly revenue growth and about £500m earnings increase from £1.6b today.
Uncover how Haleon's fair value indicates a 31% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate angle on Haleon focuses on a potential snap back in Respiratory Health as a major catalyst, which is a sharp contrast to today’s weak cold and flu backdrop. The most optimistic analysts were already pencilling in revenue of about £13.1b and earnings of £2.4b by 2029, so that bullish script may now be up for revision. You can treat this as a reminder that forecasts differ widely and that it is worth comparing several competing stories before deciding which one you find more convincing.
Explore 4 other Haleon fair value estimates, including one that suggests as much as 95% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Haleon research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Haleon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Haleon's overall financial health at a glance.
Looking For More Investment Ideas Beyond Haleon?
Haleon might be your starting point, but you can widen your watchlist by using the Simply Wall St Screener to compare different types of opportunities side by side.
- For investors who like mispriced quality, review a curated 5 high quality undiscovered gems that may not yet feature on mainstream radars but still show solid underlying fundamentals.
- If capital protection matters just as much as upside, filter for companies with sturdier financial positions using our list of solid balance sheet and fundamentals (10 results).
- For a more defensive tilt, scan resilient candidates with historically steadier risk profiles through the 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com