


How Investors Are Reacting To Bank First Stock After Earnings Beat
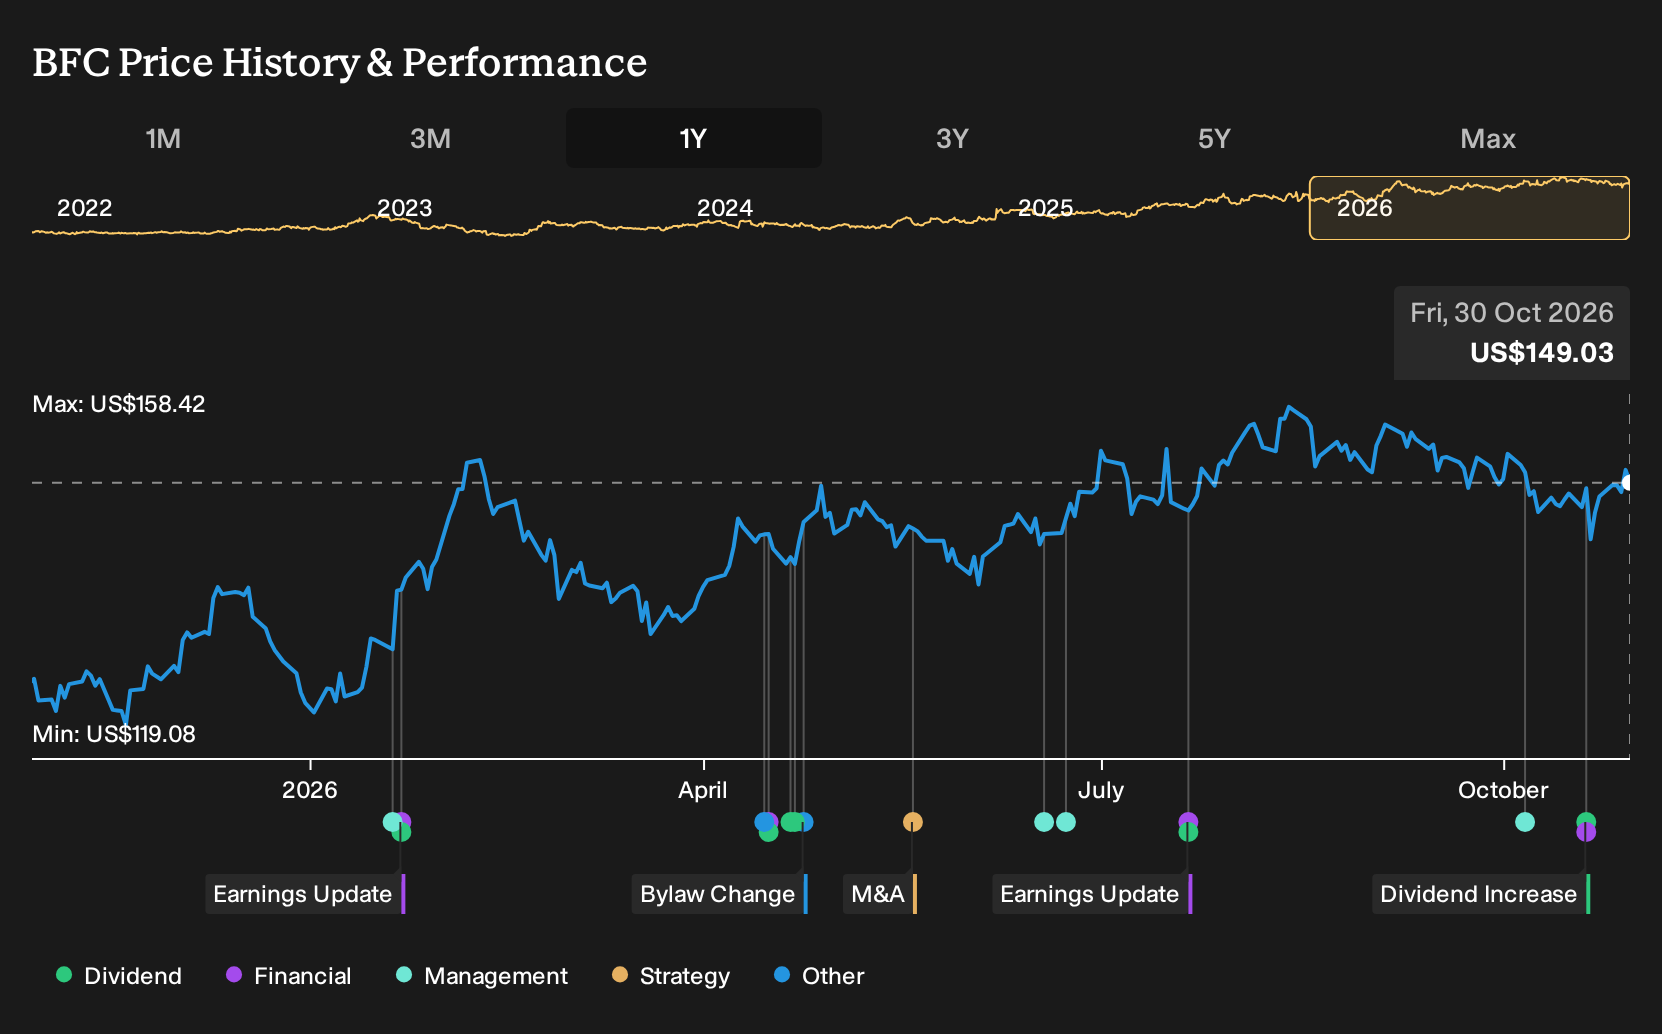
- Bank First Corporation reported higher third quarter and nine month earnings compared to a year earlier and announced a quarterly dividend of $0.65 per share, payable on January 6, 2027, which the board approved on October 20, 2026.
- The board also detailed progress on the 2026 share repurchase program, with 151,815 shares bought back for $21.5 million, which reduces share count and can concentrate earnings per share for remaining investors.
- Next, the focus will be on how Bank First’s reported earnings profile and dividend policy could shape the broader investment narrative.
Scan beyond Bank First and compare this dividend and buyback story with a curated 5 dividend fortresses that is also leaning into shareholder returns.
What Is Bank First's Investment Narrative?
To own Bank First, you need to believe this regional lender can keep turning a relatively focused Wisconsin footprint into consistent earnings and disciplined capital use. The third quarter results show higher net interest income and net income year on year, along with basic EPS of US$2.15 for the quarter and US$6.14 for the first nine months. That profitability supports a higher quarterly dividend of US$0.65 per share and a completed US$21.5m buyback, which together signal that management is comfortable returning cash rather than hoarding it.
The short term swing factor is whether Bank First can sustain this earnings profile while running with what is described as low Return on Equity and a P/E of 19.1x, above both its estimated fair P/E and the US banks average. A richer valuation puts more pressure on execution, loan quality and deposit costs, especially as net profit margins have narrowed compared with last year. The dividend increase and buyback completion fit a shareholder friendly story, but they also raise the bar for what you should expect from future performance.
That said, one underappreciated wrinkle only really comes into focus when you look at ...
There's only one way to know the right time to buy, sell or hold Bank First. Head to Simply Wall St's company report for the latest analysis of Bank First's Fair Value.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span from about US$143.54 to more than US$7.8m, which shows how far opinions on Bank First can stretch when private investors build their own models. Layer that against the recent dividend lift and completed buyback, and you get fresh catalysts that many will reassess.
Explore 2 other Bank First fair value estimates, including one that suggests it could be worth just $143.54.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank First research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank First. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank First's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank First?
Once you have formed a view on Bank First, it can help to set that opinion against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If capital preservation is top of mind, focus on resilient balance sheets and steady fundamentals through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, line up candidates that look mispriced on fundamentals using the 29 high quality undervalued stocks.
- If income is a priority, build a shortlist of companies with substantial yields by starting with the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com