


Unicharm (TSE:8113) Looks Fairly Valued As East Africa Expansion Resets Distribution
Unicharm (TSE:8113) has kicked off full-scale operations of its East African joint venture with Toyota Tsusho, shifting to a direct sales model in Kenya that investors may view as a meaningful distribution reset.
Unicharm’s move in East Africa lands at a time when momentum in the shares has been rebuilding, with the 1 month share price return of 7.88% and year to date share price return of 12.87%, in contrast to a 3 year total shareholder return that is down 39.64%.
Scan for other consumer-focused stocks pursuing similar regional expansion and social impact angles by reviewing the hand-picked 71 high quality undiscovered gems that may be flying under most investors' radar.
The East Africa push raises a sharper issue for Unicharm. Are investors re-rating the stock because of a changing mood after a weak three-year run, or because of what the current valuation says about the underlying business today?
Preferred P/E of 27x: Is it justified for Unicharm?
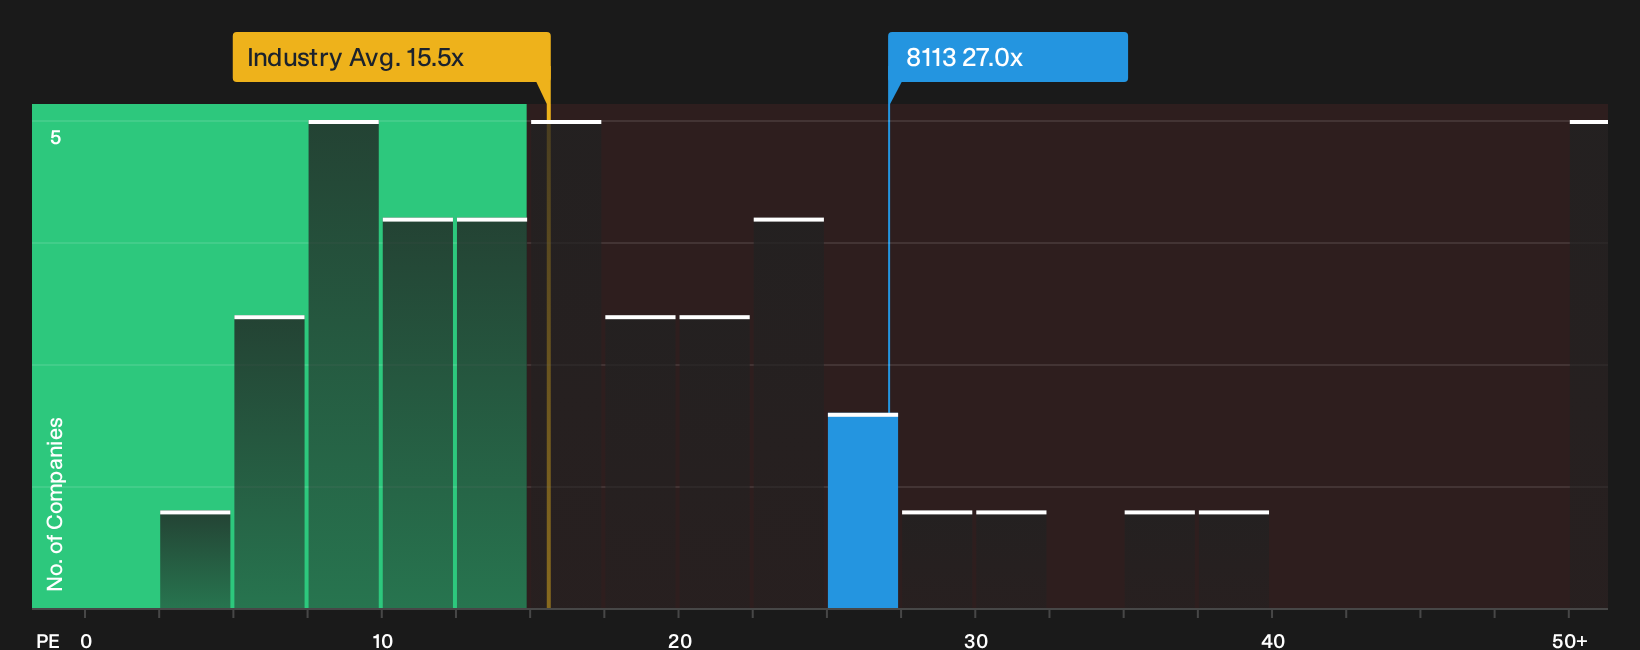
On simple earnings terms, Unicharm trades on a P/E of 27x, which puts a clear premium on the current ¥1,012 share price compared with peers. That premium matters for anyone asking whether the recent share price recovery is being driven by sentiment or by what buyers are willing to pay for each yen of profit.
The P/E ratio tells you how much investors pay today for the company’s earnings. For a consumer products group like Unicharm, where brands, repeat purchases, and cash generation tend to be central, P/E is often the first shortcut investors use to weigh up what the market is implying about future profitability.
Relative to direct peers, that 27x figure screens as expensive. Management is forecast to grow earnings by 11.6% per year, which is ahead of the wider JP market forecast of 9.6% annual profit growth, and the stock is also described as trading at good value relative to an estimated “fair” P/E of 31.3x. That fair ratio points to a level the market could move towards if those earnings forecasts and cash flow expectations hold up, even though the current multiple is high against both the Japan Household Products industry on 15.6x and the narrower peer group on 20.9x.
Explore the SWS fair ratio for Unicharm.
Result: Preferred multiple of Price-to-Earnings of 27x (ABOUT RIGHT)
Still, the premium on Unicharm looks vulnerable if East African execution disappoints or if consumer demand softens in core markets such as Japan and broader Asia.
Find out about the key risks to this Unicharm narrative.
Another View on Unicharm’s Valuation
The P/E story says Unicharm looks expensive next to the Japan Household Products industry on 15.6x and peers on 20.9x, even if the fair ratio of 31.3x hints at some headroom. That gap leaves investors weighing whether they are paying up for quality or simply taking on additional valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unicharm for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
High premium, fair ratio, East Africa rebuild: it all adds up to a mixed picture that only really settles once you test the numbers yourself. If you want a quick way to see what the market is optimistic about, start with the 3 key rewards
Looking for more Unicharm sized investment ideas?
If you stop at Unicharm, you risk missing other opportunities that fit your style. Use screeners to quickly surface ideas that match your priorities.
- Target potential mispricing by running through the 15 high quality undervalued stocks that combine earnings power with balance sheet strength.
- Prioritise resilience by scanning the 24 resilient stocks with low risk scores that show steadier risk scores and fewer financial red flags.
- Hunt for early movers by reviewing the 1 elite penny stocks with strong financials that already score well on key fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com