


How Royalty Revenue Growth At Ligand Pharmaceuticals (LGND) Has Changed Its Investment Story
- Ligand Pharmaceuticals reported third quarter 2026 results with revenue of US$78.75 million and a net loss of US$28.49 million, while reaffirming full year revenue guidance of US$270 million to US$310 million and increasing adjusted diluted EPS expectations.
- The latest update highlights 51% royalty revenue growth supported by the XOMA portfolio, Filspari and Ohtuvayre, alongside new royalty deals that expand Ligand Pharmaceuticals' portfolio of more than 200 assets and reinforce its royalty aggregation focus.
- We will now look at how Ligand Pharmaceuticals' stronger royalty engine and higher adjusted EPS guidance may influence the longer term investment narrative.
Ligand Pharmaceuticals Investment Narrative Recap
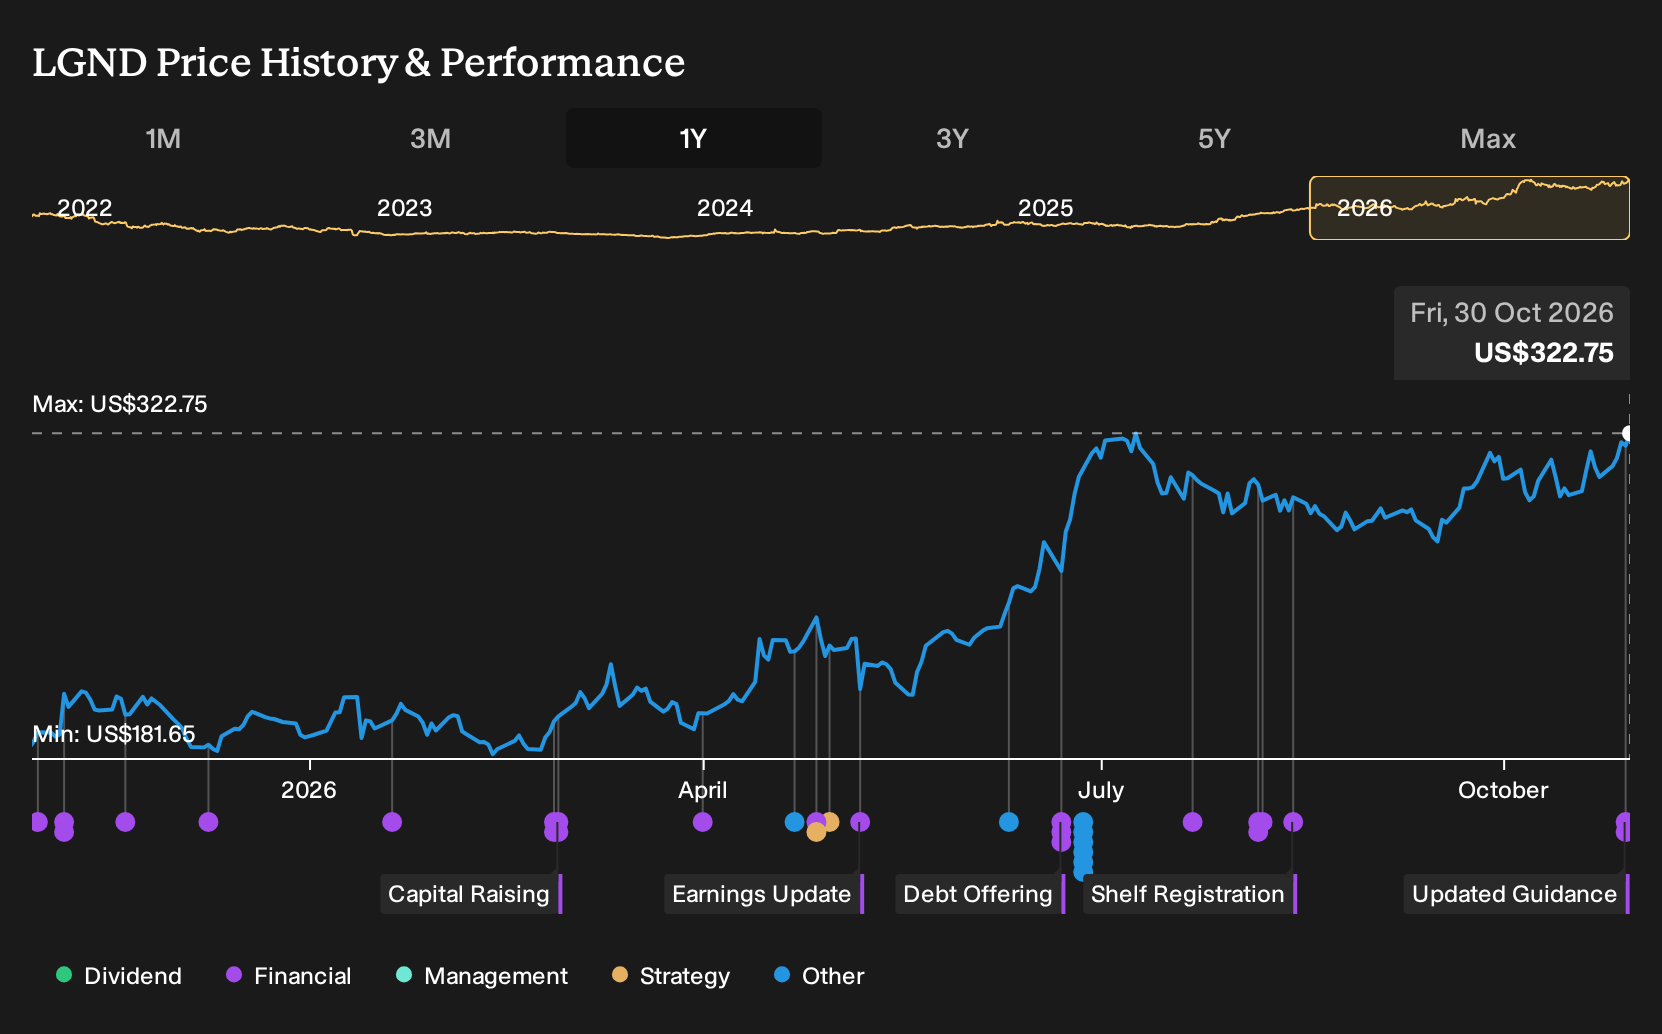
Owning Ligand Pharmaceuticals is essentially a bet that its royalty aggregation model can turn a broad portfolio of partnered drugs into durable, high margin cash flow, even as individual assets rise and fall. The Q3 2026 print complicates that story in the near term. Revenue for the quarter was US$78.75 million and the business reported a net loss of US$28.49 million, so execution needs watching more closely.
The near term swing factor remains how quickly key contributors like Filspari, Ohtuvayre and the XOMA assets translate into consistent royalty income and operating leverage. The biggest risk is still concentration in a handful of major royalty streams combined with drug pricing and payer pressure. The latest results do not remove that risk, but the 51% royalty growth narrative suggests the core engine is still developing.
The most relevant update here is management reaffirming full year 2026 revenue guidance of US$270 million to US$310 million while lifting adjusted diluted EPS guidance to US$9.50 to US$9.75. That mix indicates the focus is squarely on cost discipline and business mix rather than simply chasing more top line. For you as a shareholder, that makes margins and cash conversion key items to track.
In the context of catalysts, this tighter EPS outlook sits alongside a portfolio of more than 200 royalty assets and up to seven pivotal readouts expected in 2027. Execution risk is twofold. Partners need to hit clinical and commercial milestones on drugs like Filspari and volixibat, and Ligand Pharmaceuticals needs to keep deploying its roughly US$750 million of capital into royalty deals that translate into future cash flow rather than just an increased headline count of assets.
Ligand Pharmaceuticals' narrative projects US$482.8 million in revenue and US$275.3 million in earnings by 2029. This projection assumes 18.4% yearly revenue growth and an earnings increase of about US$78.1 million from US$197.2 million today.
Uncover why Ligand Pharmaceuticals' fair value indicates a 7% potential upside to its current price before the discount starts to close.
Exploring Other Perspectives
One alternate view puts more weight on the risk that Ligand Pharmaceuticals overpays for new royalty deals. The most cautious analysts were penciling in revenue of about US$424.0 million and earnings near US$255.2 million by 2029, with a lower P/E of 27.8x. This presents a more conservative story that this new earnings report could easily reshape.
Explore another Ligand Pharmaceuticals fair value estimate, including one that suggests it could be worth just $344.25.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ligand Pharmaceuticals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ligand Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ligand Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ligand Pharmaceuticals?
If the Ligand Pharmaceuticals story has you thinking about position sizing and portfolio balance, it can help to line it up against a wider set of opportunities that share similar traits but come with different risk and return profiles.
- For investors who want potential mispricing alongside quality fundamentals, filter for companies with the 29 high quality undervalued stocks and compare how their cash flows and balance sheets stack up against Ligand Pharmaceuticals.
- If capital preservation matters as much as upside, narrow your watchlist to businesses on the 30 resilient stocks with low risk scores and see which ones offer steadier profiles than a royalty aggregator.
- When you want robust finances to anchor the higher risk parts of your portfolio, build a shortlist using the list of solid balance sheet and fundamentals (25 results) so you can weigh Ligand Pharmaceuticals against companies with stronger cushions on the liability side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com