


Prada (SEHK:1913) Revenue Jump Puts Its Undervalued Narrative To The Test
Prada (SEHK:1913) caught investor attention after reporting unaudited net revenues of €4,541 million for the nine months to 30 September 2026. This represents a 14.5% year-on-year increase, with 3.5% organic growth.
Against that backdrop, Prada’s share price has reacted positively in the very short term, with a 1-day share price return of 4.79% and a 1-month gain of 6.24%. However, momentum has faded over a longer stretch, with the 90-day share price return down 7.95% and the 1-year total shareholder return down 9.67%.
Compare Prada’s recent revenue momentum with other consumer stocks that also pair brand strength with resilient balance sheets using our hand-picked list of solid balance sheet and fundamentals (203 results)
Short term buyers have already enjoyed a sharp bounce, yet Prada’s longer term returns remain in the red. Is most of the rerating now reflected in the price, or is there still valuation upside left to claim?
Most Popular Narrative: 16% Undervalued
On the most followed narrative, Prada’s HK$47.58 fair value sits above the last close at HK$39.82, which puts the recent rally in context but also leaves a gap that narrative followers are watching closely.
Prada’s ongoing investment in new product collections, a wider price ladder and higher touch services such as make to measure and bespoke in flagship stores remains focused on drawing more spending from affluent core clients and aspirational shoppers. This approach can support long term revenue and gross margin growth if adoption continues to build.
See why 7 investors see Prada as 16% undervalued.
Result: Fair Value of HK$47.58 (UNDERVALUED)
Still, Prada’s heavier reliance on top spenders and regions like Asia and the Americas can cut both ways if tourism slows or regional demand softens.
Find out about the key risks to this Prada narrative.
Another View: Prada On Earnings Multiples
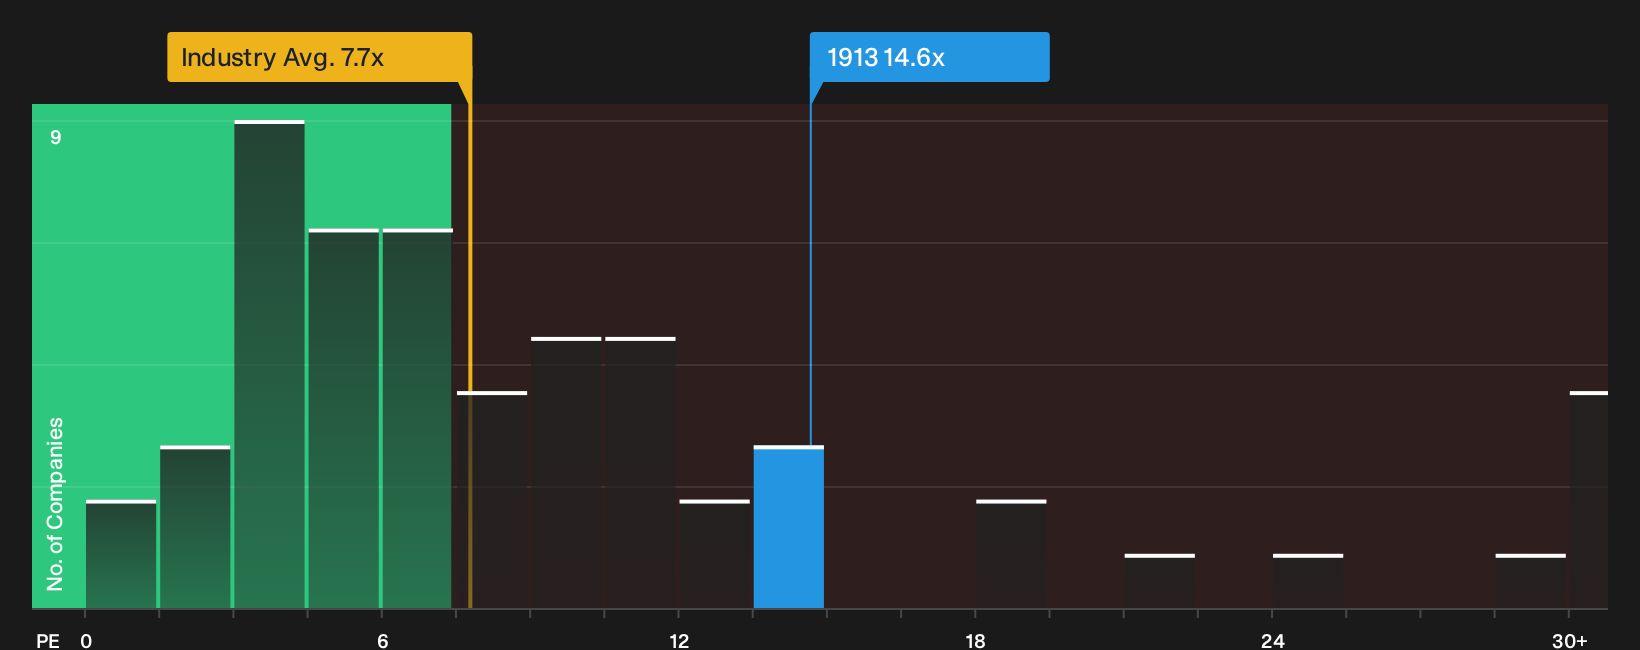
The story looks different once Prada is viewed through its P/E. The shares trade on 14.6x earnings, which is much higher than both the Hong Kong Luxury industry average of 7.7x and peers at 9.5x. The fair ratio also sits at 9.5x, suggesting limited room for error if growth underdelivers.
That kind of premium can quickly compress if sentiment cools or earnings forecasts change. It is therefore worth asking whether the quality of Prada’s franchise justifies paying well above both rivals and the fair ratio, or if patience is the better option while expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across valuation and sentiment can be confusing, especially when Prada is pulling strong opinions in both directions. To respond effectively, review the full set of numbers and narratives promptly, and weigh both the upside and downside using our breakdown of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Prada?
If Prada has sharpened your focus, now is the moment to widen your watchlist and line up a few high conviction candidates before the next move catches you off guard.
- Target resilient balance sheets and steady fundamentals by zeroing in on our list of solid balance sheet and fundamentals (203 results) that keeps financial strength front and center.
- Hunt for quality at a discount by scanning the 199 high quality undervalued stocks that filters for robust businesses trading below their estimated worth.
- Strengthen your income stream by reviewing the 221 dividend fortresses that focuses on higher yielding companies with the potential to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com