


Does Weaker Quarterly Earnings Change The Bull Case For M/I Homes (MHO)?
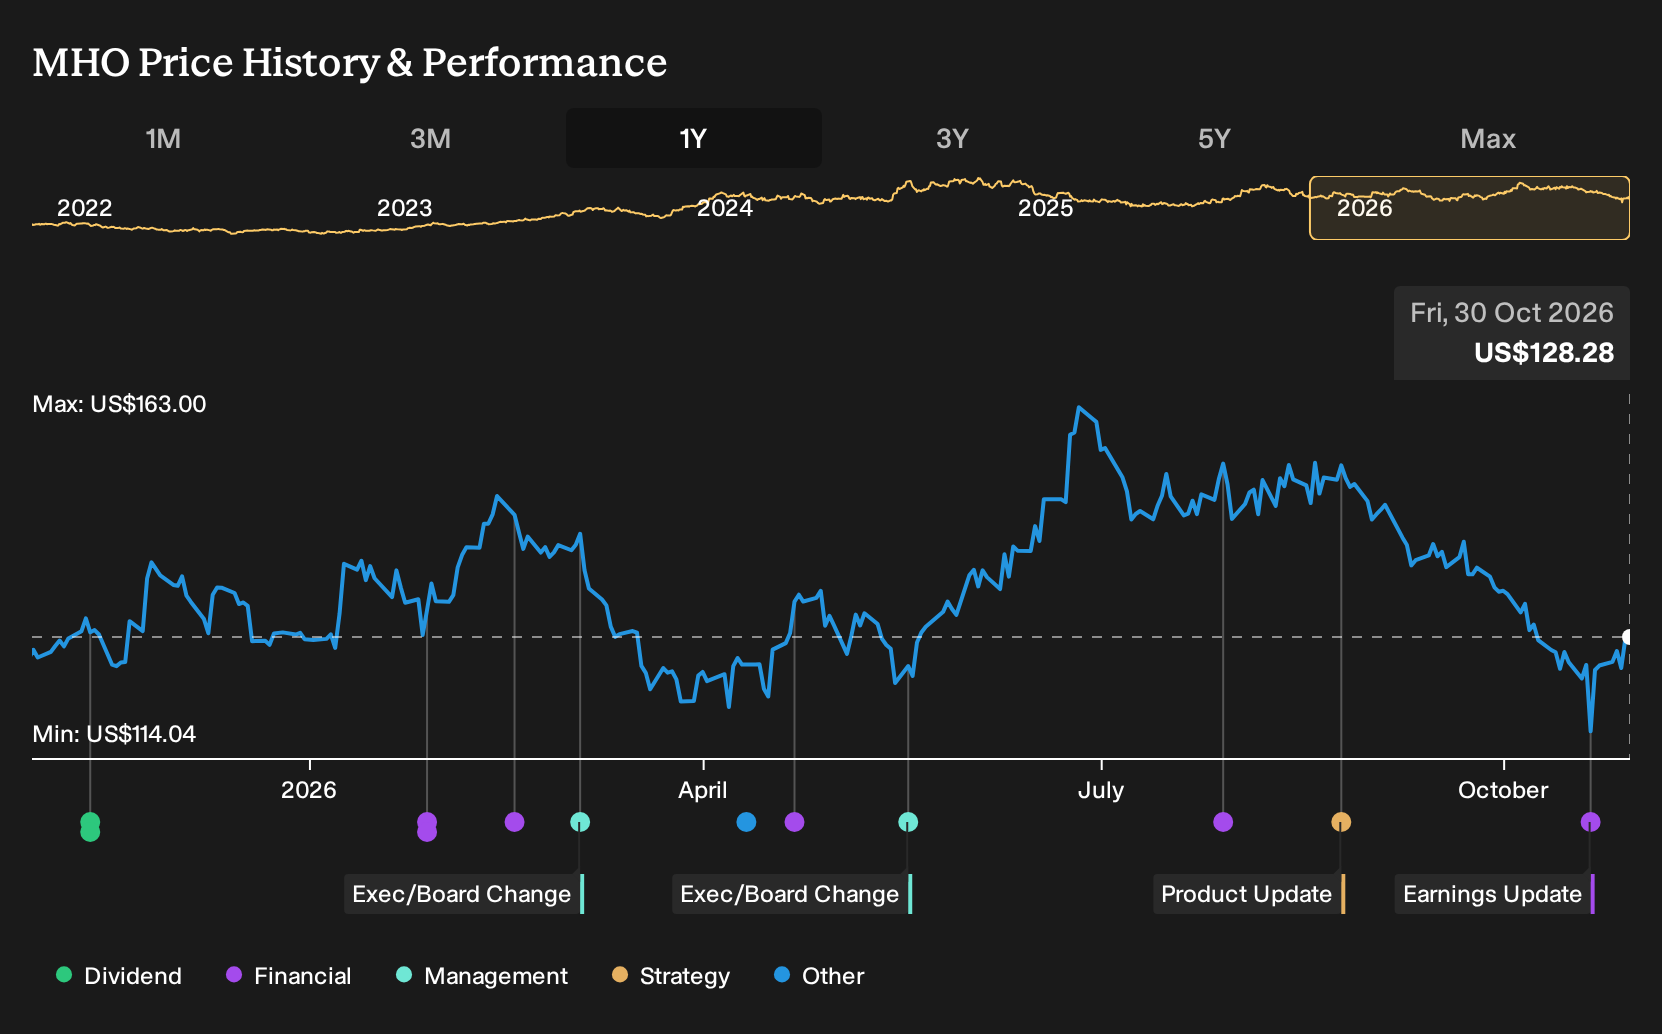
- M/I Homes reported third quarter 2026 revenue of US$1,076.07 million and net income of US$66.55 million, both below the prior year, while nine month earnings and earnings per share from continuing operations also trailed the same period in 2025.
- The business completed a sizeable share repurchase, buying back 1.34% of its stock in the latest quarter and 5.1% since November 2025 for US$179.7 million. This reduces the share count at the same time as earnings per share are under pressure.
- We will now look at how M/I Homes' investment narrative compares with weaker quarterly profitability and the ongoing share repurchase program.
M/I Homes Investment Narrative Recap
M/I Homes still asks you to believe in a simple idea. The builder can keep turning its large lot bank, wider community footprint and in house mortgage arm into steady contracts even while incentives and lot costs bite into profitability. The latest quarter, with softer earnings and margins, keeps the near term focus firmly on execution rather than expansion.
Right now, the key short term swing factor is how effectively M/I Homes uses mortgage rate buydowns and pricing to support orders without further squeezing margins. The biggest risk is that higher finished lot costs and expensive incentives stick, while demand cools. The latest earnings simply make that trade off more visible, not fundamentally different.
The most relevant update here is the completed repurchase of 1,308,756 shares, or 5.1% of the company, for US$179.7 million since November 2025. With earnings under pressure, that smaller share count increases the importance of each dollar of profit, because per share figures become more sensitive to any change in margins or volumes.
For you as an investor, that buyback sits alongside a balance sheet described as strong and a P/E below both peers and an estimated fair multiple. It puts more weight on upcoming catalysts like community openings and the performance of the Smart Series and move up communities. Execution on orders, pricing and mortgage incentives now flows more directly into per share outcomes, while any further margin compression cuts the other way just as quickly.
M/I Homes' current analyst narrative points to forecast revenue of US$4.4b and projected earnings of US$309.4 million by 2029, based on an assumed 1.6% yearly revenue growth rate and a move from US$277.4 million in earnings today to that 2029 consensus level, which is an increase of about US$32 million.
Discover why M/I Homes' fair value indicates a 22% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate view puts less weight on community growth and more on earnings pressure. The most bearish analysts were already penciling in roughly flat revenue around US$4.3b by 2029 and earnings of about US$270.4 million. That is a smaller profit pool than the consensus story. After this M/I Homes quarter and buyback update, those pre-existing numbers may look either conservative or in need of a rethink. You can use that gap between US$270.4 million and the US$309.4 million consensus earnings view as a reminder that opinions differ widely and are worth comparing side by side.
Explore 2 other M/I Homes fair value estimates, including one that suggests it could be worth just $156.67!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your M/I Homes research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for M/I Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M/I Homes' overall financial health at a glance.
Looking For More Investment Ideas Beyond M/I Homes?
If you want to stress test your thesis on M/I Homes and compare it with other potential opportunities, the Simply Wall St Screener can help you quickly scan for businesses that fit a similar risk and reward profile or take you in a completely different direction.
- Prefer to focus on resilient balance sheets and steady fundamentals first and the story second? Start with this list of solid balance sheet and fundamentals (25 results), which emphasises financial strength before anything else.
- If your priority is limiting downside and sleeping easier through volatility, you can filter for companies with lower risk profiles using the 30 resilient stocks with low risk scores tailored to more cautious investors.
- For readers looking for underappreciated opportunities with room for the thesis to mature over time, you can scan the 18 high quality undiscovered gems and see which smaller stocks share traits you like in M/I Homes.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com