


Tutor Perini (TPC) Draws A Fresh Valuation Look Following Stronger Cash Flow And Returns
Tutor Perini (TPC) is back in focus after fresh data highlighted 11.1% annual revenue growth, stronger returns on capital, and a wider free cash flow margin. These developments are feeding into increasingly positive investor sentiment around the construction contractor.
The share price reaction has been choppy, with Tutor Perini falling 3.3% over the last day and slipping over the past month, even though the year-to-date share price return is 15.1% and the one-year total shareholder return is 18.9%. This hints at momentum that has cooled recently following a very large three-year total shareholder return and strong five-year gains.
Scan how Tutor Perini's latest momentum compares with 29 high quality undervalued stocks, which also pair growing cash generation with disciplined balance sheets.
Tutor Perini now trades at a sizeable discount to both analyst targets and intrinsic value estimates after that recent pullback. Is the market being prudently skeptical, or is it mispricing the improving cash and return profile?
Most Popular Narrative: 30% Undervalued
Against a last close of $79.82, the most followed narrative for Tutor Perini points to a fair value of $113.25, with that view built on a large backlog, earnings growth forecasts, and a higher discount rate of 9.12% applied to those cash flows.
Record backlog growth, now at an all-time high of $21.1 billion (up 102% YoY), provides strong visibility and multi-year revenue predictability, as a series of major projects ramp up over the next several years.
Sustained federal and state infrastructure funding, particularly for large-scale transit and civil projects (Midtown Bus Terminal, Sepulveda Transit Corridor, Indo-Pacific Defense contracts), is fueling robust project pipeline expansion, favorably impacting both future revenue and long-term earnings growth.
See why 22 investors see Tutor Perini as 30% undervalued.
Result: Fair Value of $113.25 (UNDERVALUED)
Still, the bullish Tutor Perini story leans heavily on mega public projects, where delays, disputes or cost overruns could quickly pressure margins and unsettle that valuation case.
Find out about the key risks to this Tutor Perini narrative.
Another View: Tutor Perini Through Earnings Multiples
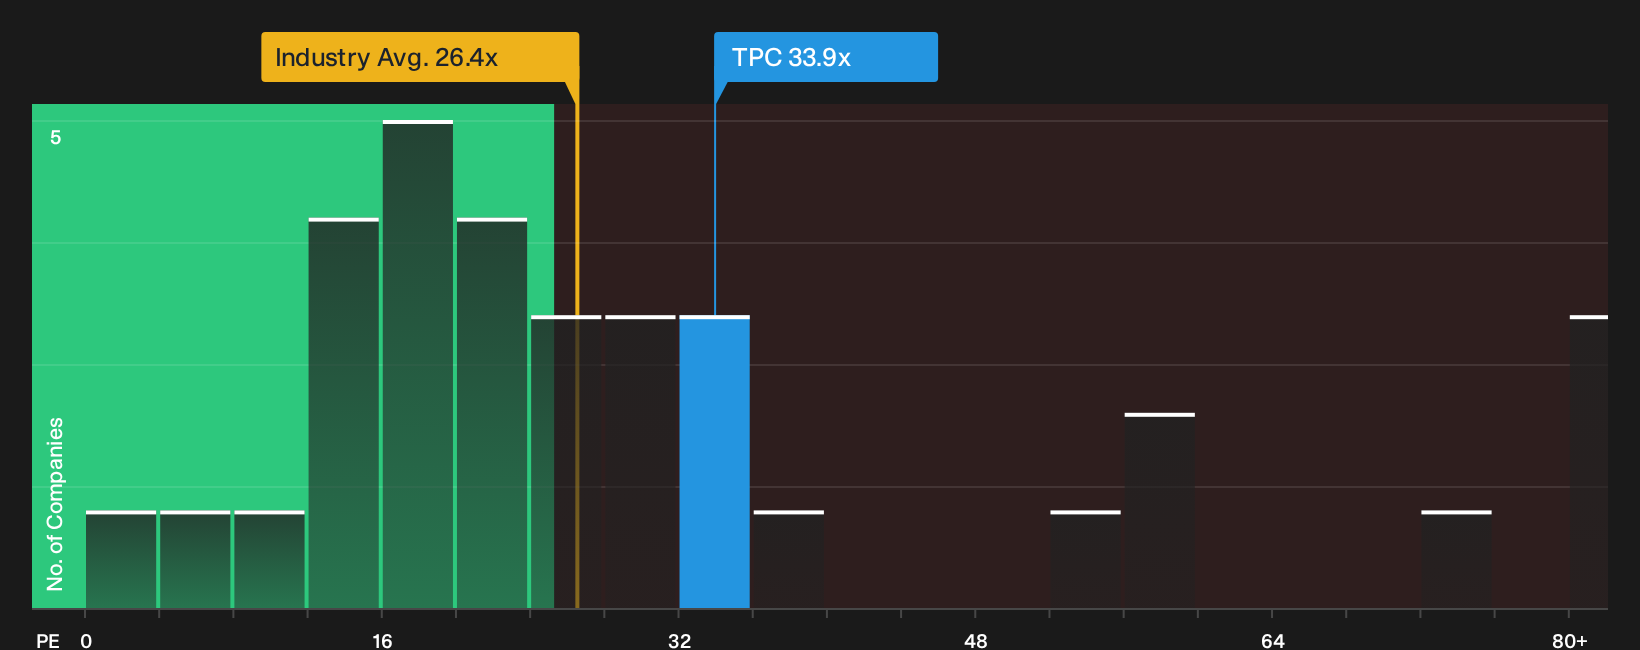
The DCF work paints Tutor Perini as undervalued, yet the market is still paying a rich headline P/E of 33.9x, compared with 26.4x for the wider US Construction group and 25.5x for closer peers. The fair ratio stands even higher at 50x, which suggests either meaningful upside if earnings forecasts land as expected, or real valuation risk if they do not.
These mixed signals leave a simple question for investors: Is the current P/E a reasonable price for forecast earnings growth, or is the market already paying upfront for a future that might prove harder to deliver than models suggest? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Tutor Perini has you on the fence, move quickly to check the underlying data yourself and pressure test every assumption. To weigh both sides of the story in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tutor Perini?
If Tutor Perini has sharpened your focus on valuation and quality, you can broaden your watchlist now by using a few targeted screeners that surface very different types of opportunities.
- Target resilient cash generators by reviewing companies with a list of solid balance sheet and fundamentals (25 results) that can better withstand business setbacks and funding shocks.
- Hunt for potential mispricings by scanning a curated set of 29 high quality undervalued stocks where fundamentals and current prices appear out of sync.
- Spot early-stage potential by filtering for 9 elite penny stocks with strong financials that already show improving financial quality rather than just low share prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com