


Should Lowered Earnings Estimates Require Action From Molson Coors Stock Investors?
- The Grand Slam of Curling announced Molson Coors Beverage as presenting partner for its 2026 season, with in-venue, broadcast, and social content integration beginning at the Masters event in Medicine Hat in early November.
- This deeper presence in a core Canadian sport highlights Molson Coors Beverage’s focus on brand engagement and community connection at a time when analysts expect pressure on near term earnings and revenue.
- This article will examine how Molson Coors Beverage’s investment narrative is affected by earnings concerns alongside this expanded Grand Slam of Curling partnership.
See how Molson Coors Beverage compares with other consumer stocks facing earnings pressure using a curated list of 29 high quality undervalued stocks that combine solid fundamentals with potential upside.
Molson Coors Beverage Investment Narrative Recap
To own Molson Coors Beverage, you need to believe the business can shift its mix toward above premium, beyond beer and non alcoholic products while keeping a grip on costs. Earnings pressure, soft volumes in core beer and elevated input costs have made that a heavy lift. The key near term swing factor remains execution on the US$450m cost savings program and supply chain changes, rather than marketing headlines.
The new curling partnership looks incremental rather than transformational for the operating story. It helps brand relevance in Canada but does not directly change exposure to falling US beer volumes, inflation in aluminum and freight, or competitive discounting in markets like the U.K. The biggest risk is that volumes and costs move in the wrong direction at the same time, which could keep margins weak.
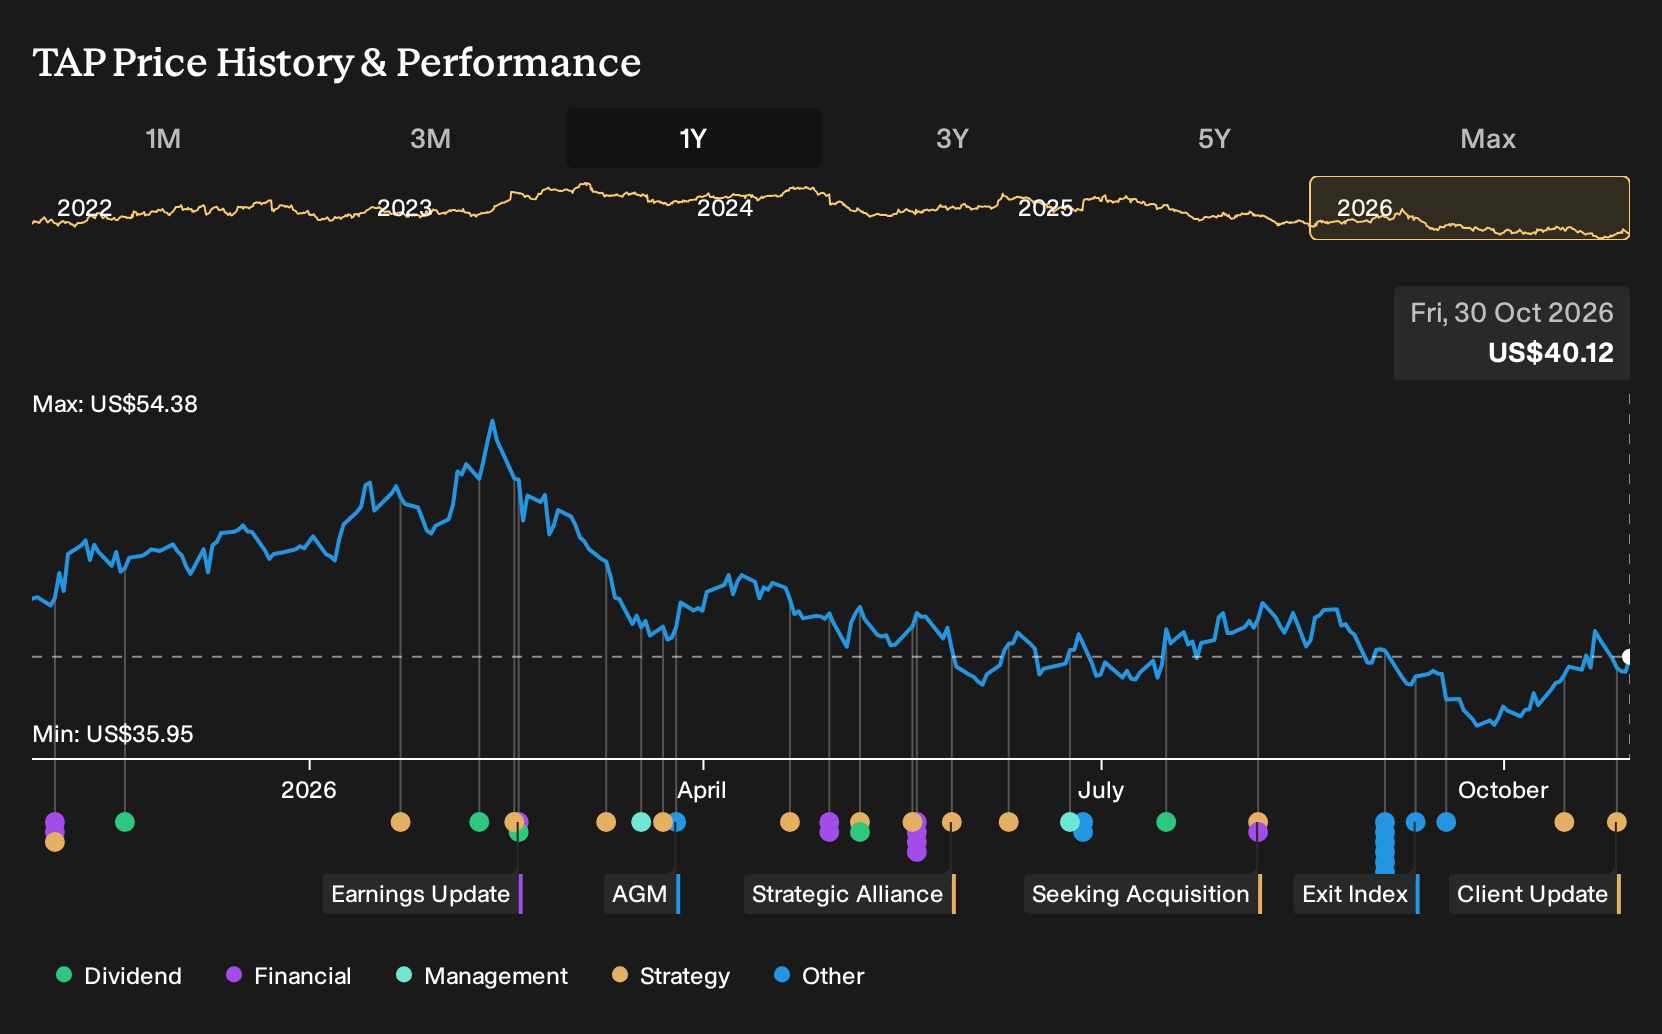
The most relevant update tied to this curling deal is the expectation that Molson Coors Beverage will report lower earnings and revenue for the September 2026 quarter compared with a year earlier. Management is leaning into higher visibility marketing at the same time analysts describe a more cautious earnings backdrop and a Zacks Rank of #4.
For you as a shareholder, the question is whether promotional partnerships like Grand Slam of Curling help support the broader premiumization push enough to offset weak near term financials. The next earnings print on 5 November 2026 is an immediate checkpoint on how pricing, mix and costs are tracking against those expectations and where risks around debt, dividends and profitability might sit.
Molson Coors Beverage's narrative projects revenues of US$11.2b and earnings of US$956.9m by 2029. This reflects relatively flat revenue trends over the period and an earnings increase of about US$3.3b from current earnings of a US$2.3b loss.
Uncover why Molson Coors Beverage's fair value indicates a 9% potential upside to its current price before the window for that discount narrows.
Exploring Other Perspectives
Some of the lowest Molson Coors Beverage forecasts lean hard into curling sponsorship risk rather than brand opportunity. These analysts were penciling in revenue drifting to about US$10.7b and earnings near US$1.0b by 2029 before this deal, which reflects a more cautious story. Use that spread to test your own view and explore how this new partnership might shift expectations.
Explore 4 other Molson Coors Beverage fair value estimates, including one that suggests it could be worth just $43.62.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Molson Coors Beverage research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Molson Coors Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Molson Coors Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Molson Coors Beverage?
If Molson Coors Beverage is only one piece of your watchlist, it makes sense to scan a wider field of opportunities and compare quality, valuation and risk across the market before committing fresh capital.
- For investors focused on stability and lower volatility, review companies flagged as having resilient profiles through the 30 resilient stocks with low risk scores.
- If balance sheet strength matters most to you, filter for businesses with healthier debt and liquidity metrics using the list of solid balance sheet and fundamentals (25 results).
- For those hunting for mispriced opportunities backed by solid fundamentals, start with a curated pool of potential value ideas through the 29 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com