


How New South Korea Bioprocessing Center Will Impact Merck Shares
- Merck KGaA, Darmstadt, Germany, through MilliporeSigma, has opened a €300m Asia Pacific Bioprocessing Production Center in Daejeon, South Korea, supplying cell culture media, process liquids and single use sampling solutions for biologic medicines to regional manufacturers.
- The fossil fuel free facility uses an integrated digital ecosystem for automated data capture and batch traceability, which can influence Merck KGaA’s cost base, supply resilience and execution of its in region for region Life Science strategy in Asia Pacific.
- This development also provides context for Merck KGaA’s investment narrative in relation to its €300m Asia Pacific bioprocessing capacity build out.
Merck KGaA Investment Narrative Recap
To own Merck KGaA, you need to believe the trio of Life Science, Healthcare and Electronics can collectively offset pressure in any one area and still support earnings growth. The Daejeon bioprocessing site fits that view, since it deepens the in region for region supply footprint in Asia Pacific and supports the workflow solutions push in Life Science.
In the short term, the key swing factor is how quickly Life Science and Healthcare execution can offset visible Healthcare patent erosion risks, especially around Mavenclad. The new facility looks helpful but not transformational near term. Currency moves, portfolio changes and any renewed weakness in Electronics delivery systems remain important watchpoints for earnings quality.
The pimicotinib update is the clearest recent Healthcare catalyst to set against the Life Science capacity story. Two year MANEUVER data showed sustained symptom and function improvements in tenosynovial giant cell tumor, with robust response rates and more than half of initially treated patients still on therapy at two years, which supports the rare disease focus.
Pimicotinib is already approved in China and Canada, with the U.S. FDA and other regulators reviewing applications. For an investor, that puts real world execution risk around label decisions, uptake and safety monitoring alongside the opportunity. It also matters for how well newer rare disease assets can help offset expected Mavenclad revenue erosion into 2027.
Merck KGaA's current analyst narrative points to €24.6b in revenue and €3.4b in earnings by 2029, based on expectations of 5.2% yearly revenue growth and an increase of about €1.0b in earnings from €2.4b today.
Uncover why Merck KGaA's fair value signals a valuation gap that appears roughly in line with its current price.
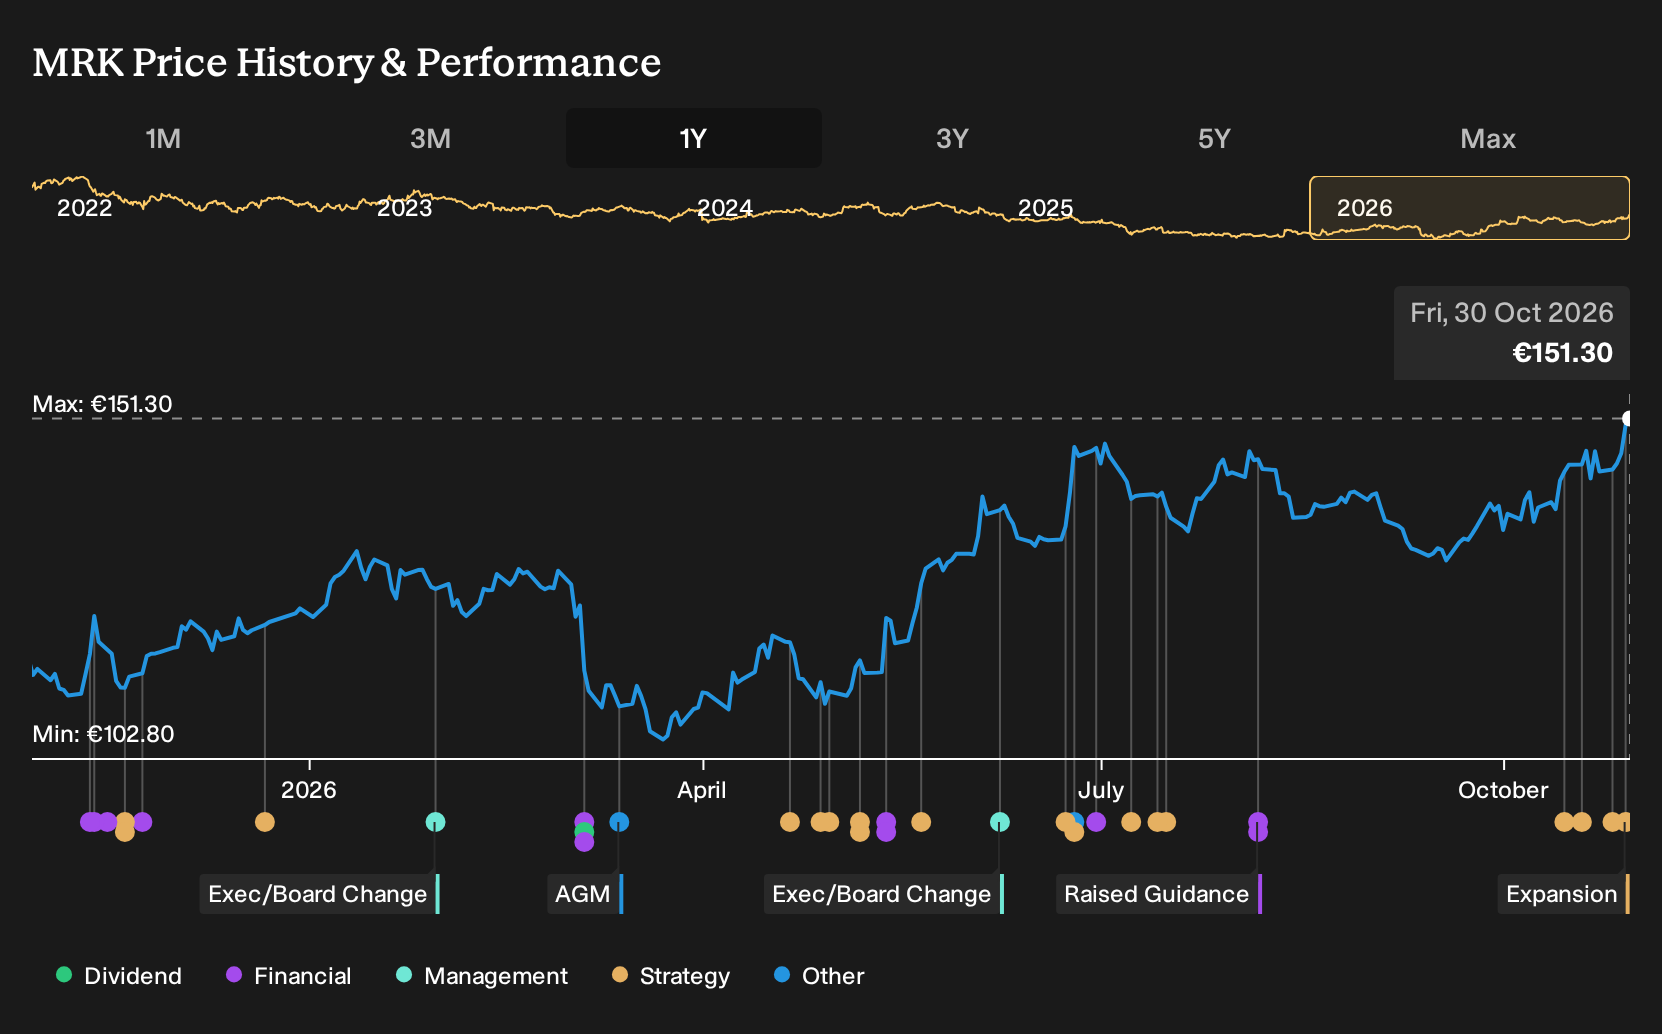
Exploring Other Perspectives
One alternate view puts the Bio-Techne deal, not the Daejeon build out, at the center of the Merck KGaA story. The most optimistic analysts were already penciling in €26.1b of revenue and €3.8b of earnings by 2029 before this capacity news. You can treat Daejeon as a fresh data point and stress test both narratives yourself.
Explore 3 other Merck KGaA fair value estimates, including one that suggests as much as 120% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Merck KGaA research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Merck KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merck KGaA's overall financial health at a glance.
Looking For More Investment Ideas Beyond Merck KGaA?
If you want to pressure test your thesis on Merck KGaA against what else is out there, widen the lens with a few targeted stock lists on the Simply Wall St screener.
- For investors who want quality at a reasonable entry point, scan a curated group of 199 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- If capital preservation sits high on your priority list, sort through a focused set of 218 resilient stocks with low risk scores that aim to keep balance sheets and business models on steadier ground.
- When you are hunting for tomorrow's potential standouts before they are widely followed, work through a hand picked pool of 603 high quality undiscovered gems that combine resilient financials with quieter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com