


Cenergy Holdings And 2 Top Grid Tech Stocks To Watch
Fresh economic data shows US growth running hotter than the Federal Reserve expected, with inflation pressures sticking around. Higher rates can make high-flying tech more volatile, but they also shine a spotlight on real world infrastructure that keeps the lights on. This article walks through three power grid technology stocks from our curated screener that tap into that theme and explains why many investors are watching them closely right now.
The three stocks covered below are just a sample, and the full screen surfaced 36 more power grid technology companies with equally compelling stories that are not included in this article. To identify and analyze the highest conviction opportunities right now, go straight to the Power Grid Technology Stocks screener.
Cenergy Holdings (ENXTBR:CENER)
Cenergy Holdings is one of the clearest grid plays in this list, with its high voltage and submarine cable operations plugging directly into the heavy-duty wiring needed for AI era electricity demand, while a sizeable steel pipes arm keeps the wider industrial portfolio diversified.
Cenergy generates most of its €2.5b cables revenue from high voltage, submarine and land power products that link power plants, offshore wind and grids, alongside a €718 million steel pipes division, and the group is valued at about €4.7b by the market.
"Ongoing global investments in grid modernization and the energy transition (especially upgrades for renewables and offshore wind) are fueling robust demand for Cenergy's high-specification cable projects, as evidenced by a record order backlog and continued strong capacity utilization, which in turn supports multi-year revenue and EBITDA growth."
The real swing factor for Cenergy Holdings is how one subtle shift in project mix filters through to pricing power and long term margins.
That margin mix question is exactly what the full narrative for Cenergy Holdings unpacks, including how project timing, contract structure and execution risk could be masking the real earnings power.

JAPAN MATERIAL (TSE:6055)
Japan Material builds and services the “plumbing” of high tech plants, supplying gas, ultrapure water and vacuum systems that support semiconductor and power equipment manufacturing, alongside a smaller graphics and solar arm. Electronics Related Business generates ¥58,666 million, Graphics Solution Business adds ¥1,821 million and Solar Power Generation contributes ¥205 million. The firm is valued at about ¥208.9 billion.
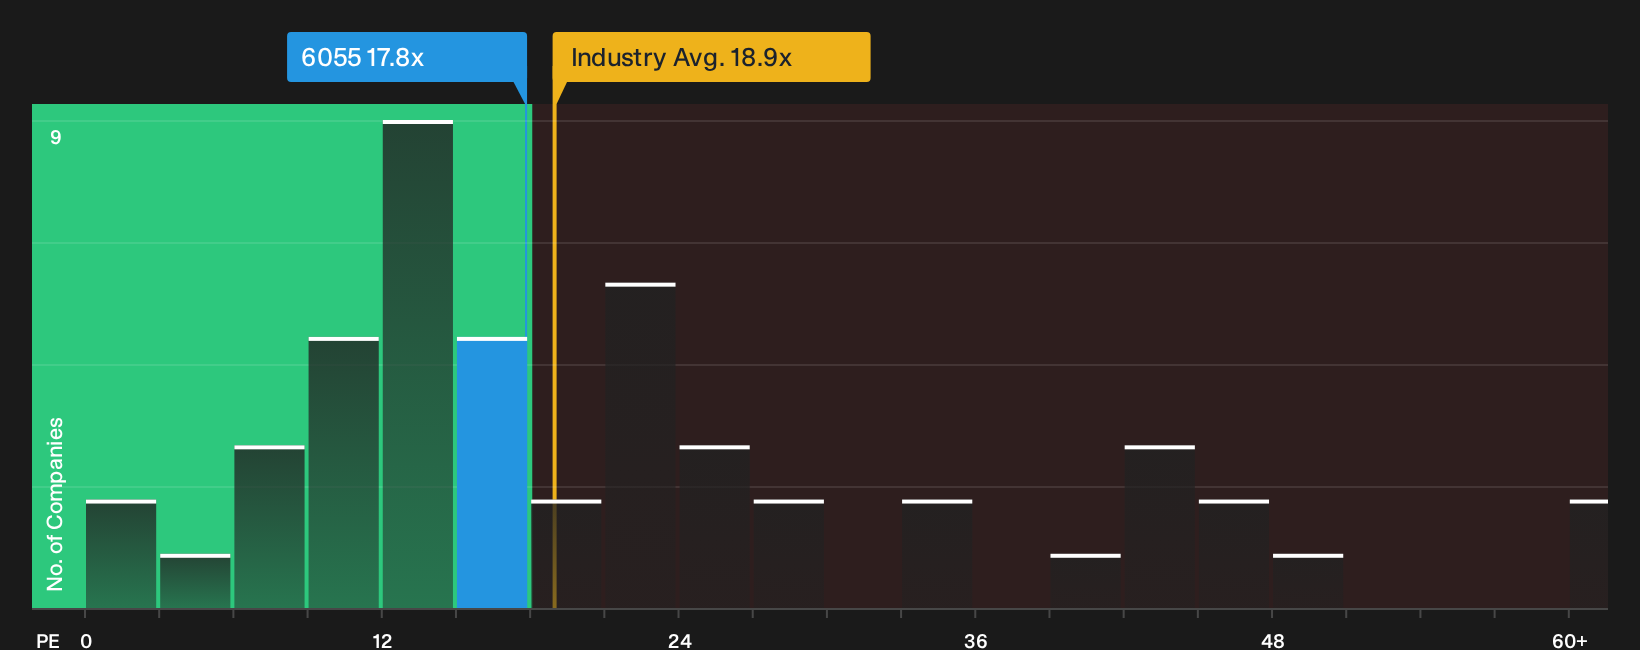
Japan Material provides exposure to the nuts and bolts of high density power manufacturing, from gas lines to ultrapure water that keep chip and power equipment fabs running. Earnings grew 39% last year on a P/E of 17.8x, and margins are near 19%. This makes the reliance on future factory capex cycles and any pressure on pricing power factors worth monitoring.
That factory cycle reliance makes it even more important to see how management is positioned in the 5 key rewards and 1 important warning sign that could reshape Japan Material's earnings path.
GE Vernova (GEV)
GE Vernova is built around big power hardware that keeps electricity flowing, and the Electrification arm plugs directly into the grid theme with equipment, software and services that help move high density power from generation to the data centers and factories that consume it.
GE Vernova generates about US$22.2b from Power, US$8.6b from Wind and US$13.5b from Electrification, with the utility focused grid segment a major contributor alongside generation and renewables, and the business is valued at roughly US$233.8b.
"AI infrastructure spending has dramatically accelerated the need for stable and dispatchable electricity generation, and in Q1 2026 alone GE Vernova reportedly secured $2.4 billion in data-center-related electrification orders. That figure exceeds the total for all of 2025 combined."
What matters next is how one pressure behind those orders reshapes pricing power and long term profitability across GE Vernova's grid portfolio.
That pricing reset is exactly what the full narrative for GE Vernova pulls apart, showing where accelerating AI power demand could decouple GE Vernova's grid profits from old cycle playbooks.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not stay under the radar for long. Once momentum hits, entry points can vanish quickly as prices start breaking away. Scan these ideas before the crowd and get in early.
- Track cash rich companies that still trade like they are being ignored, then zero in on the most promising setups using the 199 high quality undervalued stocks.
- Focus on real revenue instead of hype by filtering for fast growing automation players through the curated 96 robotics and automation stocks.
- Explore potential opportunities in uranium, turbines and grid rebuilds by combing through our hand picked 16 nuclear energy infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com