


Is Aviva (LSE:AV.) Fully Valued Following Morgan Stanley’s Upgrade?
Morgan Stanley’s upgrade of Aviva (LSE:AV.) has pushed the insurer into focus for many investors, as the broker highlighted stronger UK and Ireland earnings potential and improved personal insurance margins.
The recent upgrade fits into a solid run for Aviva, with a 7.37% year to date share price return. The current £7.338 share price sits against a 1 year total shareholder return of 16.79% and a very large 157.69% over five years, which points to momentum that has been building rather than fading.
Scan beyond Aviva and see how other insurers with momentum and earnings potential line up in our hand picked 5 resilient stocks with low risk scores for comparison.
The upgrade has nudged Aviva closer to broker targets, yet a sizeable estimated discount to intrinsic value remains. Is the market rightly cautious about the earnings profile, or mispricing the recent shift in UK and Ireland momentum?
Most Popular Narrative: 6% Overvalued
Against a last close of £7.34, the most followed narrative points to a fair value of about £6.93. This frames Aviva as slightly ahead of where the valuation work lands once future cash flows are discounted at 7.56%.
Accelerating the shift to 'capital-light' businesses (now over 66% of earnings and targeting 70%+ after the Direct Line integration) is driving improved group profit margins, lower capital requirements, and better return on equity, creating a strong forward-looking outlook for net earnings and cash generation.
See why 187 investors see Aviva as 6% overvalued.
Result: Fair Value of £6.93 (OVERVALUED)
Still, heavy reliance on the mature UK market, along with the execution risk around integrating Direct Line, could easily upend the current Aviva valuation story.
Find out about the key risks to this Aviva narrative.
Another View: Cash Flows Paint A Different Picture For Aviva
While the narrative built around analyst targets and earnings multiples frames Aviva as about 6% overvalued, the SWS DCF model points in the opposite direction. On that approach, the current £7.34 share price sits well below an estimated future cash flow value of £13.12, which casts the stock as materially undervalued instead.
The gap between a 39.3x P/E and a DCF value that is almost double today’s price signals very different views of risk and the durability of those cash flows. For you, the key question is which set of assumptions appears more realistic if earnings growth slows, capital needs rise, or both.
Look into how the SWS DCF model arrives at its fair value.
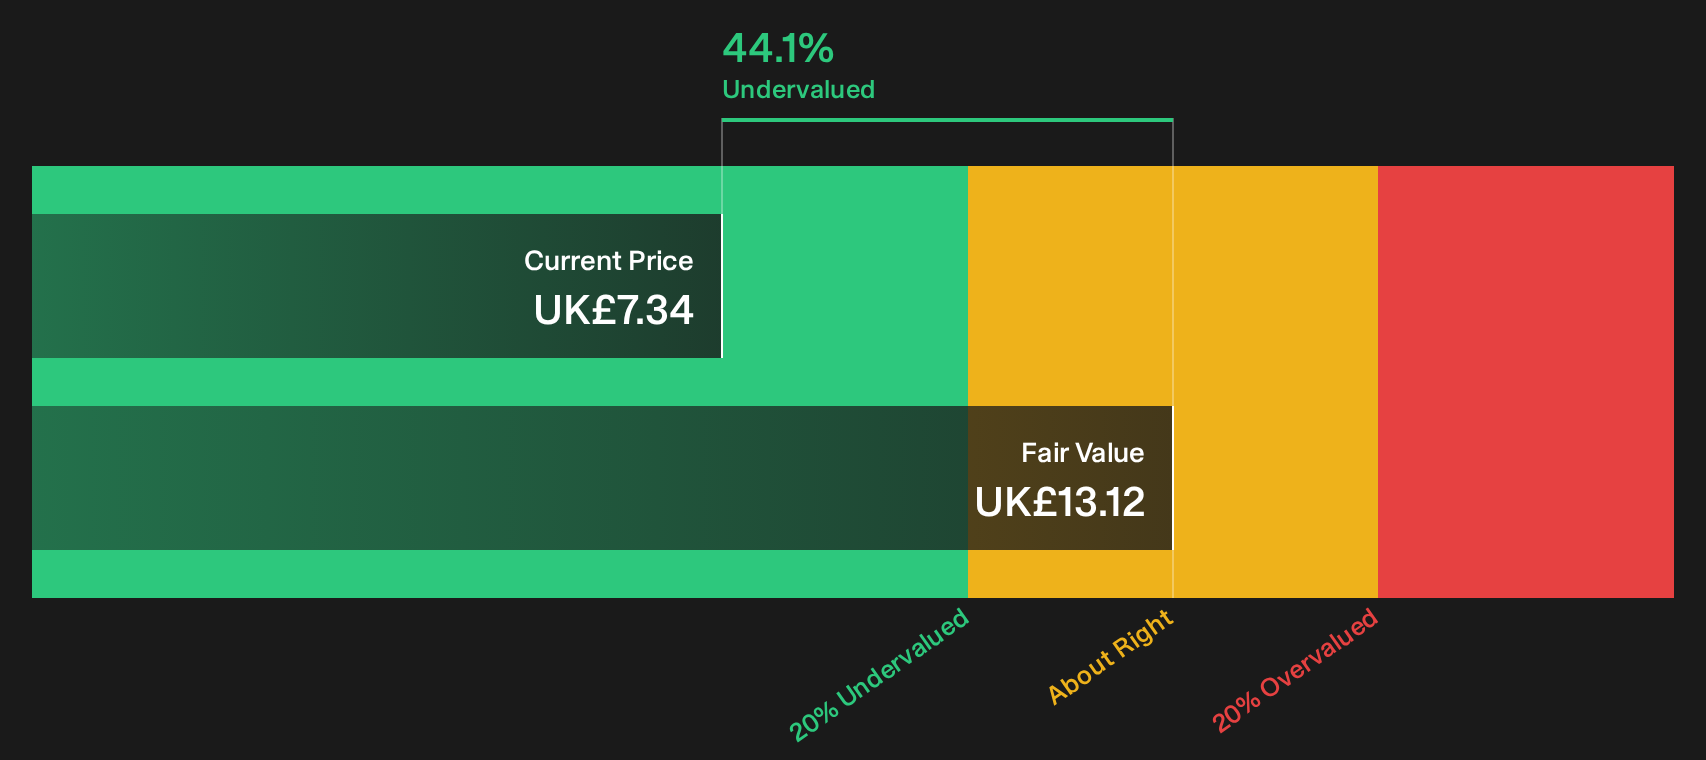
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aviva for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Aviva’s value can be useful. Use that tension as a prompt to move quickly, review the data, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aviva?
If Aviva has sharpened your focus on value and income, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Consider resilient balance sheets and steadier fundamentals with a curated list of solid balance sheet and fundamentals (10 results) that filters for financial strength first.
- Look for potential mispricings by scanning a focused 12 high quality undervalued stocks that pairs quality metrics with pricing signals.
- Explore your income stream by reviewing 5 dividend fortresses that aim to combine higher yields with sturdier business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com