


TTM Technologies (TTMI) Record Quarter And 2027 Growth Outlook Put Valuation Back In Focus
TTM Technologies (TTMI) has just combined record third quarter revenue, earnings, and margins with fresh guidance for late 2026 along with early signals on 2027, giving investors new numbers to weigh.
Despite the strong third quarter update and new buyback plan, TTM Technologies’ share price has been volatile, with a 1-day share price return that fell 5.32% and a 30-day share price return down 32.46%, even as the year-to-date share price return is 17.5% and the 5-year total shareholder return is 480.62%, indicating long-term momentum that has recently cooled.
Compare TTM Technologies’ surge in guidance and fresh buyback with peers by scanning hand picked 18 high quality undiscovered gems that share strong fundamentals but receive far less headline attention.
TTM Technologies now looks like a stronger business on paper, yet the share price has slipped hard in the past month. Is that combination a genuine discount or just a value trap dressed up in fresh guidance?
Most Popular Narrative: 55% Undervalued
On the narrative numbers, TTM Technologies screens as heavily discounted, with a fair value of $185.80 against a last close of $82.97. This puts a lot of weight on whether its AI, data center, and defense roadmap actually converts into cash flows under a 9.17% discount rate.
Large scale AI data center and networking buildouts are feeding into TTM Technologies’ expectation that data center and networking revenue will more than double for full-year 2026 and move toward roughly half of Q3 sales. This can support higher long term revenue and earnings power if that demand persists.
See why 49 investors see TTM Technologies as 55% undervalued.
Result: Fair Value of $185.80 (UNDERVALUED)
Still, the narrative weakens if TTM Technologies’ heavy capital expenditure program leaves capacity underused, or if higher debt and interest costs reduce future earnings power.
Find out about the key risks to this TTM Technologies narrative.
Another View: What Multiples Say About TTM Technologies
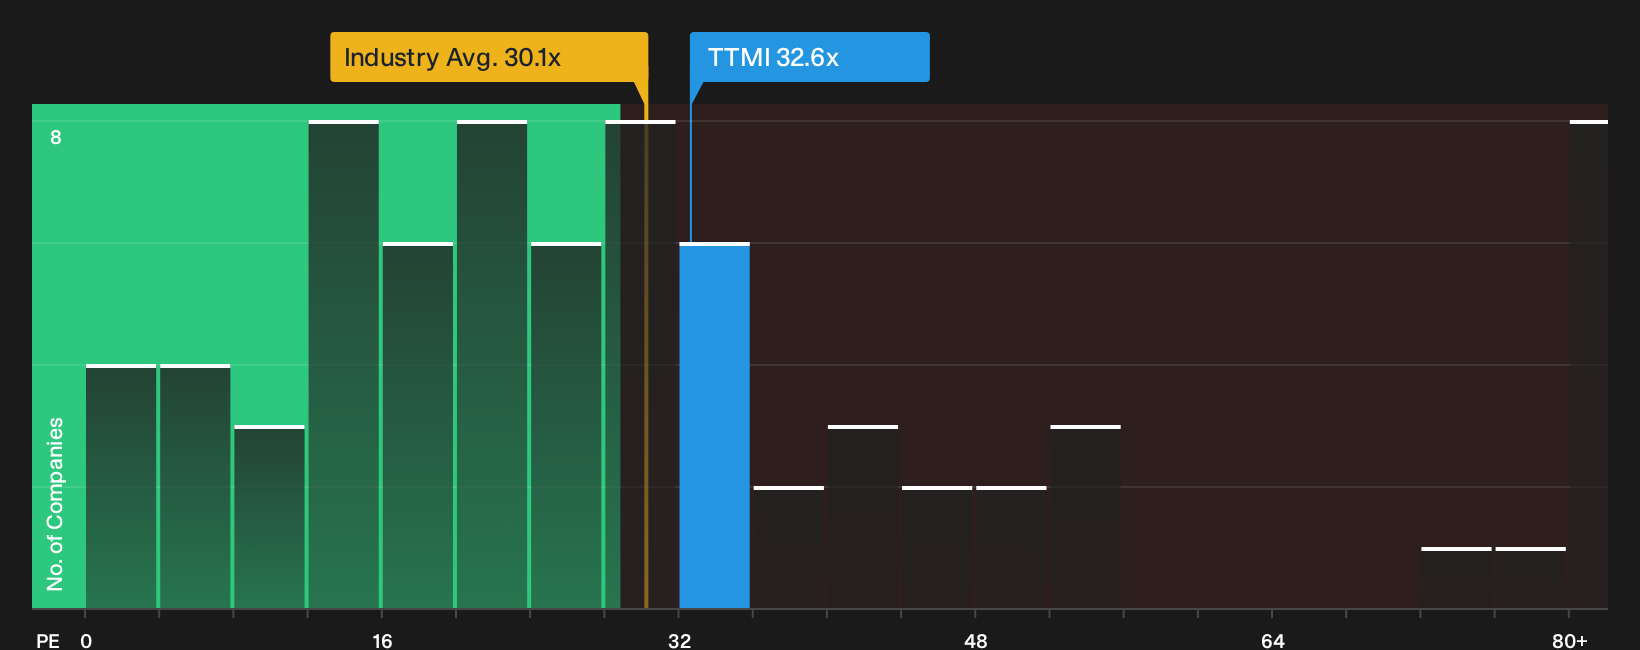
The DCF driven fair value paints TTM Technologies as heavily undervalued, yet the current P/E of 32.6x sits above both peers at 28x and the US Electronic industry on 30.1x. That premium suggests less obvious room for error if the growth story wobbles, so which signal do you trust more?
For a closer look at how this earnings multiple stacks up against what the market could eventually pay, and how that gap might narrow over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on TTM Technologies so far. If you want to move quickly and base your own view on the full picture, start with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond TTM Technologies?
If you only focus on TTM Technologies, you could miss other opportunities that fit your style even better, so stress test your thinking with a few targeted screens.
- Target potential mispricings by scanning a curated 29 high quality undervalued stocks that pair resilient earnings profiles with price tags that still look modest.
- Build income-focused exposure by reviewing a focused group of 5 dividend fortresses that combine higher yields with robust payout histories and balance sheets.
- Dial down portfolio risk by filtering for 30 resilient stocks with low risk scores where financial strength and calmer price moves take priority over headline excitement.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com