


What Banca Monte Dei Paschi Bulls Got Right
If you had put money into Banca Monte dei Paschi di Siena at the end of October 2025, the result a year later might prompt a second look at that call. For Banca Monte dei Paschi di Siena shareholders, the return over the past year was 57.2%, including dividends. Early on, analysts were split between concerns over shrinking margins and optimism around Mediobanca synergies. Which of those competing stories looked more convincing with only that record in front of you?
Banca Monte dei Paschi di Siena has already moved. See which of 199 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Banca Monte dei Paschi di Siena
The shares cost €7.6 at the start of the period, and you were basically choosing between two well framed stories about Banca Monte dei Paschi di Siena.
The bullish view put Fair Value at €9.28, a notional price implied by expectations that revenue could rise about 4.1% a year with profit margins settling near 34.2% and a future P/E of 10.5x.
The bearish camp pointed to a Fair Value of €6.35, arguing that aging demographics, fintech pressure and a 100% payout policy could lift credit risk, trim margins toward 30.9% and justify only a 10.8x P/E.
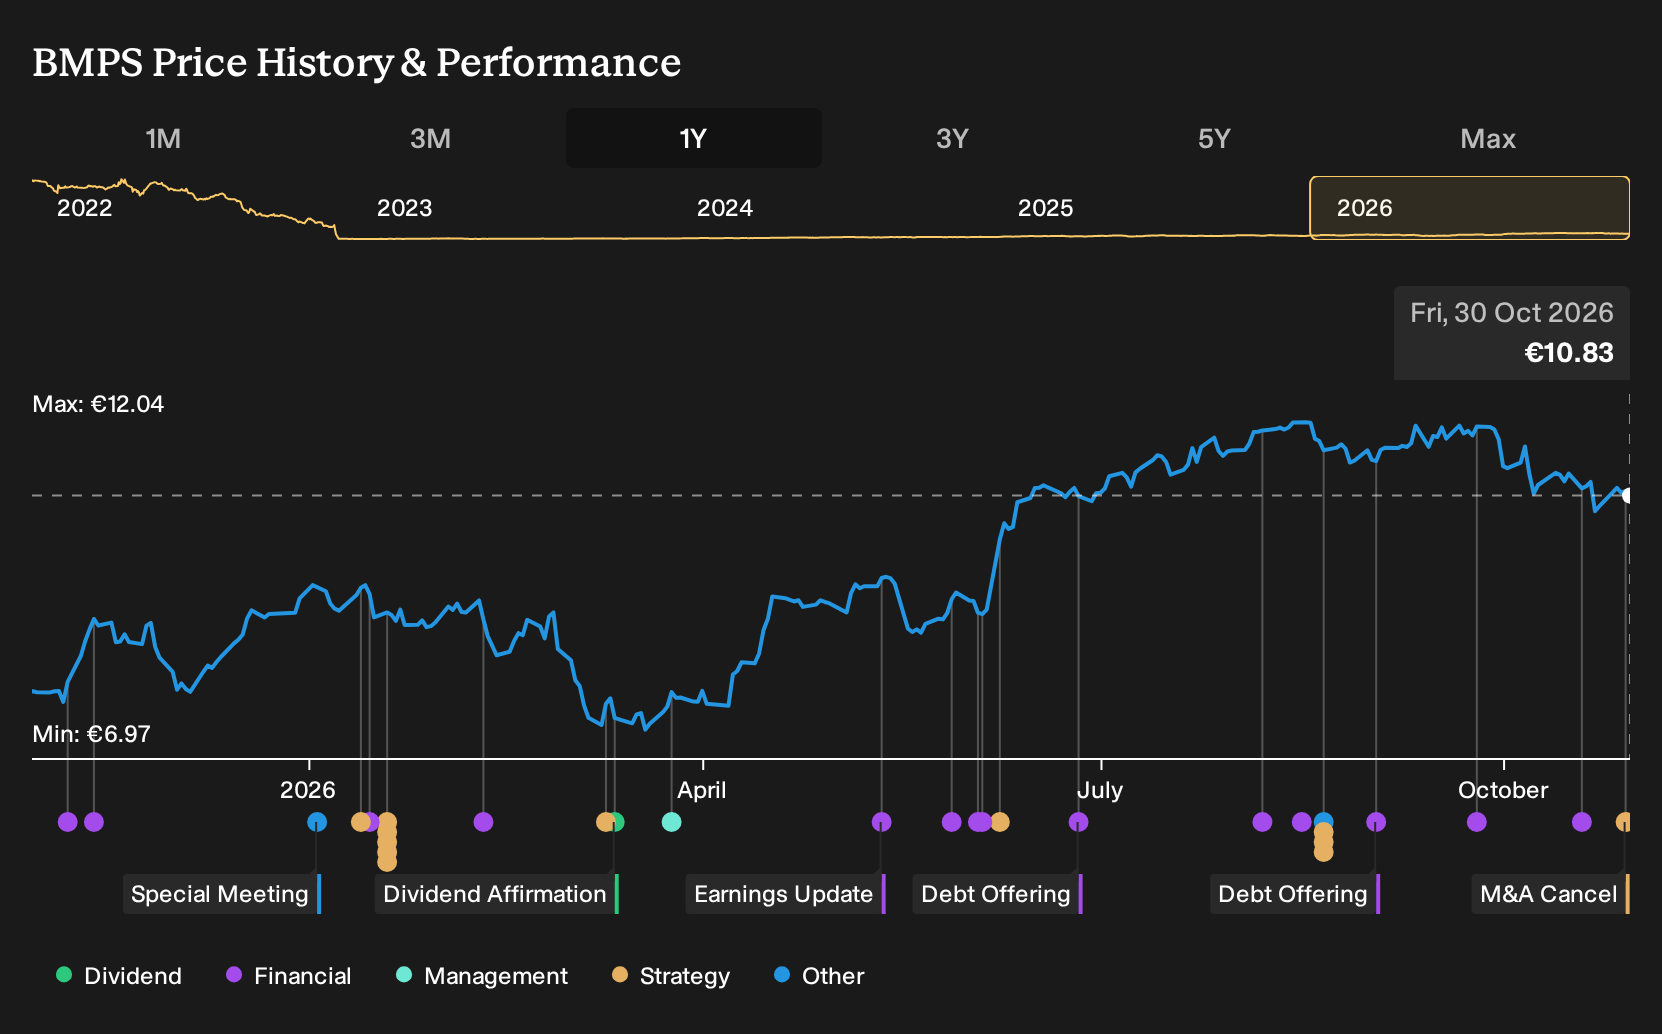
What The Facts Did To The Banca Monte dei Paschi di Siena Argument
Intesa Sanpaolo’s unsolicited bid for Banca Monte dei Paschi di Siena, later raised to €35b with a 12.5% premium, leaned toward the bullish story that consolidation value and potential synergies mattered. Resistance to Monte Paschi’s own acquisition plans for Banco BPM and Banca Generali, plus the board’s view that Intesa’s initial offer premium was limited, pushed back against the rosiest takeover assumptions. The evidence cut both ways.
The key hinge here was not a margin print, but whether external buyers validated the bank’s future earnings power. For any other lender, you would watch how takeover offers, branch disposals, and required stake thresholds line up against earlier P/E and Fair Value assumptions before trusting a merger driven narrative.
What Today's Banca Monte dei Paschi di Siena Price Already Assumes
Today Banca Monte dei Paschi di Siena trades at €10.83 after a 57.2% gain over the past year. The selected Narrative places its Fair Value above that level, based on a consolidation story that leans heavily on Mediobanca, Banco BPM and Banca Generali plans.
That view argues today’s price still does not fully credit Banca Monte dei Paschi di Siena successfully converting those planned banking combinations into durable earnings and fee income.
"The main thing that has to go right is that Banca Monte dei Paschi di Siena converts the planned cost and revenue synergies from the Mediobanca, Banco BPM and Banca Generali transactions into sustainable earnings while keeping asset quality and capital ratios within the guided ranges."
The price and this Narrative do not agree. → Uncover what this Narrative says Banca Monte dei Paschi di Siena is actually worth
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 31% below our estimate - channels tax-efficient capital into renewable energy and long-duration infrastructure assets.
- Company 2 - 44% below our estimate - expands a multi-brand electric vehicle range while automating assembly with advanced robotics.
- Company 3 - 47% below our estimate - targets modular construction and energy contracts using digital bidding tools to protect margins.
That is three of the list. See every one of the 203 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com