


Gibson Energy (TSX:GEI) Could Be 2% Overvalued As Record Q2 EBITDA Lands
Gibson Energy (TSX:GEI) has reported record adjusted EBITDA for Q2 2026, with long-term, take-or-pay infrastructure contracts and assets such as Chauvin and the Hardisty Connection now shaping the investment story.
Gibson Energy’s recent Q2 2026 update lands after a strong run, with a 30-day share price return of 11.86%, a year-to-date share price gain of 33.01%, and a 1-year total shareholder return of 51.48%, suggesting momentum has been building as investors reassess its contracted infrastructure earnings and dividend profile.
Scan how Gibson Energy’s contract-backed model compares with other infrastructure-heavy plays by reviewing our curated 39 power grid technology and infrastructure stocks riding similar demand for energy transport and storage capacity.
The recent surge in Gibson Energy raises a simple tension. Are investors finally pricing in the contracted infrastructure earnings, or is sentiment running ahead of what this record EBITDA and dividend framework support today?
Most Popular Narrative: 2% Overvalued
Gibson Energy last closed at CA$34.05 compared with a narrative fair value of CA$33.43, which frames the recent rally as slightly ahead of that central estimate while still anchored by contracted infrastructure cash flows and the dividend framework.
The main thing that has to go right is that Gibson Energy maintains high utilization and renewal rates at its key terminals and pipelines so fee-based cash flows comfortably cover dividends, interest and growth capital.
The current numbers on dividend yield, payout ratio, leverage and analyst targets together suggest that Gibson Energy’s share price already reflects a valuation that is viewed as fair with a moderately positive outlook.
See why 19 investors see Gibson Energy as 2% overvalued.
Result: Fair Value of CA$33.43 (OVERVALUED)
Still, Gibson Energy’s reliance on North American crude volumes, along with its 4.4x infrastructure leverage and an 88% payout ratio, leaves little room if contracts or refinancing terms disappoint.
Find out about the key risks to this Gibson Energy narrative.
Another View: Gibson Energy On Cash Flows
The first yardstick calls Gibson Energy about 2% overvalued around CA$34.05 versus a CA$33.43 fair value. A very different picture comes from our DCF model, which estimates future cash flow value at CA$78.29 per share, implying the stock trades far below that cash flow based view.
Both readings use reasonable inputs yet point in opposite directions. The question is which one better matches how you think Gibson Energy’s contracts, leverage and dividend will play out over time.
Look into how the SWS DCF model arrives at its fair value.
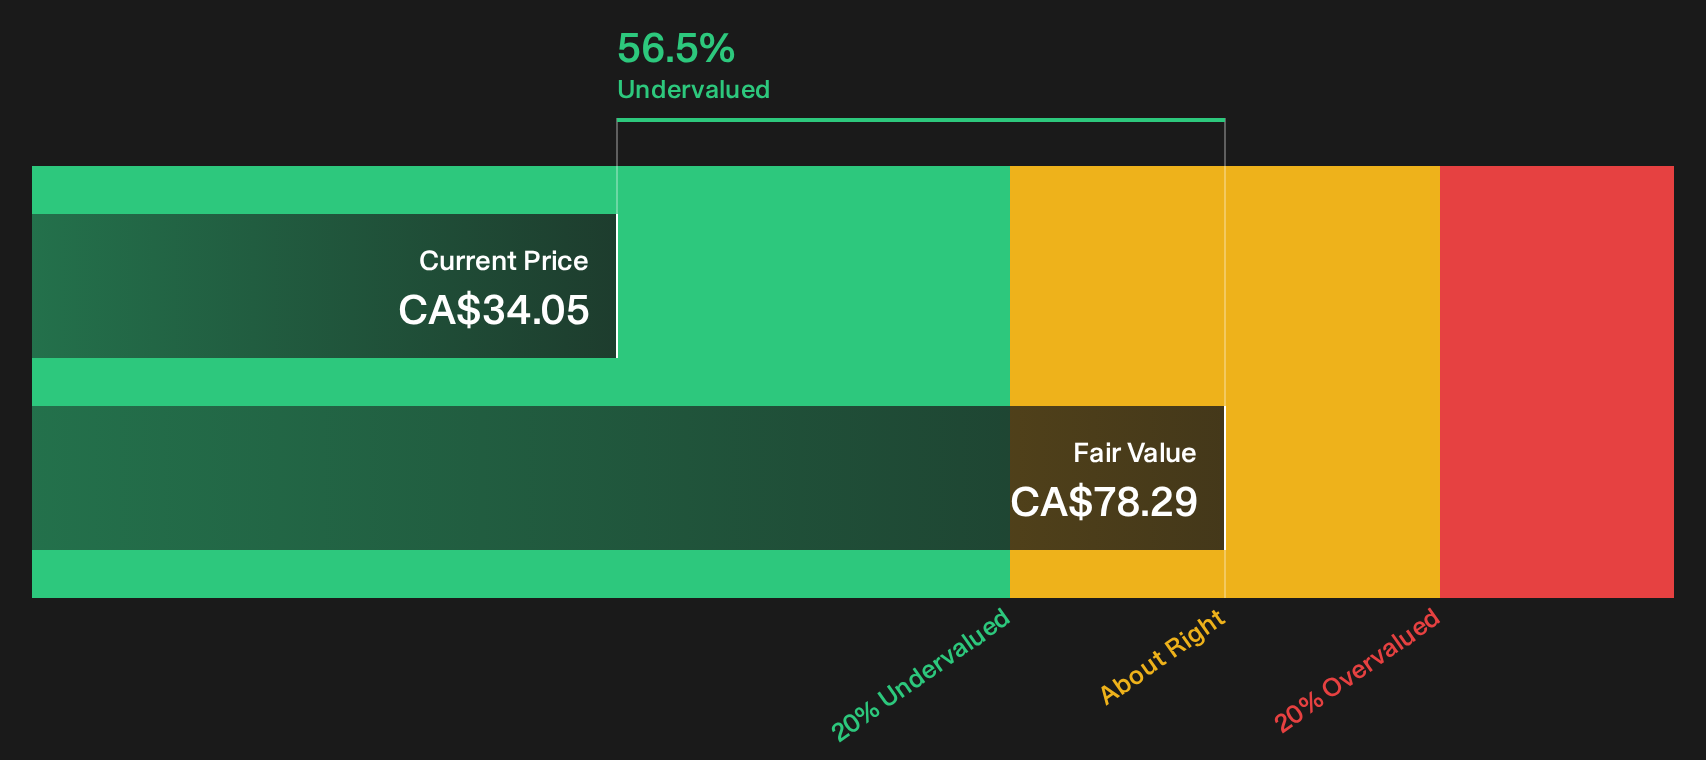
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Gibson Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Gibson Energy feels finely balanced, consider acting promptly: review the numbers yourself, then weigh the 3 key rewards and 2 important warning signs.
Looking for more Gibson Energy sized investment ideas?
Do not stop your research with Gibson Energy. Broaden your watchlist now by scanning other data driven ideas that could complement or contrast this infrastructure story.
- Target resilient upside with a 7 resilient stocks with low risk scores that keeps volatility in check while you focus on consistent business quality.
- Hunt for pricing power by reviewing a 3 high quality undervalued stocks where fundamentals and valuation line up more cleanly than the market narrative suggests.
- Strengthen your income stream by assessing a 3 dividend fortresses built around companies that prioritise returning cash to shareholders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com