


Altius Minerals And 2 Canadian Lithium Stocks To Own
Oil traders are bracing for a wild week as Brent crude moves toward $120, and that kind of energy price strain keeps battery metals in sharp focus. Higher fuel costs push governments and companies to keep backing electrification, which leans heavily on lithium. If you care about long term electrification themes, this is a moment to pay attention. This article walks through three Canadian focused lithium miners from the screener that may be worth a closer look.
The three lithium miners below are just a starting sample. The full screen surfaced 13 more companies with equally compelling narratives that are not covered here. To go wider than this shortlist, identify patterns, and analyze which ideas best fit your own thesis, head straight into the Lithium Mining screener.
Altius Minerals (TSX:ALS)
Overview: Altius Minerals is a diversified royalty company that collects long term payments from copper, potash, lithium and renewable energy assets.
Operations: Most income comes from Mineral Royalties of about CA$79 million, with roughly CA$20 million from Renewable Royalties and minimal Project Generation revenue.
Market Cap: CA$3.0 billion
For lithium investors, Altius Minerals matters because its royalty and streaming deals give you indirect exposure to battery metals without owning or operating a single mine.
"Large, long dated copper, iron ore and gold royalty exposures such as Chapada, CAMI and Arthur depend on counterparties executing significant capital programs and permitting milestones, so any delay or scope changes in these projects could push out expected volume uplifts and dampen near to medium term revenue and EBITDA trajectories."
What really shifts the story for Altius is how one less visible funding and reinvestment pressure ultimately feeds through to lithium royalty growth.
That pressure on reinvestment is only half the picture, and Altius Minerals investors who want the full lithium angle should read the full narrative for Altius Minerals for how those royalties could evolve.

Lithium Americas (TSX:LAC)
Overview: Lithium Americas is developing the Thacker Pass lithium mine and processing hub in Nevada to supply battery grade lithium to global customers.
Market Cap: CA$1.1 billion
Lithium Americas focuses primarily on Thacker Pass, a single large lithium mining and processing project that fits within a global lithium supply theme. Forecasts point to no near term revenue and ongoing losses. Investor attention is on whether this heavily funded build out ultimately delivers a cost and volume profile that can absorb its growing financing load if a single key assumption changes.
If a single assumption wobble is what worries you, start with the analysis report for Lithium Americas to see how Lithium Americas' funding runway and project economics stack up.

Evolve Royalties (CNSX:EVR)
Overview: Evolve Royalties is a Vancouver based copper focused royalty and streaming business with additional exposure to lithium bearing mining projects.
Operations: Evolve Royalties generates about CA$3.7 million from acquiring and managing royalty and similar interests, mainly sourced from Canadian assets.
Market Cap: CA$151 million
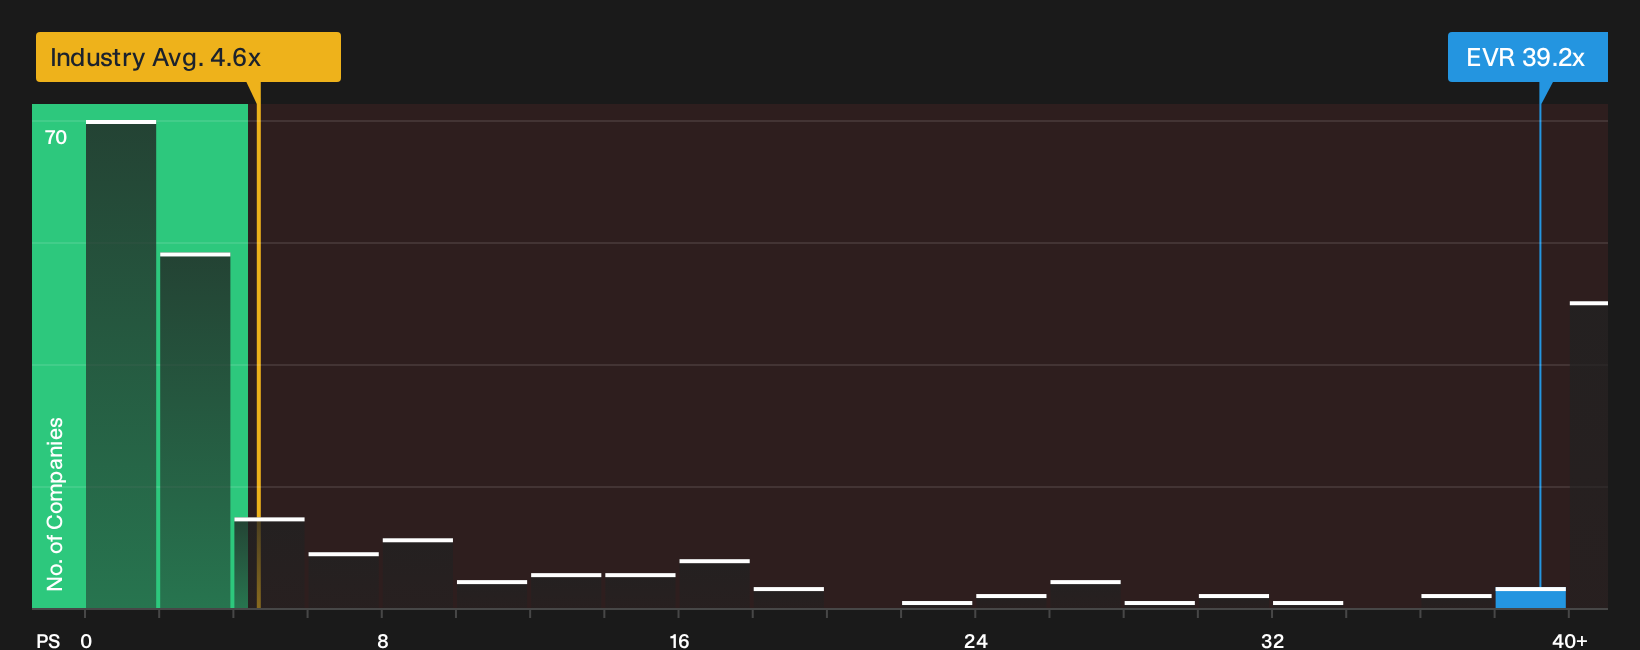
Evolve Royalties gives lithium focused investors royalty exposure to lithium linked deposits inside a broader copper and critical metals portfolio. Profitability is now established but supported by modest CA$4 million revenue and a rich 39.2x P/S. Future returns depend heavily on how one pressure point in those lithium connected royalty streams ultimately shapes cash flow visibility.
That pressure point sits at the core of Evolve Royalties' thesis, so read the 4 key rewards and 2 important warning signs (1 is major!) to see what could accelerate or stall those cash flows.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes gain momentum while most investors are still caught watching prices. Scan these curated lists while the data is under the radar for now and consider your options.
- Spot dependable income streams and stress test your dividend exposure with the 3 dividend fortresses before yields change and the best payers become fully priced.
- Track high potential stories early and weigh their strength using the 7 high quality undiscovered gems while these smaller opportunities are still flying below broad market attention.
- Follow major infrastructure trends by sorting through the 39 power grid technology and infrastructure stocks while sentiment is developing and long term projects are being funded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com