


Finance Shake Up Might Change The Case For Investing In Vistry Group (LSE:VTY)
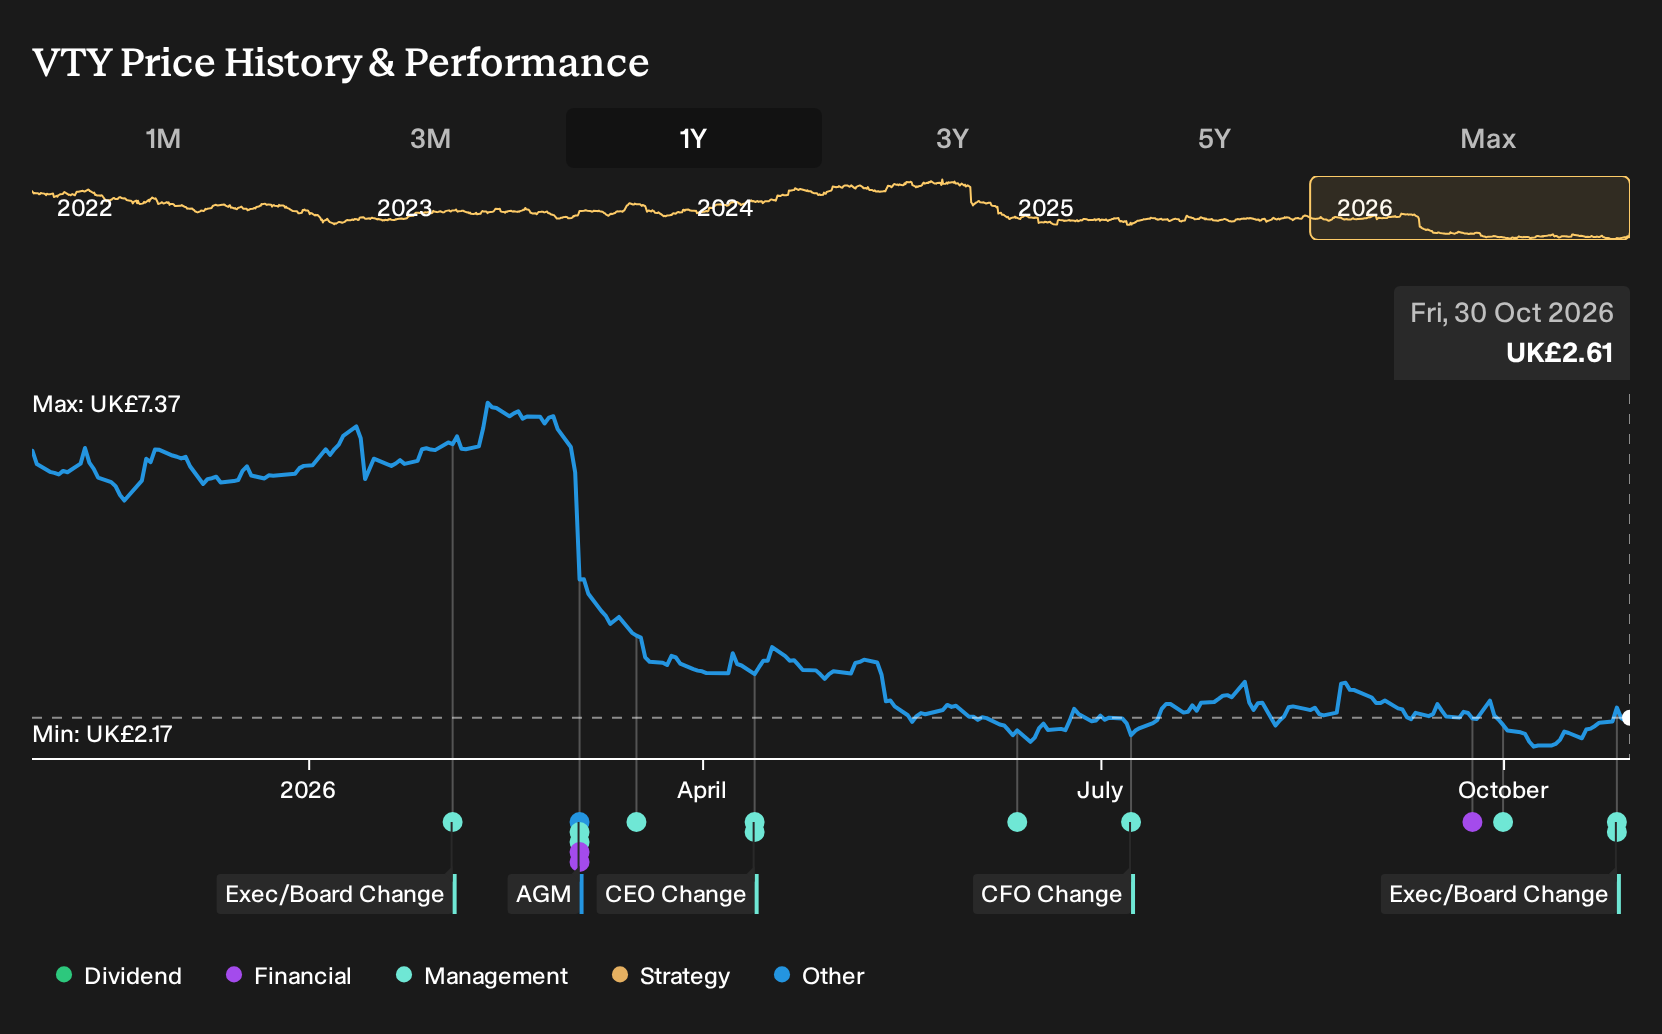
- Vistry Group has reshaped its finance leadership, appointing Severn Trent CFO Helen Miles as executive director and future CFO, while bringing in experienced real estate finance leader Robert Allen as interim CFO and board member from 27 October 2026.
- The pairing of a future FTSE 100 finance chief with an interim CFO steeped in property and regeneration work gives Vistry Group a finance bench with direct relevance to its partnerships focused housing model and capital light plans.
- Now the focus turns to how Vistry Group's investment narrative around capital light partnerships could be influenced by Helen Miles' appointment.
Scan how other housing and infrastructure players compare on balance-sheet strength and capital discipline with Vistry Group by reviewing the hand-picked list of solid balance sheet and fundamentals (10 results).
Vistry Group Investment Narrative Recap
To stay invested in Vistry Group, you need to be comfortable with a capital light partnerships model that still has moving parts on profitability, cash generation and regional clean up. The near term story hinges on improving margins after guidance for adjusted profit before tax was cut to a maximum of £125m for 2026 as discounting and deal deferrals bit.
The biggest operational risk remains execution. The group is reshaping its land bank, exiting parts of Southeast England and working through about £470m of related charges alongside a £475m goodwill impairment. At the same time, it is targeting lower net debt. The new finance line up looks important for delivering that plan rather than changing the short term catalyst.
The most relevant development is Helen Miles agreeing to join Vistry Group as future CFO, with Robert Allen stepping in as interim CFO until 2027. This matters for a business that is trying to push a partnerships focused model, shrink a 51,000 plot land bank, release about £300m of capital and reduce average daily net debt over time.
Investors now have a clearer sense of who will own the numbers as Vistry Group works toward overhead savings, capital discipline and a more predictable earnings profile. The recent losses, charges and guidance cut keep execution risk high, so attention is likely to sit squarely on whether this refreshed finance leadership can keep delivery on track.
Vistry Group's narrative projects £3.7 billion in revenue and £134.9 million in earnings by 2029. This projection assumes 2.7% yearly revenue growth and an earnings change of about £635 million, from the current earnings loss of £500.3 million to the 2029 consensus figure.
Uncover why Vistry Group's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts building safety and 2026 clean up costs front and centre. Those more cautious analysts were working off around £3.6b of 2029 revenue and £167.6m of earnings, yet still landed on a £1.60 target. They saw Helen Miles’ future at Vistry Group as a variable that could reshape those assumptions.
Explore 4 other Vistry Group fair value estimates, including one that suggests as much as 39% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vistry Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vistry Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistry Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vistry Group?
Once you have formed a view on Vistry Group, it can help to compare it with other opportunities that match your risk appetite and income goals using the Simply Wall St Screener.
- If you want potential mispricing with quality fundamentals, start by reviewing 12 high quality undervalued stocks that combine financial strength with discounted valuations.
- For a focus on income, check companies in the 5 dividend fortresses that aim for yield levels many investors look for when building a cash flow focused portfolio.
- When capital preservation matters most, narrow your research to the 5 resilient stocks with low risk scores that score well on resilience and balance sheet quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com