


Valeura Energy (TSX:VLE) Secures Lower Rig Rates, Is The Stock Still Cheap?
Valeura Energy (TSX:VLE) has just locked in a three-year deal for a high-spec jack-up drilling rig at meaningfully lower day rates, focusing attention on how reduced future drilling and development costs might affect the current share valuation.
Recent trading reflects that optimism. Valeura Energy’s 30-day share price return of 17.73% and 90-day gain of 38.42% build on a 114.22% year-to-date share price move and a very large 5-year total shareholder return. This suggests momentum has been strong as investors reassess the risk and reward profile around new contracts and existing production assets.
Spot 7 high quality undiscovered gems that, like Valeura Energy after its rig deal, could be repricing as the market reassesses their cost base and earnings power.The question now is blunt. Has the Valeura Energy share price surge simply ridden a wave of optimism, or does it line up with what the earnings and cash flows suggest the business is worth?
Most Popular Narrative: 12% Undervalued
At a last close of CA$17.33 against a narrative fair value of CA$19.61, Valeura Energy is priced below what the widely followed thesis suggests. This puts the focus squarely on whether future projects and lower rig costs can justify that gap.
The new three year high spec jack up drilling rig contract at roughly 30% lower day rates than the current rig is expected to reduce future drilling and development costs per barrel, which can support wider net margins and stronger free cash flow for Valeura Energy if activity levels are sustained.
See why 15 investors see Valeura Energy as 12% undervalued.
Result: Fair Value of CA$19.61 (UNDERVALUED)
Still, the Valeura Energy story carries real execution risk if regulatory approvals slow Thai projects or if unhedged oil prices move sharply against operating costs.
Find out about the key risks to this Valeura Energy narrative.
Another View: What Multiples Say About Valeura Energy
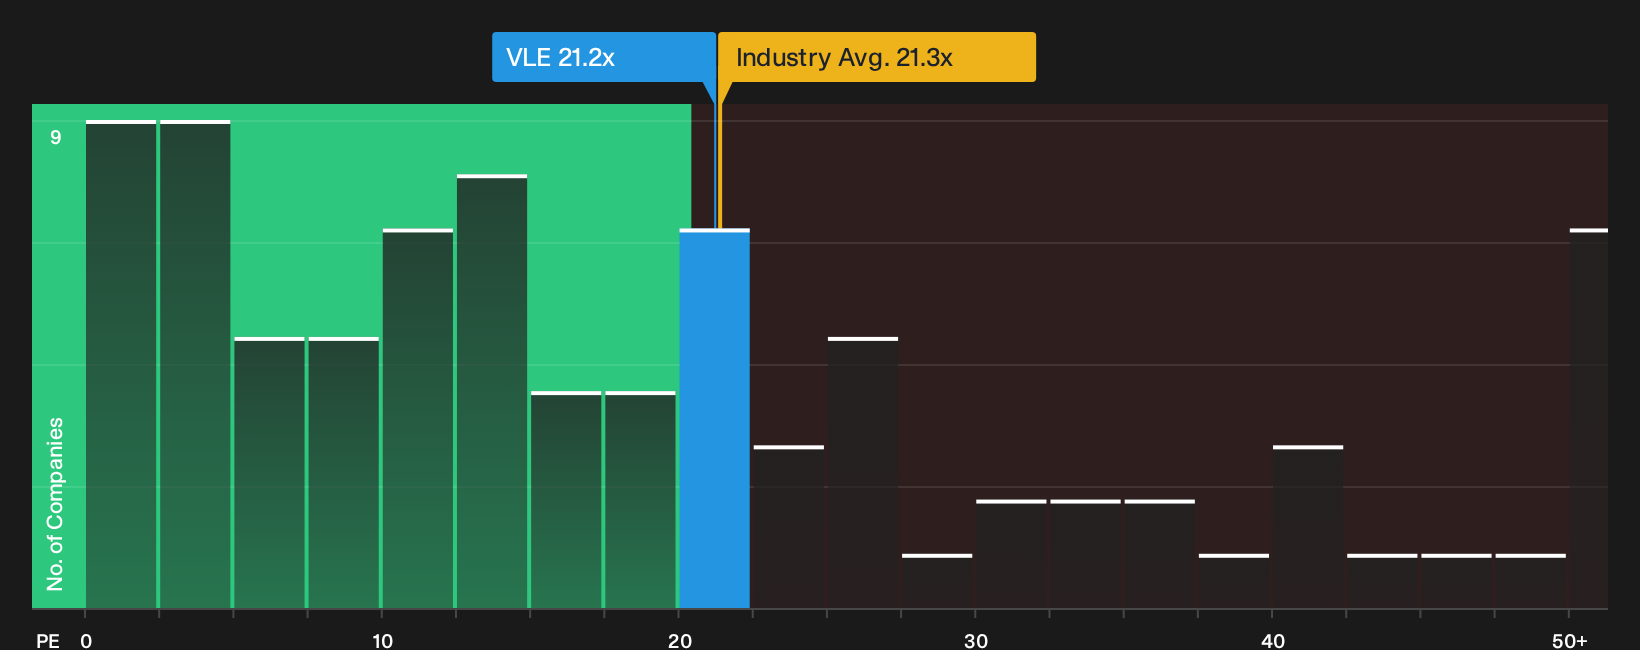
The story looks different when you shift from narrative fair value to simple earnings multiples. Valeura Energy trades on a P/E of 21.2x, which is almost identical to the Canadian Oil and Gas sector at 21.3x, yet well above its own fair ratio of 8.8x.
That gap implies the share price is rich compared with what the fair ratio suggests the market could move towards, even though it lines up with peers. If the DCF-style narrative points to upside while the earnings multiple indicates possible valuation risk, which signal do you treat as more important?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Valeura Energy is clearly split, with both upside potential and real risks on the table. Move fast and stress test the data against your own expectations by weighing 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Valeura Energy?
If you stop with Valeura Energy, you risk missing other setups where price, balance sheet strength, and income potential line up in your favor.
- Target fresh upside by scanning 3 high quality undervalued stocks that pair quality fundamentals with prices that lag behind their underlying business strength.
- Prioritize staying power and sleep-at-night resilience with a focused 7 resilient stocks with low risk scores that screens for robust financial profiles and lower volatility.
- Build a watchlist of potential income workhorses by reviewing 3 dividend fortresses that combine higher yields with disciplined payout histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com