


Brunswick (BC) Q3 Earnings Lift Margins But Tariff Costs Linger
Brunswick came into this earnings season with a mixed story. The stock had slipped over the past three months but still sat modestly higher over the last week. Then Q3 2026 hit. Shares edged up about 1% after the release, a restrained move for a leisure manufacturer that just posted about $1.5b in quarterly sales and adjusted earnings per share of $1.58.
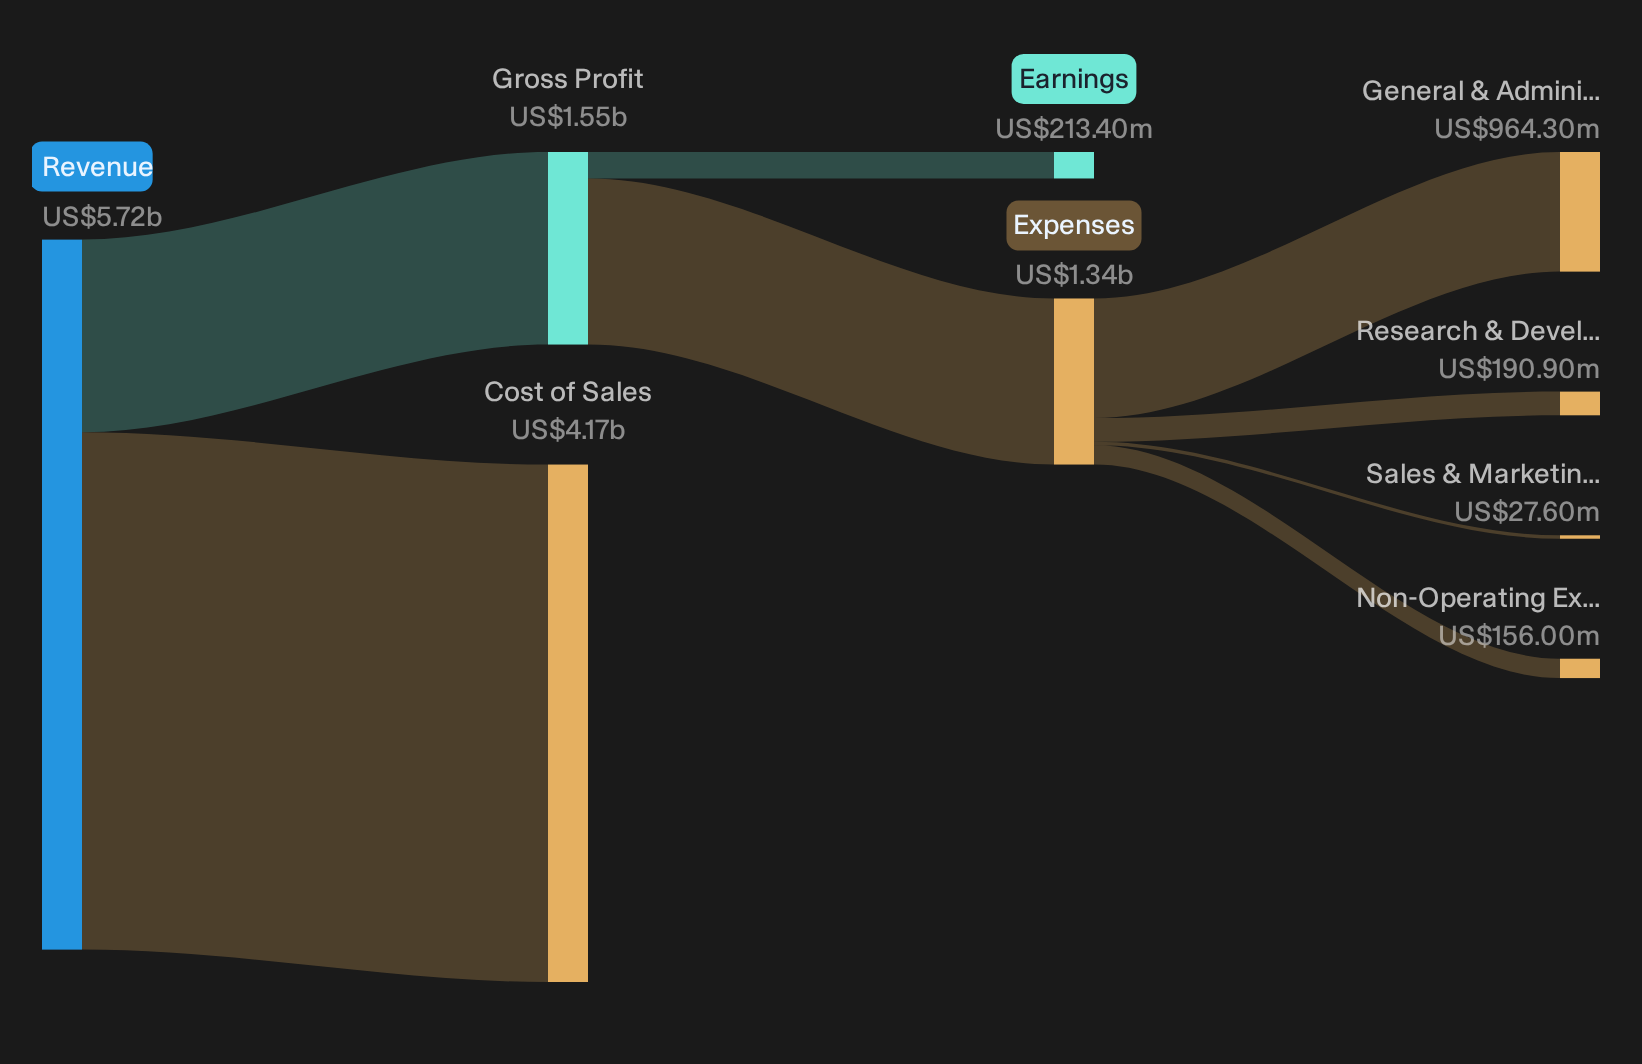
The headline is not the uptick in the share price. It is the sharp improvement in profitability, with adjusted operating margin reaching 10.1% and free cash flow of $140m. This puts the long running thesis about pressure on big ticket recreational spending under a fresh spotlight.
You may appreciate Brunswick's stronger margins and solid free cash flow but still be concerned about how sensitive big-ticket leisure spending can be. Use our list of solid balance sheet and fundamentals stocks (25 results) as a benchmark while you look for peers that combine resilient finances with consistent cash generation.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,453.9m vs. US$1,360.2m (up 6.9%)
- Net Income, excluding extra items (Q3 2026 vs Q3 2025): US$65.6m vs. a loss of US$234.3m (returned to profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.01 vs. a loss of US$3.57 per share (moved back into positive territory)
- Adjusted Operating Margin (Q3 2026 vs Q3 2025): 10.1% vs. 7.8% (improved by 230 basis points)
Ask Charlie what raised Brunswick’s earnings guidance without higher sales.
Brunswick’s Mix Shift Starts To Show Up In Margins
The bullish story around Brunswick hinges on mix and recurring earnings doing the heavy lifting. That ambition is clearly stated as:
"The main factor that has to go right is that Brunswick continues to deepen its premium and high-horsepower mix while scaling recurring and technology rich products, so that earnings growth comes from share gains, pricing, cost actions and synergies rather than depending on a rebound in unit volumes."
Q3 margin gains across Mercury, Engine P&A and Navico, plus higher contribution from Freedom Boat Club and other Business Acceleration units, point to this mix shift starting to work. The raised full year EPS guide, with revenue guidance unchanged, reinforces that earnings are increasingly coming from efficiency and richer product exposure rather than simple volume.
The price and this Narrative do not agree. → Uncover what this Narrative says Brunswick is actually worth.
Brunswick Tariff Drag Still Clouds Recurring Upside
Bearish analysts worry that Brunswick’s recurring engine, electronics and shared access earnings will be blunted by higher tariffs and input costs rather than flowing cleanly into profit.
"Even as Freedom Boat Club and other shared access and lifecycle services add recurring revenue per boat and widen Brunswick’s reach, the extra tariff burden and higher input costs mean each additional unit of participation may contribute less incremental profit than investors expect, putting pressure on long term margin and free cash flow targets."
Q3 tells a mixed story. Margins improved across Propulsion, Engine P&A and Navico, and free cash flow reached US$140m. Yet management still pegs 2026 net incremental tariffs at about US$40m and flags fresh material inflation. This means the cost headwind that underpins the bearish view has not cleared and has only been managed for now.
Hunt For Quiet Margin Stories
Brunswick shows how earnings quality can improve even when big ticket demand questions linger. The real opportunity sits in finding stocks that could be mispriced before the crowd pays attention.
- Company 1 - 38% below our estimate - expands coconut based drinks into mainstream shelves while scaling private label partnerships across retail and foodservice.
- Company 2 - 35% below our estimate - supplies the GPU hardware and software stack that many data centers rely on to run large scale AI workloads.
- Company 3 - 21% below our estimate - packages advanced optical components that hyperscalers and telecom providers need as they ramp higher bandwidth data connections.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com