


Has Albertsons Companies (ACI) Fallen Far Enough on Sales?
Albertsons Companies has seen its share price fall over several years. With fresh moves in the boardroom and changes to its product offering, the open question is whether the current valuation is properly anchored to its sales. For anyone watching the stock, the key issue is how that sales base supports the price investors are being asked to pay today.
- The share price has declined 42.4% over the past 5 years, which raises a basic question about how the market is weighing Albertsons Companies against the sales it generates.
- The new Albertsons for U+ subscription program is designed to lean on digital grocery sales. This can influence how durable and repeatable its revenue stream looks when you line it up against the stock price.
- There is a second opinion on Albertsons Companies worth weighing. See what analysts think Albertsons Companies's shares could be worth.
The stock's next move may depend on whether Albertsons Companies' current share price is well supported by its sales when set against the Fair Ratio benchmark.
If you are weighing whether Albertsons Companies’ current price is justified by its sales, it can help to compare that against other 29 high quality undervalued stocks for broader context.
Is Albertsons Companies a Bargain on Sales?
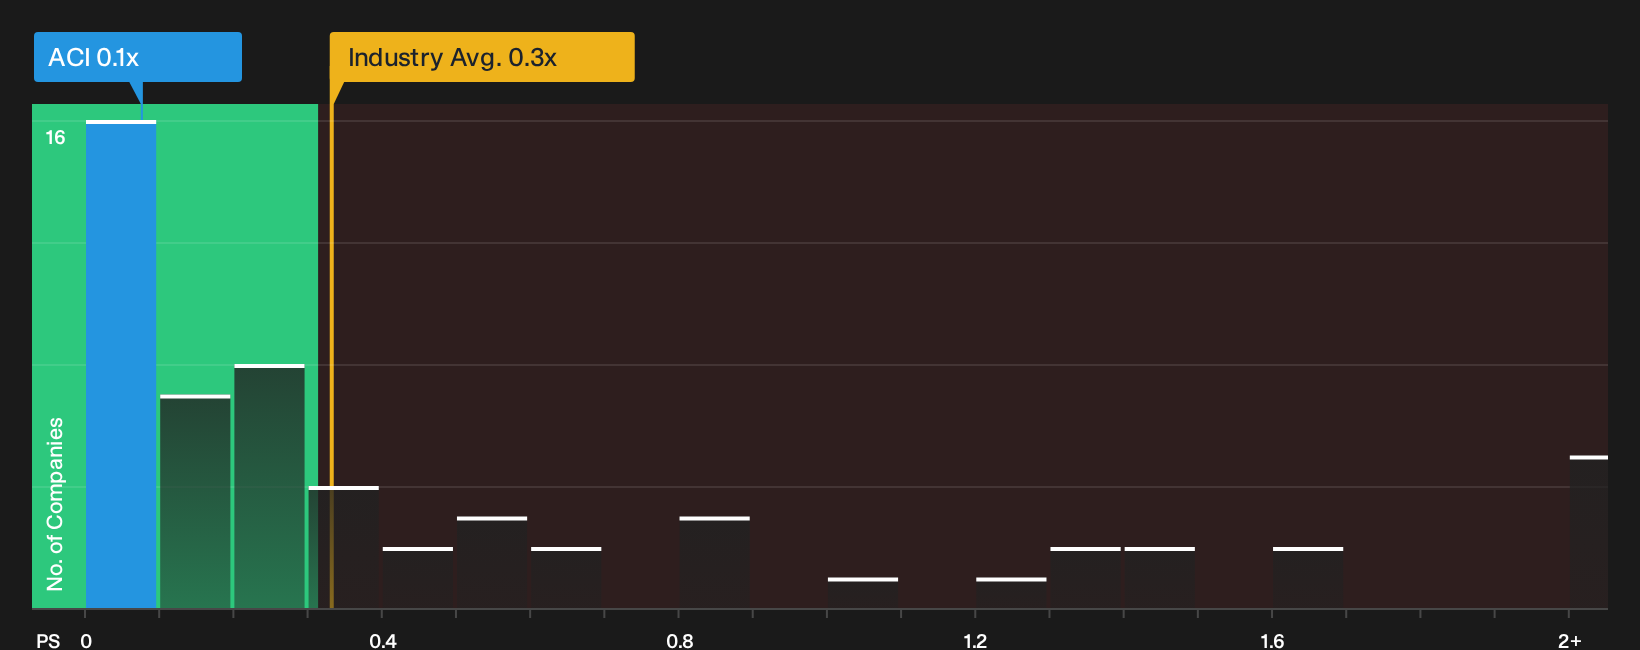
The P/S ratio fits Albertsons Companies because groceries revolve around steady revenue volume, so comparing price to sales gives a clean read on what investors pay for each dollar sold. On this measure, the stock trades on a P/S of 0.1x, far below the Consumer Retailing industry average of 0.3x and also below the peer group at about 1.4x.
That low multiple sits under the Fair Ratio benchmark, which is the P/S level you might expect once growth prospects, profit margins, size and risk are baked in. Because the recent board shake up and the arrival of Meg Whitman come against a backdrop of weak share performance, the current discount suggests the market still prices Albertsons cautiously despite those governance changes. For anyone assessing whether that gap is justified, the key question is how dependable its sales base looks alongside the newer Albertsons for U+ subscription revenue stream. Explore the numbers behind Albertsons Companies's P/S valuation.
The Albertsons Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Albertsons Companies pick up where this pricing puzzle leaves off. They spell out what kind of future path for growth, profitability and earnings would need to play out for the stock to trade materially higher or lower than today’s level, using each scenario as a clear thesis about Albertsons Companies' business that you can track over time on the Community page rather than a one off snapshot.
Albertsons Companies splits opinion, with one camp seeing more upside from digital and loyalty economics, while the other leans into execution risk and pricing pressure.
Bull case: 7% undervalued
"Growth in loyalty and retail media, with more than 51 million loyalty members who spend several times more than non members…"
Discover why this Narrative puts Albertsons Companies at 7% undervalued.
Bear case: 31% overvalued
"Digital and e commerce are now profitable and growing, yet Q1 fiscal 2026 still saw a 23 basis point gross margin decline tied in part to mix…"
Explore why this Narrative puts Albertsons Companies at 31% overvalued.
Before acting on Albertsons Companies' valuation, one more factor deserves attention
Price and sales only tell part of the story for Albertsons Companies, because Simply Wall St's broader checks have flagged risks that could change how you weigh the whole picture. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com