


Gilead (GILD) Stock Rallies As Q3 Results Fuel HIV Growth Debate
Gilead Sciences stock came into Friday already on a tear, with a 90 day gain above 30%, then tacked on another 3.1% after the Q3 2026 release as traders rushed to price in fresh numbers. The headline is simple. Base business product sales hit US$8.2b and total product sales reached US$8.3b, both supported by double digit HIV and oncology demand.
In the short term, the move looks like a victory lap. Over a multi year lens, the more important story is whether this strong product engine can pull a still loss making group back to sustainable earnings and justify the current valuation debate.
Love Gilead Sciences’ product momentum but concerned that a still loss making group may not fit your risk profile? Screen for companies that pair robust demand with cleaner profitability using the 30 resilient stocks with low risk scores.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$8.3b vs. US$7.8b (up about 7%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$2,429m vs. US$3,052m (declined about 20%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.96 vs. US$2.46 (fell about 20%)
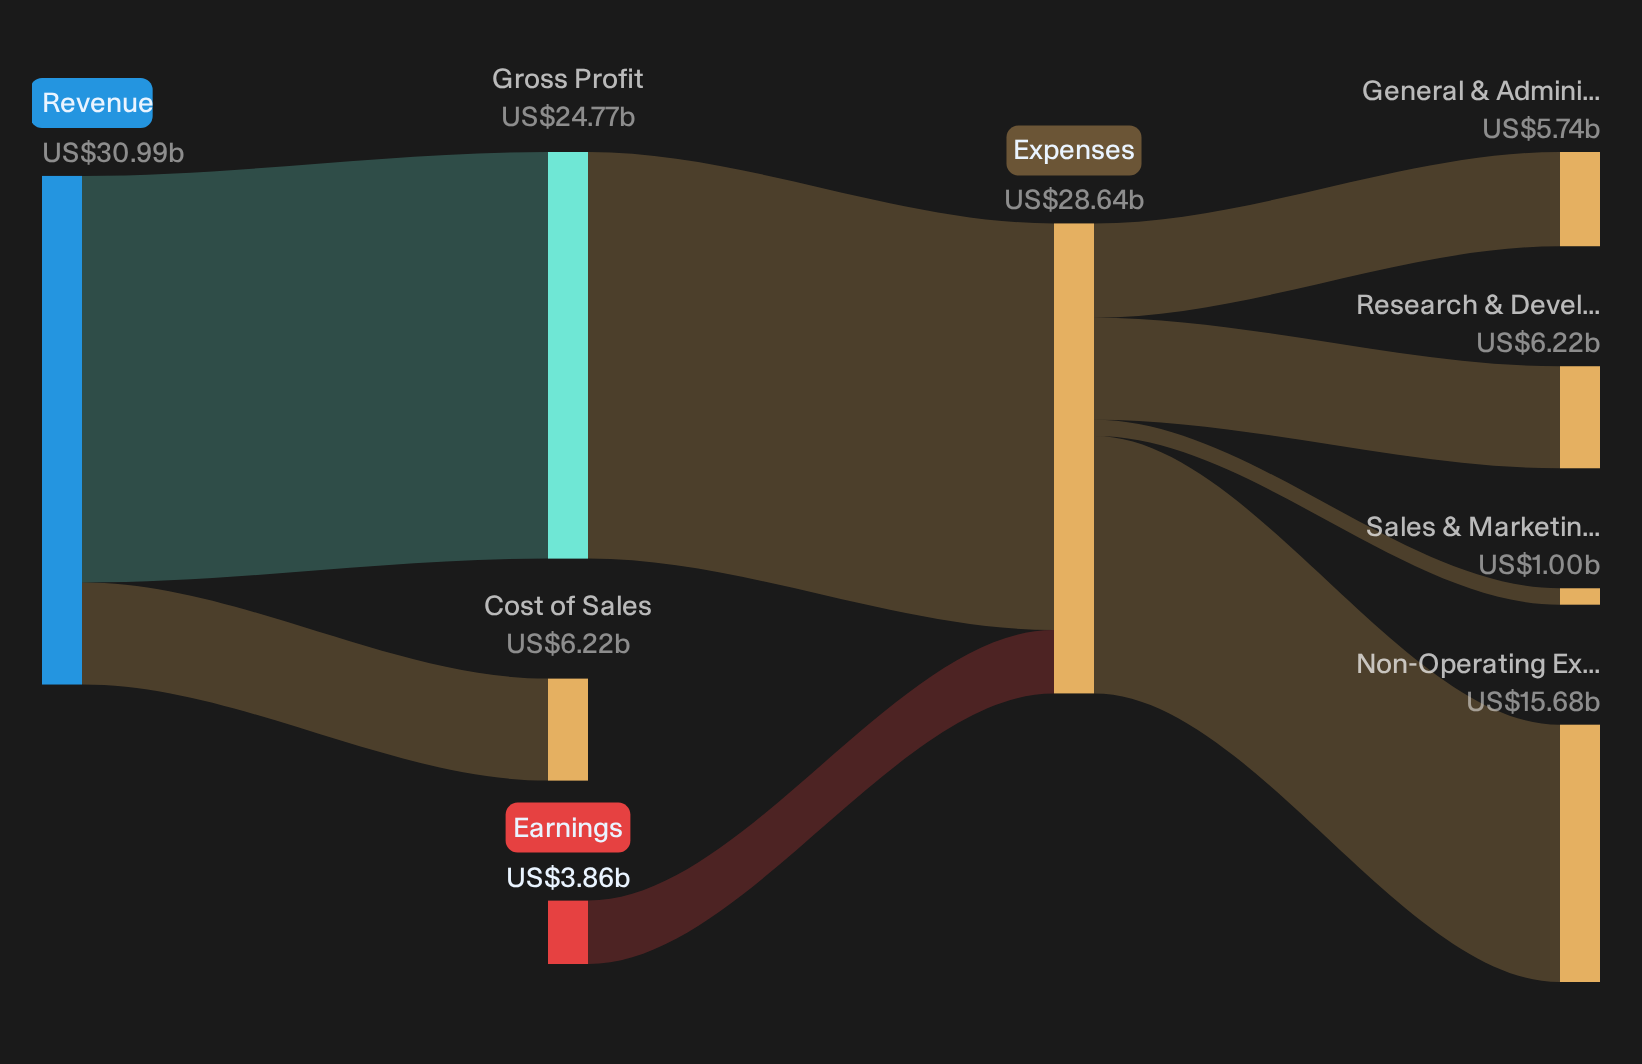
- Trailing 12 Month Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): loss of US$3,862m vs. profit of US$8,110m (swing into loss on a trailing basis)
Yeztugo is already tracking toward $1B in its first year. Ask Charlie what Gilead’s Yeztugo surge means for HIV rivals.
Gilead Sciences Bull Case Meets Key HIV Milestones
Supporters argue Gilead Sciences can turn long acting HIV and oncology assets into a broader, more durable revenue mix over time.
"The main thing that has to go right is that Gilead Sciences converts its expanded HIV PrEP opportunity and emerging oncology launches into sustained uptake that more than offsets pricing pressure and competition."
Q3 results move this thesis from concept to evidence. HIV sales reached US$6.2b, up 18% year on year, with Biktarvy at US$4.1b and U.S. treatment share at 53%. PrEP revenue nearly doubled, with Yeztugo already tracking toward roughly US$1b this year and combined PrEP products around a US$4b run rate, while Trodelvy closed in on a US$2b annual pace.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
Gilead Sciences Bear Case: Policy Fears Vs Profit Reality
Bearish investors worry that Gilead Sciences will not grow HIV treatment enough to outrun U.S. policy and pricing hits.
"Bearish analysts expect headwinds from Medicare drug price negotiations and broader U.S. policy changes to keep Gilead Sciences’ HIV treatment growth constrained, with modest long-term revenue expansion and shrinking profitability reinforcing concerns about the business mix."
Q3 undercuts the idea of constrained HIV expansion, with US$6.2b of HIV sales and strong PrEP traction. The miss is on profitability. Trailing 12 month net income swung from an earlier US$8.1b profit to a US$3.9b loss, and full year GAAP EPS guidance still points to a loss as acquired IPR&D and deal costs weigh on margins.
Hunt For Mispriced Earnings Power
Gilead Sciences just showed how fast sentiment can pivot when a product story meets live numbers. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 29% below our estimate - runs a high efficiency digital banking platform that keeps adding customers as newer operations move toward breakeven.
- Company 2 - 47% below our estimate - turns intensive AI infrastructure investment into fresh advertising tools and business messaging products that reshape how clients target and capture demand.
- Company 3 - 22% below our estimate - builds electrical and communications projects that align with rising data center construction while maintaining no long term debt on its balance sheet.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com