


DaVita (DVA) Stock Slides As Q3 Earnings Meet Margin Pressure
DaVita just reported Q3 2026 and the headline is simple. Earnings power held up while the stock sold off. Shares fell about 3% today to roughly US$187.66, even as adjusted earnings per share landed at US$3.82 and adjusted operating income reached US$561 million.
Investors focused on a softer quarter to quarter earnings step down and reacted quickly. The fundamentals told a calmer story. Revenue edged to about US$3.58b and free cash flow came in at US$276 million. This keeps the spotlight firmly on one issue that really moved sentiment today: the pressure on margins from heavy technology spending.
Like the resilience in DaVita’s earnings power but uneasy about margin pressure from heavy tech spending? Check out the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,578.1m vs. US$3,420.2m (up about 4.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$222.9m vs. US$150.3m (up about 48.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.49 vs. US$2.09 (up about 67.5%)
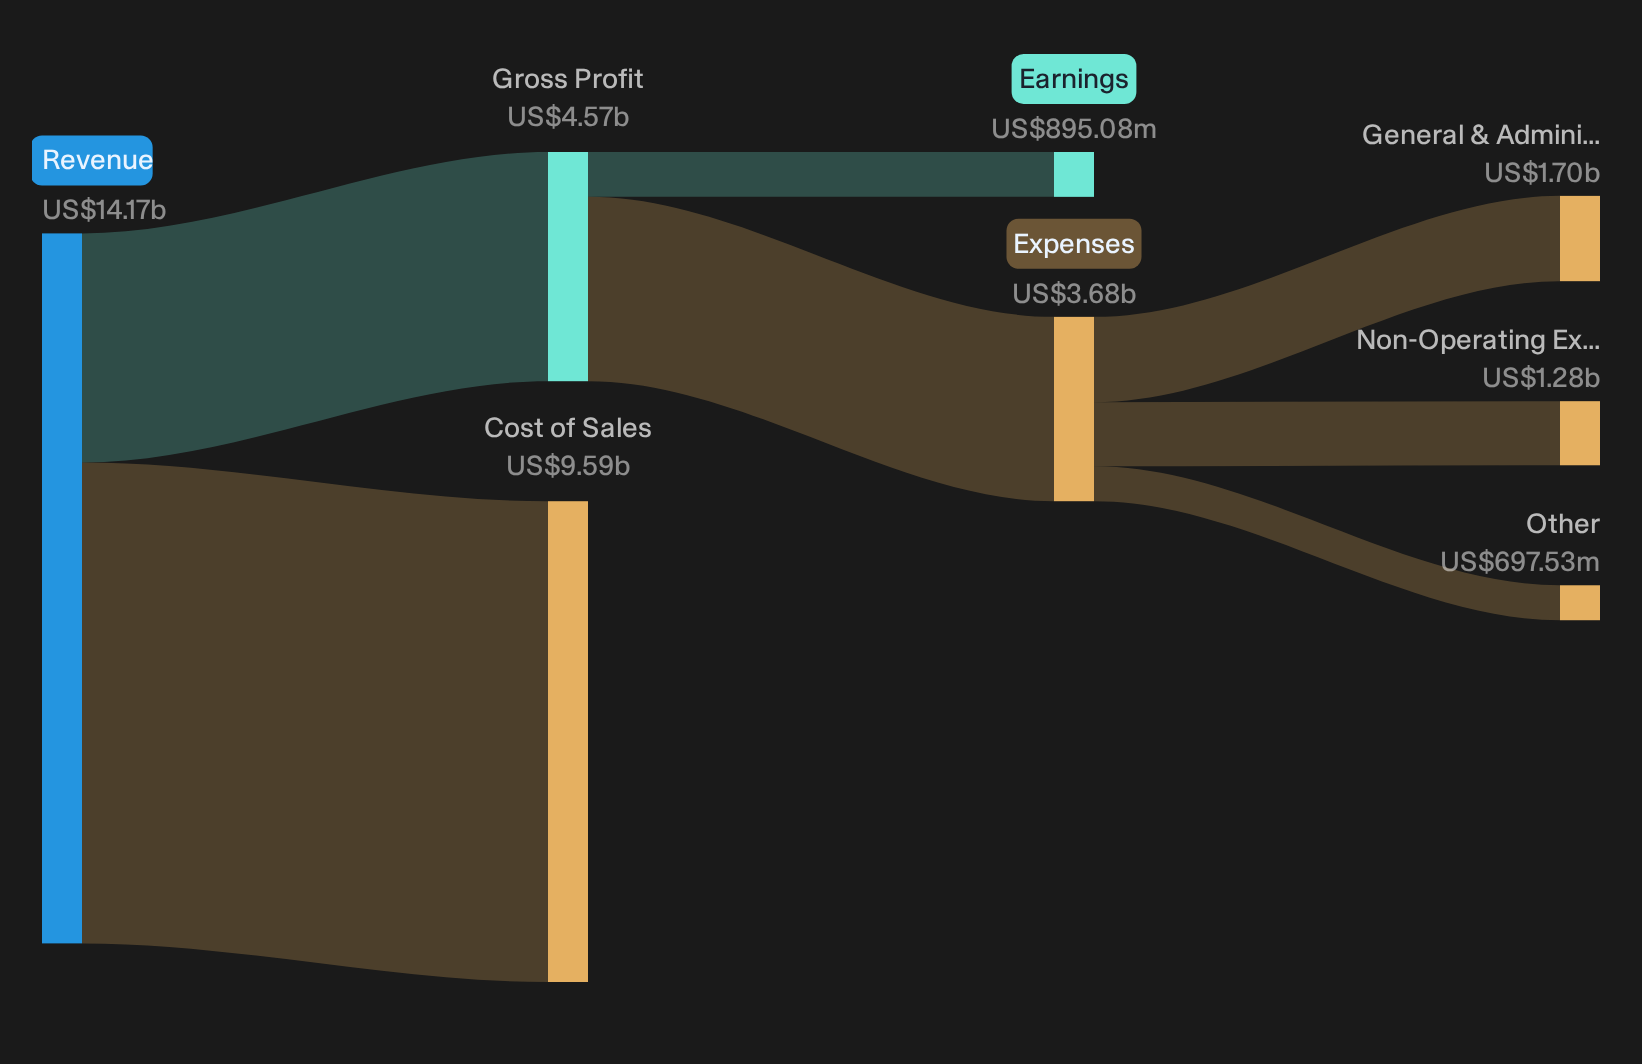
- Trailing 12-Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$895.1m vs. US$771.9m (up about 16.0%)
Earnings grab attention, but investors who care about what DaVita is really generating for shareholders usually focus on the cash coming in and out of the business. When you look at DaVita's cash flows rather than just the Q3 print, the stock could be a dramatic 39% undervalued.
DaVita’s Bull Case Hinges On Proving Capacity To Compound
The upbeat view on DaVita hinges on whether current clinical and operating projects can translate into steadier earnings power.
"The main thing that has to go right is that DaVita converts its MOTheR trial findings, CKCC performance, and technology investments into sustained treatment growth, durable IKC profitability, and slower cost-per-treatment growth despite reimbursement and payer-mix pressure."
Q3 offers partial proof. U.S. treatments rose 1.2% with mortality gains helping census, and Integrated Kidney Care is tracking at least US$65m of adjusted operating income in 2026, ahead of earlier expectations. Cost per treatment still climbed 2.4% and technology spend grew more than 20%, so the margin leg of this hypothesis is not yet showing up in the numbers.
The price and this Narrative do not agree. → Uncover what this Narrative says DaVita is actually worth.
DaVita’s Costs Validate Margin Fears, Timing Still Hurts
The cautious view centers on the idea that DaVita is paying up today without near-term financial relief.
"Large, multi year IT and AI investments that are currently lifting G&A and patient care costs may take longer than expected to translate into cost efficiencies. This would keep operating expenses elevated and limit growth in earnings and free cash flow."
Q3 results lean toward that concern. Patient care cost per treatment climbed 2.4% and technology spending rose more than 20%, while management still sees no material dialyzer or AI profit benefit before 2028. Guidance for 2026 free cash flow of US$1.0b to US$1.25b appears solid, and at the same time margin expansion remains deferred rather than addressing the underlying concern.
Hunt For Mispriced Compounding Stories
DaVita showed how earnings strength and margin worries can pull a stock in different directions on the same day. The real opportunity is finding companies that could be undervalued before the market closes that gap.
- Company 1 - 38% below our estimate - expand branded and private label coconut drinks as retailers consolidate sourcing in a fast growing category.
- Company 2 - 46% below our estimate - deepen relationships with merchants that centralize emerging market payment flows onto a single local collection and payout platform.
- Company 3 - 20% below our estimate - scale account, card and asset products as banks integrate its infrastructure into channels to route more customer payment volume.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com